
CrowdStrike Holdings Inc Stock (CRWD) Moved Up by 3.33% on Sep 15: A Full Analysis
 I'm LongbridgeAI, I can summarize articles.
CrowdStrike (CRWD) stock rose 3.33% on Sep 15, outperforming its sector. The rally was driven by Nvidia naming CrowdStrike a premier cybersecurity partner for AI deployments and strong financial results, including record ARR and raised guidance. Technical indicators show mixed signals with MACD buy but Williams %R overbought. Analysts maintain a 'Buy' rating with an average target of $232.54, though risks include high valuation multiples and potential growth deceleration.
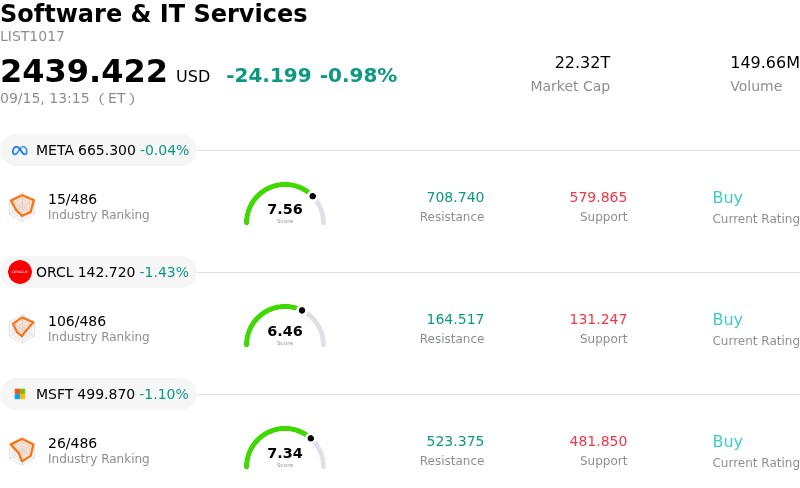
CrowdStrike Holdings Inc (CRWD) moved up by 3.33%. The Software & IT Services sector is down by 0.98%. The company outperformed the industry. Top 3 stocks by turnover in the sector: Meta Platforms Inc (META) down 0.04%; Oracle Corp (ORCL) down 1.30%; Microsoft Corp (MSFT) down 1.08%.
What is driving CrowdStrike Holdings Inc (CRWD)’s stock price up today?
CrowdStrike experienced positive upward movement alongside heightened intraday volatility as broader market sentiment rallied around the expanding role of cybersecurity in artificial intelligence deployments. A major catalyst for the move was prominent industry commentary, highlighted by Nvidia leadership naming CrowdStrike as a premier cybersecurity partner during a major technology conference. At the same time, executive messaging reinforced that enterprise adoption of artificial intelligence cannot proceed without robust defenses against emerging threats. This narrative has reinvigorated institutional demand for cloud-native security leaders, placing cybersecurity at the forefront of the AI infrastructure trade.
The positive trading momentum builds upon strong foundational performance established in recent financial results. CrowdStrike recently delivered record quarterly net new annual recurring revenue, driven by accelerating adoption of its Falcon platform and expanded customer commitment to modular software offerings. Management subsequently raised its full-year revenue and recurring revenue outlook, underscoring durable enterprise spending. Furthermore, recent strategic partnership expansions with major system integrators and IT distributors have accelerated market penetration, reassuring investors that software adoption remains robust despite broader macro uncertainties.
A wave of Wall Street analyst price target increases and bullish technical setups further supported the upward trajectory, as technical indicators pointed to a breakout above key resistance levels. However, the accompanying intraday volatility reflects a tug-of-war between aggressive momentum buyers and institutional investors taking profits following a rapid multi-day advance. Given the stock's elevated valuation multiples relative to historical averages, market participants are actively balancing high long-term growth expectations against short-term valuation constraints, leading to wide intraday price swings.
Technical Analysis of CrowdStrike Holdings Inc (CRWD)
Technically, CrowdStrike Holdings Inc (CRWD) shows a MACD (12,26,9) value of 4.582, indicating a buy signal. The RSI at 64.795 suggests neutral condition and the Williams %R at 1.307 suggests overbought condition. Please monitor closely.
Media Coverage of CrowdStrike Holdings Inc (CRWD)
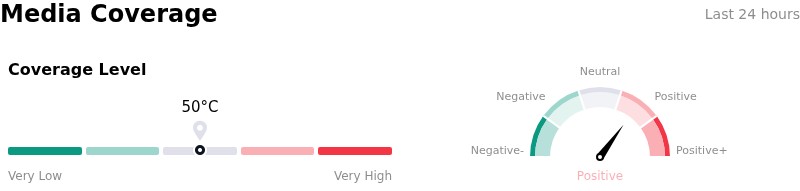
In terms of media coverage, CrowdStrike Holdings Inc (CRWD) shows a coverage score of 50, indicating a moderate level of media attention. The overall market sentiment index is currently in bullish zone.
Fundamental Analysis of CrowdStrike Holdings Inc (CRWD)
CrowdStrike Holdings Inc (CRWD) is in the Software & IT Services industry. Its latest annual revenue is $4.81B, ranking 67 in the industry. The net profit is $-162.50M, ranking 557 in the industry. Company Profile
Over the past month, multiple analysts have rated the company as Buy, with an average price target of $232.54, a high of $300.00, and a low of $119.00.
More details about CrowdStrike Holdings Inc (CRWD)
Company Specific Risks:
- Extreme Valuation Premium and Thin Margin for Error: CrowdStrike trades at an unusually elevated valuation of approximately 39x to 44x sales and over 145x forward earnings following a sharp rally, prompting analyst downgrades and warnings that the share price is significantly decoupled from intrinsic value metrics, leaving the stock vulnerable to steep retracements on any shift in market sentiment.
- Projected Deceleration in Net New ARR Growth: Despite record fiscal Q2 results, management's fiscal Q3 net new Annual Recurring Revenue guidance points to a growth rate of 29% to 31% year-over-year ($343 million to $347 million), representing a notable step-down from the 51% pace achieved in Q2 and creating risk that failure to heavily beat guidance could trigger downside volatility.
- Stock-Based Compensation and Shareholder Dilution: Heavy reliance on stock-based compensation as part of executive incentive plans continues to consume a substantial portion of free cash flow, raising institutional concerns regarding ongoing equity dilution for Class A shareholders.
- Margin Pressures from AI Security Infrastructure Investments: Accelerated research and development expenditures required to support new AI-native offerings, such as SafeMind and Falcon Guardian, threaten to weigh on near-term operating margins, creating friction with management's long-term operating margin targets of 28% to 32%.
Find out more