

Apple Earnings Preview: Can iPhone Offset Memory Cost Pressures? Wall Street's Highest Target Hits $400
 I'm LongbridgeAI. Here is the key information I extracted
TradingKey - Apple (AAPL) will release its fiscal fourth-quarter 2026 financial results after the U.S. market close on November 2, Eastern Time, and hold an earnings call at 5:00 p.m. This is not only a key moment for the market to assess iPhone demand and profit margins, but also the first time John Ternus will host Apple's earnings call after taking over as Chief Executive Officer.
Wall Street expects Apple's fourth-quarter revenue to be approximately $113.4 billion, up 10.7% year-over-year, with earnings per share expected at $1.99, up 7.6% year-over-year. The company previously provided revenue growth guidance of 9% to 11%, corresponding to approximately $111.7 billion to $113.7 billion.
iPhone Remains Core of Growth as Services Business Supports Profits
The iPhone business remains the most critical metric to watch in Apple's latest earnings report. Market expectations project fourth-quarter iPhone revenue to reach approximately $56.5 billion, a year-over-year increase of about 15%. While this growth remains substantial, it marks a cooling from the roughly 22% growth in the previous quarter, indicating that the strong momentum previously driven by upgrade demand may be normalizing.
Notably, the reporting period for this earnings report primarily spans July to September, with the iPhone 18 Pro series contributing only about nine days of sales data. Therefore, the current quarter's performance does not fully reflect market reception following the new model launches. Apple's first foldable phone, the iPhone Duo, officially went on sale on October 23 and will also not be included in this quarter's revenue, with its sales performance set to be more reflected in the upcoming holiday shopping season results.
Besides the iPhone, the Services business remains a crucial pillar sustaining Apple's profitability. The market expects Services revenue for this quarter to be around $31.6 billion, representing a year-over-year increase of nearly 10%, though the growth rate may fall to its lowest level in over three years.
Given that the Services business typically enjoys higher gross margins, its growth performance will directly influence market assessments of Apple's overall earnings quality. Meanwhile, attention should also be paid to the sales performance of the Mac, iPad, and Wearables segments following new product releases, as well as whether product price hikes have impacted consumer demand.
Gross Margin Becomes Top Earnings Focus as Memory Prices Rise
Compared to whether revenue meets expectations, a risk more worthy of attention in this earnings report may come from the cost side. The ongoing construction of AI data centers continues to push up global demand for memory chips, tightening DRAM and NAND supply, with price hikes passing through to the consumer electronics supply chain. For Apple, even if iPhone sales maintain growth, rising costs for memory chips and other key components could still erode profit margins in its hardware business.
In the previous quarter, Apple's consolidated gross margin reached 50.1%, but about two percentage points of that stemmed from tariff refunds, leaving it at roughly 48.1% excluding this factor. The company's gross margin guidance for the fourth quarter is 47% to 48%, which still includes about one percentage point of tariff refund benefit, implying that the core gross margin may be only 46% to 47%.
Apple previously stated that more than the entire decline from the previous quarter's adjusted 48.1% to the midpoint of this quarter's guidance of about 46.5% can be explained by rising memory costs. Lower non-memory component costs, inventory buffers, and a more favorable product mix can only offset part of the pressure.
Changes in memory prices typically do not fully reflect in the income statement immediately. As lower-cost inventory is gradually depleted and newly procured higher-priced DRAM and NAND begin entering cost of goods sold, gross margin pressure may extend into the next fiscal quarter. Even if Apple passes on costs by raising product selling prices, it remains to be seen whether sales volume will be affected as a result.
New CEO Debut: AI Strategy and Holiday Guidance Matter More
This earnings report carries special significance as it marks the first time Ternus will host Apple's earnings call after succeeding Tim Cook as CEO. Having long led Apple's hardware engineering and product development, Ternus's comments on the product cycles of the iPhone, Mac, and iPad will be closely watched, as will any new signals he might give regarding corporate strategy and the pace of product innovation.
In recent months, Apple has rolled out new products including foldable smartphones, smart home hubs, and touchscreen MacBooks, accelerating its pace of product updates. Whether Ternus can continue to drive hardware innovation while maintaining Apple's consistent product ecosystem and profitability will serve as a key basis for investors to evaluate his management style.
The artificial intelligence strategy is equally impossible to ignore. Compared with companies like Microsoft (MSFT), Google (GOOGL), Amazon (AMZN), and Meta (META), Apple has not invested heavily in building AI data centers, focusing instead on integrating AI features into its existing device and software ecosystem, and supplementing its capabilities through partnerships with external models. This relatively disciplined spending approach provided Apple with a measure of valuation protection when tech stocks recently came under general pressure from AI capital expenditure demands.
However, investors still need to see how AI will create tangible value for Apple. The market is likely to focus its questions on the progress of Siri AI upgrades, user adoption rates, and whether Apple can generate revenue by distributing third-party AI services through the App Store.
Visible Alpha estimates that Apple's fiscal first-quarter 2027 revenue will be approximately $153 billion, with earnings per share of around $2.93. This quarter will fully reflect the sales performance of the iPhone 18 Pro and iPhone Duo, serving as a more effective window to assess whether price hikes can offset rising costs.
If Apple projects revenue growth in only the low-to-mid single digits while gross margin continues to decline, the market may revise down future earnings forecasts. Conversely, if holiday season demand remains robust, services revenue grows steadily, and gross margin refrains from further deterioration, the cost pressures of this quarter may be viewed as a temporary phenomenon.
Apple Price Target Reaches as High as $400
Apple's stock price has risen about 30% over the past year and gained nearly 27% year-to-date. As other Big Tech companies face scrutiny over AI capital expenditures, Apple's relatively restrained investment approach has made its stock performance more resilient. However, the strong rally also implies that the market has already priced in high growth expectations.
According to TipRanks data, among 27 analysts covering Apple over the past three months, 13 rate it a "Buy", 10 recommend a "Hold", and 4 assign a "Sell" rating. The 12-month average price target is $337.77, with a high of $400 and a low of $245. Based on the pre-earnings price of $344.63, the average price target actually represents downside of about 2%.
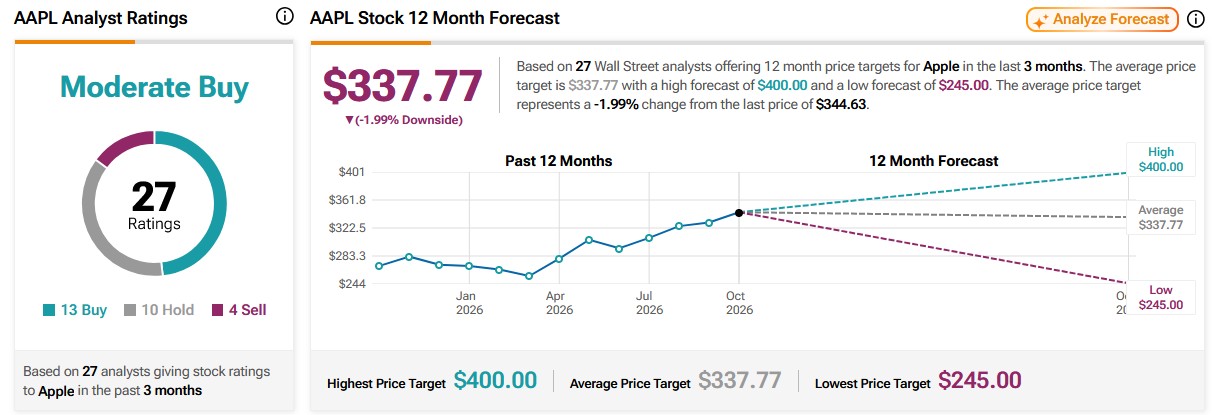
Source: TipRanks
These figures reflect that while Wall Street remains confident in Apple's long-term competitiveness, opinions on its current valuation have clearly diverged. Bullish views hold that iPhone premiumization, services revenue, and a new product cycle can support the $400 price target, while cautious views argue that a valuation approaching 40 times earnings leaves little room to tolerate margin declines or holiday season guidance that misses expectations.
Find out more