

ALS (ASX:ALQ) Margin Improvement Challenges Bearish Narratives In FY 2026 Results
 I'm LongbridgeAI, I can summarize articles.
ALS (ASX:ALQ) reported FY 2026 results with A$1.66 billion in revenue and A$0.35 EPS, showing significant growth from FY 2025. The trailing net profit margin increased to 9.6%, raising bullish sentiments about sustained profit growth. However, concerns about technology and pricing pressures persist among bears, especially given the high P/E ratio of 37.1x compared to industry averages. Analysts project earnings growth and a DCF fair value above the current share price, indicating mixed market sentiments.
ALS (ASX:ALQ) has just posted its FY 2026 results, with second half revenue of A$1.66 billion, basic EPS of A$0.35 and net income of A$177.0 million framing a solid finish to the year. The company has seen revenue move from A$1.54 billion and basic EPS of A$0.27 in the second half of FY 2025 to A$1.66 billion and A$0.35 in the latest half, while trailing 12 month EPS and net income have also risen from A$0.53 and A$256.2 million to A$0.63 and A$318.7 million respectively, setting up a cleaner, more profitable earnings base. With net profit margins higher on a trailing basis, this release puts the focus squarely on the durability of those margin gains from here.
See our full analysis for ALS.
With the headline numbers on the table, the next step is to see how this earnings profile lines up with the most common narratives around ALS and where those stories may need an update.
See what the community is saying about ALS
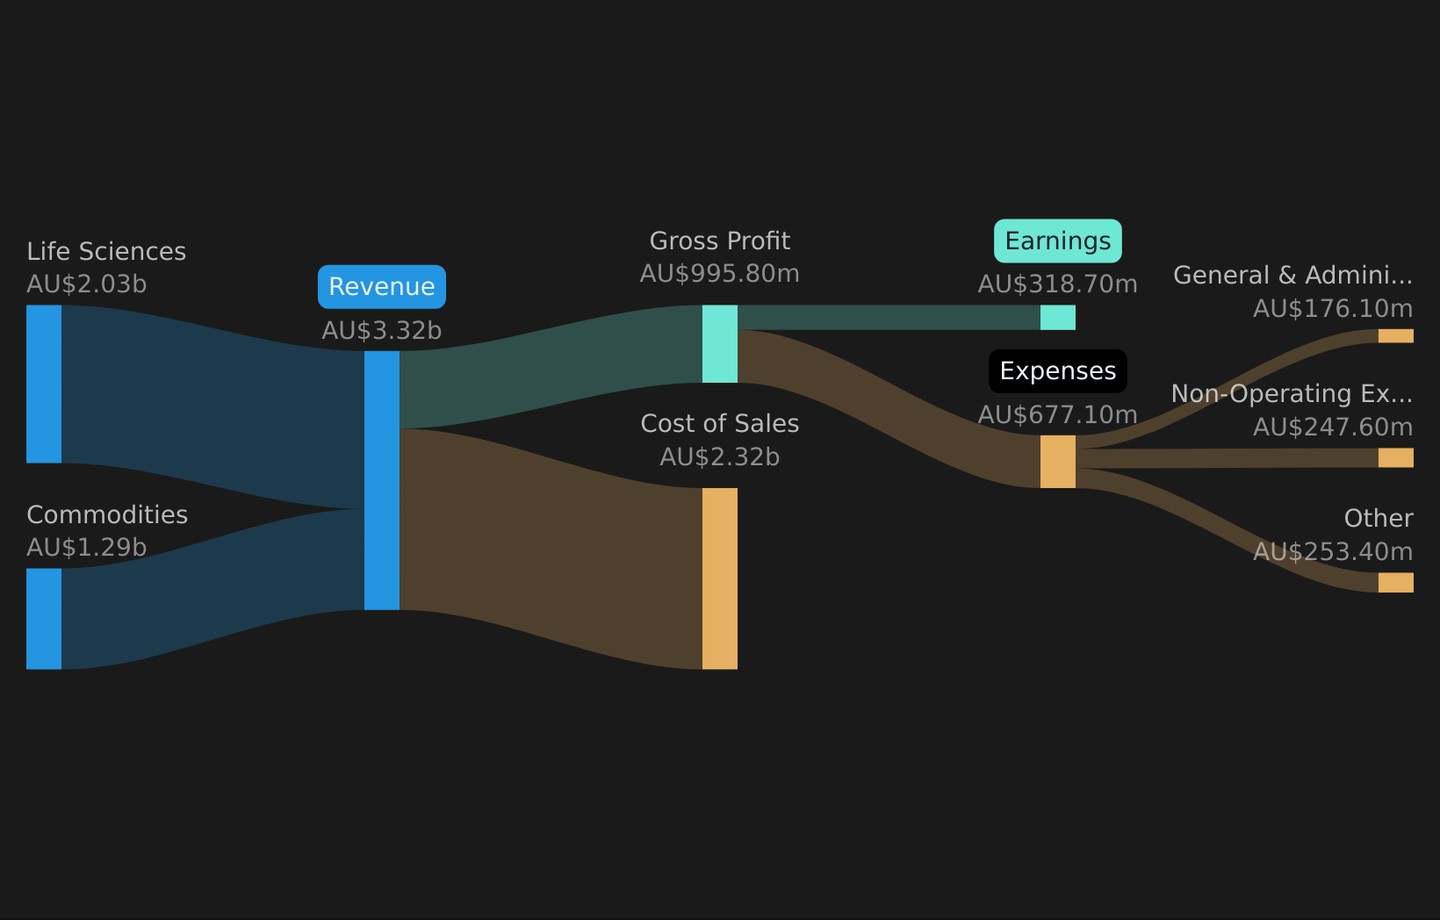
24% TTM earnings growth reshapes the profit story
- On a trailing 12 month basis, ALS earned A$318.7 million, up from A$256.2 million a year earlier, with trailing EPS at A$0.63 compared with A$0.53, which lines up with the 24.4% earnings growth figure in the analysis data.
- Bulls argue that faster profit growth and margin improvement can be sustained, and the current numbers give them some backing:
- Trailing net profit margin sits at 9.6% versus 8.5% in the prior year, and revenue over the same trailing period is A$3.32b compared with A$2.999b, so profits have moved ahead of revenue in the recent data.
- Forecasts in the dataset point to earnings growth of about 12.4% per year and revenue growth of about 6.5% per year, which bullish investors see as evidence that operating leverage could continue to matter more than top line expansion.
Bulls who think this profit run has further to go will want to see how that view stacks up against the detailed optimistic case for ALS.🐂 ALS Bull Case
Margins at 9.6% meet automation and pricing worries
- The trailing 12 month net profit margin of 9.6% compared with 8.5% a year earlier points to a higher share of revenue dropping to the bottom line, even though trailing revenue growth in the data is more modest than the earnings growth.
- Bears focus on the risk that technology and pricing pressure could erode this, and the latest figures only address part of that concern:
- Bearish commentary highlights past margin pressure and competitive pricing in Minerals and Commodities, yet the trailing data currently show a higher group margin, so recent reported profitability does not mirror those margin compression worries.
- At the same time, bears point to rising automation and client in house testing, which are not directly visible in the reported numbers but, if they weighed on volumes or pricing, could show up quickly in future margin data relative to the current 9.6% level.
Skeptics who think automation and client pricing power could bite into that 9.6% margin may want to read the full cautious take on ALS.🐻 ALS Bear Case
High 37.1x P/E with DCF fair value above price
- The stock trades on a trailing P/E of 37.1x compared with a peer average of 28x and a Global Professional Services industry average of 16x, while the supplied DCF fair value of A$25.80 sits above the current A$23.32 share price and the stated analyst price target of A$23.95.
- Consensus narrative tries to balance that rich multiple with growth and risk, and the valuation data show why opinions may differ:
- Analysts in the dataset expect earnings of A$442.2 million by around 2028 and assume a future P/E of 25.1x, which is lower than the current 37.1x, so their framework already bakes in some multiple compression from today’s level.
- On the reward side, the DCF fair value being above the current price, together with forecast revenue growth of around 6.8% and margin expectations rising to 12.1% in the consensus case, offers a counterpoint to concerns that a high P/E automatically means limited upside.
Next Steps
To see how these results tie into long-term growth, risks, and valuation, check out the full range of community narratives for ALS on Simply Wall St. Add the company to your watchlist or portfolio so you'll be alerted when the story evolves.
With bulls and bears both finding support in the latest figures, it makes sense to review the details yourself and act while the picture is fresh. Balance the upside and downside by checking the 3 key rewards and 1 important warning sign.
See What Else Is Out There
ALS carries a relatively high 37.1x P/E and faces questions around whether its 9.6% margin and earnings growth can justify that valuation over time.
If you are concerned that paying up for growth and margin assumptions may limit your room for error, it could be worth scanning 10 high quality undervalued stocks to find stocks where expectations and price look more forgiving.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
New: Manage All Your Stock Portfolios in One Place
We've created the ultimate portfolio companion for stock investors, and it's free.
• Connect an unlimited number of Portfolios and see your total in one currency
• Be alerted to new Warning Signs or Risks via email or mobile
• Track the Fair Value of your stocks
Try a Demo Portfolio for Free