
US September CPI Preview: Inflation May Heat Up, How Will US Stocks, Dollar and Gold React?
 I'm LongbridgeAI, I can summarize articles.
The US will release September CPI data on October 14, ahead of the Fed's policy meeting. Markets expect headline CPI to rise to 3.7% YoY due to energy prices, while core CPI may slow to 0.2% MoM. This divergence suggests limited immediate pressure for rate hikes, keeping October hike odds low at 19%. The report's impact on stocks, the dollar, and gold hinges on whether core inflation remains contained or accelerates, influencing Fed expectations and asset valuations.
TradingKey - The U.S. will release its September CPI data on Wednesday (October 14) Eastern Time, which will be one of the most important inflation reports ahead of the Federal Reserve's October 27-28 policy meeting. Currently, the market widely expects that, driven by rising energy prices, U.S. headline inflation may continue to pick up, while core inflation growth may slow.
September CPI May Rebound Sharply, Fed October Rate Hike Odds Remain Low
Based on market expectations, the consensus forecast shows the September CPI rising 3.7% year-over-year, higher than August's 3.4%, while core CPI year-over-year is expected to edge up slightly to 2.5% from 2.4%. On a month-over-month basis, the market expects headline CPI to rise by about 0.6%, significantly higher than August's 0.4%, whereas core CPI is expected to increase by 0.2%, down from 0.3% in August.
For investors, the most noteworthy aspect of this CPI report is the potential sharp divergence between headline and core inflation. International energy prices remained elevated in September, with Middle East tensions driving up gasoline and other energy costs, which could serve as the primary driver behind the acceleration in headline CPI. If core CPI remains contained at around 0.2% month-over-month, it would suggest that the energy shock has not yet visibly spread to broader goods and services prices, keeping market concerns over further rapid Fed rate hikes relatively limited.
It should be noted that U.S. inflation risks have not yet abated. The latest consumer survey from the Federal Reserve Bank of New York showed that one-year inflation expectations among U.S. consumers rose to 3.9% in September from 3.6%, reaching the highest level since May 2023. Consumers also expect prices for various categories—including gasoline, food, rent, and medical care—to continue rising. This implies that even if core CPI cools temporarily, the Fed still needs to monitor whether energy prices and inflation expectations further pass through to services and wage pricing.
Meanwhile, recent labor market data has provided the Fed with some room to wait and see. U.S. nonfarm payrolls added just 29,000 jobs in September, significantly below market expectations of 90,000. The unemployment rate rose from 4.1% to 4.2%, while average hourly earnings increased by only 0.1% month-over-month. As the labor market cooled, expectations for back-to-back rate hikes by the Fed in October diminished noticeably.
According to the CME FedWatch Tool, the market currently puts the probability of a Fed rate hike in October at around 19%, though bets on a December rate hike remain close to 85%. Therefore, if the core CPI meets expectations at 0.2%, the Fed is more likely to pause in October and continue monitoring subsequent PCE and employment data. However, if core CPI reaches 0.3% or even 0.4%, accompanied by a re-acceleration in services inflation, expectations for rate hikes in either October or December could heat up significantly.
How Will September CPI Impact US Stocks, the Dollar and Gold?
For US equities, core CPI may be more important than headline CPI. If headline CPI rises to 3.7% due to higher energy prices, but core CPI increases by only 0.2% month-on-month, the market may view inflationary pressure as mainly stemming from a short-term energy shock. This would reinforce expectations that the Federal Reserve will pause rate hikes in October, which is relatively favorable for high-valuation sectors such as the Nasdaq, AI, and semiconductors. Conversely, if core CPI reaches 0.3% or even higher, the market may again raise expectations for Fed rate hikes. Currently, the 10-year US Treasury yield remains around 5.2%, and high interest rates have become a key factor capping valuation expansion for US stocks. Therefore, a higher-than-expected CPI reading could put pressure on tech growth stocks.
As for the US dollar, if the September CPI, particularly core CPI, beats expectations, the dollar may continue to draw support from interest rate expectations. The US Dollar Index recently climbed to near an 18-month high, and although it pulled back to around 102.39 during the Asian trading session on October 13, US interest rates remain elevated. Stronger-than-expected inflation data could prompt the market to raise the probability of an October or December rate hike and push US Treasury yields higher, thereby supporting the dollar. Conversely, if core CPI rises by only 0.2% or even less, the dollar could undergo a temporary pullback, as the market would further solidify expectations for the Fed to stay on hold in October.
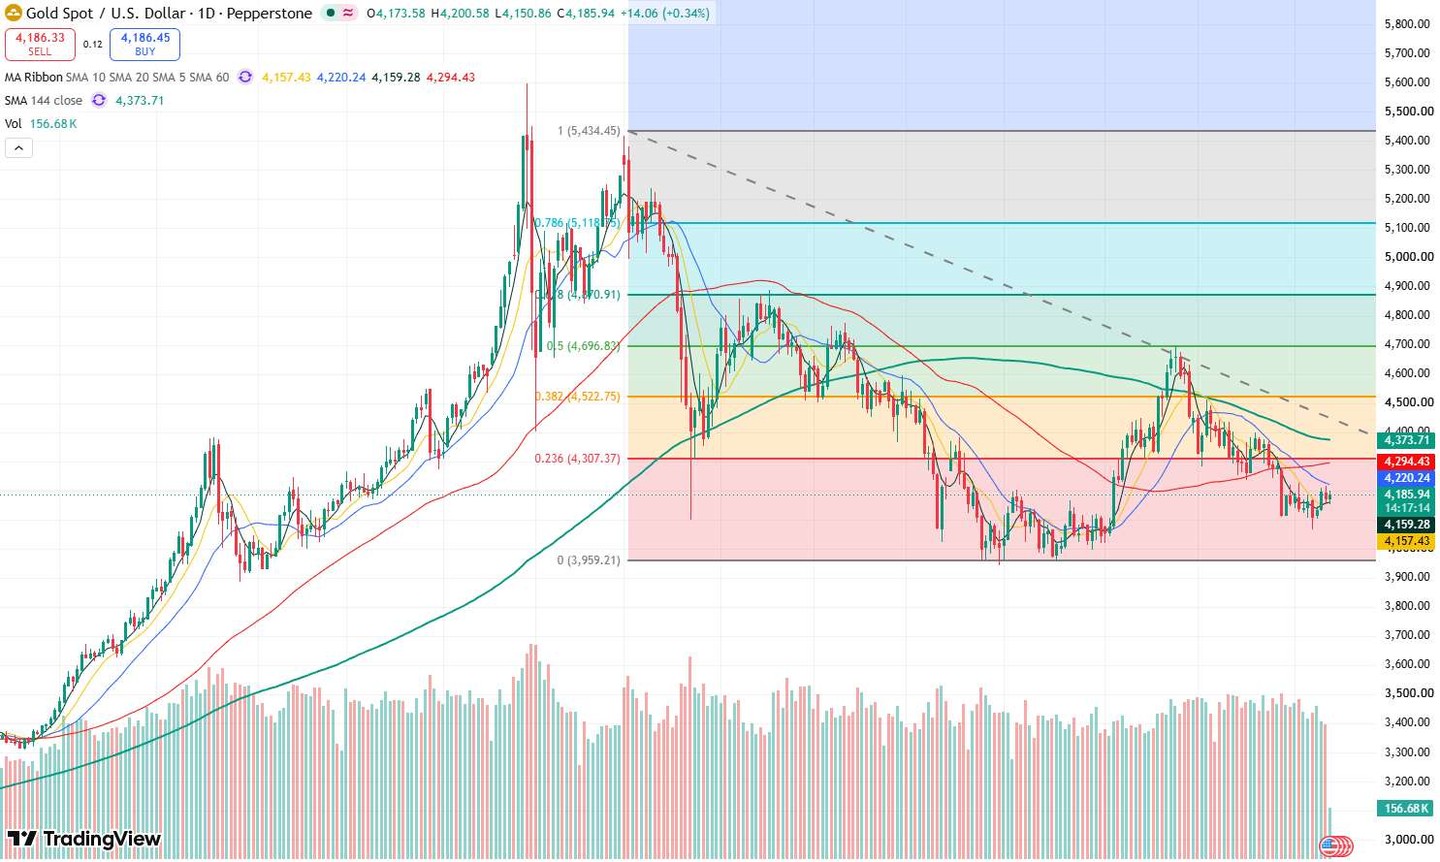
Gold price daily chart, Source: TradingView
As for gold (XAUUSD), spot gold is currently trading near $4,180, with recent high interest rates and a strong US dollar capping the upside for gold prices. If core CPI beats expectations, rising Fed rate hike expectations could push the dollar and US Treasury yields up again, weighing on gold; if core CPI is modest or even below expectations, the probability of an October rate hike will drop further, and a retreat in US Treasury yields and the dollar could drive gold to bounce back. The market is currently pricing in a low probability of an October rate hike, so what gold really needs to watch out for is a significant upside surprise in core inflation, rather than just energy driving headline CPI up to 3.7%.