

Is Apple a Buy on the Dip, or Are Mounting Headwinds Too Strong?
 I'm LongbridgeAI. Here is the key information I extracted
Apple (AAPL +5.31%) posted another strong quarter of iPhone sales when it reported its fiscal fourth-quarter results after the bell on Nov. 2. However, the stock traded lower on worries of gross margin compression due to higher memory prices and decelerating service revenue growth.
The stock was up nearly 25% on the year before the report.
Let's take a closer look at the company's fiscal Q4 results and prospects to see why I wouldn't be chasing this small pullback.
Image source: The Motley Fool
Strong iPhone sales
Apple's fiscal Q4 tends to be a seasonally weaker quarter for the company, as it comes right before the release of its newer model phone and before the holiday season. Its new iPhone 18 Pro was only available eight days in the quarter, while its new iPhone Duo didn't hit shelves until after the quarter was over. However, the company did benefit from the $100 price increase it implemented in June.
iPhone sales soared 17% to $57.58 billion, which was a September quarter record and ahead of the $56.54 billion analyst consensus, as compiled by LSEG. It saw strong double-digit iPhone sales in both the U.S. and Greater China, and set a record for upgraders worldwide. Meanwhile, it said the response to both the iPhone 18 and Duo has been strong.
AAPL - Apple
NASDAQ · As of 4:00 PM ET 11/04/26
 Moneyball Superscore87/100
Key data points
Other product sales were mixed
Mac revenue was also strong, with sales climbing 24% year over year to $10.79 billion and topping analyst expectations for sales of $9.61 billion. The company credited strong growth in emerging markets. It set a September quarter record for new Mac customers.
Sales of Apple's other products were generally weak. Sales of iPads fell 10% to 6.23 billion, while wearable revenue sank by 8% to $8.3 billion. However, the company did recently launch new products in these categories, including a new iPad mini with an OLED display and Apple HomeView, which is meant to act as an entertainment and personal assistant hub.
Total product segment sales climbed by 12.5% to $82.9 billion. China was once again solid, with revenue jumping 21% to $17.54 billion.
Apple services revenue growth slows again
Apple's services segment -- which consists of its App Store, iCloud storage, Google Search revenue sharing, Apple Pay, Apple TV, and more -- saw revenue rise 10% to $31.57 billion. That was a continued deceleration from the 12% growth it saw in fiscal Q3 and 16% growth it saw in fiscal Q2. It was the segment's slowest quarterly growth since 2022.
Product gross margin came in at 37.2%, and excluding tariff refunds in both quarters was down 100 basis points sequentially. Like others in the space, Apple is currently dealing with surging memory prices. Service margin, meanwhile, rose by 40 basis points sequentially to 76%. Overall gross margin was 47.9%, which was above analyst expectations of 47.5%.
Overall, Apple's revenue rose by 12% to $114.48 billion, while its earnings per share (EPS) jumped 14% to $2.10. Excluding an $0.05 tariff rebate boost, adjusted EPS would have been $2.05. That topped the analyst consensus estimates for EPS of $1.99 on sales of $113.39 billion.
Tempered guidance
For fiscal Q1, Apple projected its revenue to grow by 7% to 10% year over year, impacted by currency headwinds and supply constraints. Service revenue is expected to increase between 8% to 9%, hurt by third-party licensing and currency headwinds. The company guided for gross margin to be between 45% and 46%.
Analysts were looking for revenue growth of 6%, but gross margins of 46.3%.
Time to stay on the sidelines
Apple has one of the best compounding business models in the world, but it is facing headwinds from memory prices, supply constraints, and currency headwinds. The company so far has been bucking the overall weakness in the smartphone and PC markets, but high memory prices are pressuring its gross margins. Another worry is the continued deceleration of the company's high-margin services business, which had been a consistent mid-teen revenue grower in the past.
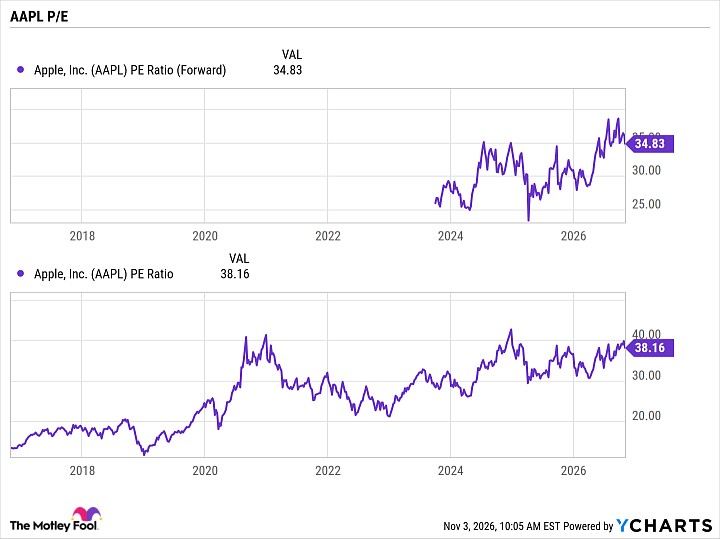
Taken altogether, I would not be buying Apple on this minor dip. The stock continues to trade at a premium valuation despite its headwinds, with a forward price-to-earnings (P/E) ratio of nearly 35 times based on analysts' estimates for fiscal 2027 (which ends in September 2027).
AAPL PE Ratio (Forward) data by YCharts
The stock has benefited from huge multiple expansion over the past decade, but it's hard to see that continuing. As such, while Apple is a great company, I wouldn't be buying the stock right now.