

Oracle’s AI Spending Is Still Huge, But the Payoff Is Starting to Show in Earnings
 I'm LongbridgeAI, I can summarize articles.
Oracle reported strong Q1 FY2027 results, with revenue up nearly 30% to $19.35 billion and record $23 billion operating cash flow, driven by a 62% surge in Cloud revenue. Despite negative free cash flow due to data center demand, the backlog grew 46% to $664 billion, signaling AI monetization success. Analysts maintain a Moderate Buy consensus, citing an inflection point for accelerated earnings growth and stock recovery.
Highlights from the Q1 fiscal year 2027 (FY2027) release reveal the impacts of spending, capital raises, and dilution, overshadowed by improved earnings leverage and cash flow. The likely outcome is that monetization of its AI network will accelerate in the coming quarters, while capital expenditure (CapEx) could begin to taper off over time.
The result could be rapid profitability improvement, high-level growth, accelerated earnings, and eventually debt reduction—a quartet of bullish stock price catalysts.
Migration to Oracle’s Cloud Accelerates in FQ1
Oracle’s results were robust across metrics, driving sequential and year-over-year revenue growth acceleration to 30%. The $19.35 billion in revenue outperformed MarketBeat’s consensus by more than 100 basis points (bps), underpinned by strength in the Cloud and 850 MW in new GPU capacity. Total Cloud grew 62%, with infrastructure up 121% and software-as-a-service (SaaS) up 10%; segmentally, Services grew 5%, and Hardware grew 15%. Legacy Software, now less than 30% of the business, contracted by 3%.
The real news is in the margins and cash flow. After two years of accelerating spend, negative free cash flow, increasing debt, and shareholder dilution, the company is showing traction with its strategy. Backlog conversion contributed to significant improvement in operating and net income, both GAAP and adjusted, with both outpacing topline growth. Key takeaways include a record $23 billion in operating cash flow, 55% growth in GAAP earnings per share and 30% growth in adjusted earnings, and a sizable earnings beat versus consensus.
The only downside is that free cash flow remains negative because of intense data center demand. Oracle reported negative free cash flow of $5 billion in Q1 FY2027. The offset is that the backlog continues to swell, growing by about 46% year-over-year (YOY) in the first quarter to $664 billion. More importantly, the company says the new orders don’t translate into increased capital needs, which means the revenue and earnings outlook has improved without requiring an increase in its existing capital-raising plan. Oracle said more than $30 billion in new AI cloud contracts booked during Q1 had no incremental impact on its capital-raising plans. Guidance reflects the improvement, with management citing a strong Q2 and raising full-year targets, forecasting continued acceleration.
Analysts Highlight Oracle’s AI-Driven Inflection Point: Accelerating Growth Ahead
The analysts' response is mixed, including at least one price target reduction, but it is an outlier, given that the bulk of revisions are bullish. Chatter focused on the massive beats and guidance, which indicate AI monetization is not only on track but progressing ahead of schedule. Barclays reiterated a Buy rating, expecting accelerating earnings growth in upcoming quarters.
As it stands, the 40 analysts MarketBeat tracks provide a high conviction in the Moderate Buy rating. There is a 75% Buy-side bias in the data, and the consensus price target, which was validated by post-release responses, forecasts nearly 65% of upside from early September trading levels. In this scenario, analysts' sentiment is firming and likely to continue strengthening as the year progresses.
Oracle’s Stock Price Inflection Is Here
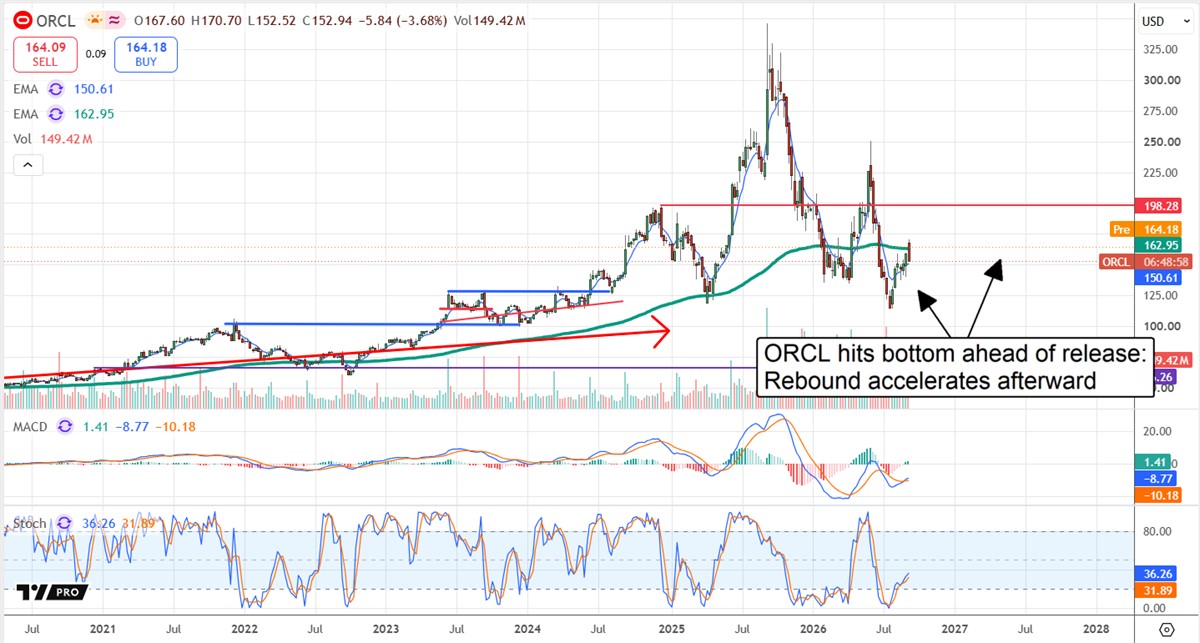
Stock price action is favorable. The late 2025 and early 2026 price pullback was overdone, disconnected from the opportunity, and a reversal is now underway. The bottom is near $130, now the critical support target, and indicators such as the stochastic and MACD align with Buy signals across multiple time frames. The hurdle is the long-term 150-week EMA near $135; it marks an inflection point for traders and reflects the stance of institutional and long-term investors. A move above that level would signal a shift in sentiment, clearing the way for a fuller price recovery.
Institutions will make the difference because Oracle is a tightly held stock. The group owns more than 40%, a seemingly small number until you consider that insiders also own more than 40%. The risk is that selling, which dominated their activity in calendar Q2, will pick up again as price action increases, but that is less likely if profitability continues improving. Early Q3 activity reflects a surge in buying, which is the more likely outcome. With this in play, institutional buying could help limit downside if price weakness returns.
Oracle’s biggest risks are debt and dilution, but those are becoming easier to absorb as growth accelerates. The surging backlog and monetization reduce the risk, leaving investors to wonder when share buybacks will resume. While buybacks are unlikely in 2027, 2028 is a possible target, as most of the planned capacity will be online or nearly there. The dividend helps make up the difference, yielding about 1.3% at current prices around $150, and the distribution is expected to increase over time. Oracle doesn’t raise the dividend annually, but has a record of increasing it every few years.
Should You Invest $1,000 in Oracle Right Now?
Before you consider Oracle, you'll want to hear this.
MarketBeat keeps track of Wall Street's top-rated and best performing research analysts and the stocks they recommend to their clients on a daily basis. MarketBeat has identified the five stocks that top analysts are quietly whispering to their clients to buy now before the broader market catches on... and Oracle wasn't on the list.
While Oracle currently has a Moderate Buy rating among analysts, top-rated analysts believe these five stocks are better buys.
View The Five Stocks Here
Continue following MarketBeat
Add MarketBeat as your preferred source on Google to see our latest stories in your feed.
Add As Preferred Source