

Opinion: The Most Important Number in Taiwan Semiconductor's Earnings Report Was 68%
 I'm LongbridgeAI, I can summarize articles.
TSMC's Q3 revenue rose 41.2% to $46.72 billion, with net income up 68.7%. High-performance computing (HPC) accounted for 68% of revenue, driven by AI demand and advanced manufacturing processes like 2nm and 3nm. TSMC expects Q4 revenue between $52.3B-$54.3B and full-year growth of ~44%, highlighting HPC as a key growth driver.
The third-quarter results for Taiwan Semiconductor Manufacturing (TSM +2.19%) are in, and investors have plenty of reasons to be excited. TSMC reported Q3 revenue of $46.72 billion, a 41.2% increase from a year ago. Net income jumped 68.7%, while the company's gross profit margin reached 66.4%.
Those are impressive numbers by any measure, particularly for a company of TSMC's size. But there's another figure buried in the company's earnings presentation that I think is even more important. High-performance computing (HPC) accounted for a whopping 68% of TSMC's quarterly revenue, with sales in that business increasing 22% from Q2.
That tells us quite a bit about where TSMC's growth is coming from -- and why its artificial intelligence (AI) business remains such an important opportunity for investors.
Image source: TSMC.
AI is becoming an even bigger part of TSMC's business
TSMC is the biggest chip foundry in the world, manufacturing chips for companies such as Nvidia, Advanced Micro Devices, and Apple. TSMC has an overwhelming 72.5% of the global market share and, in 2025, produced more than 12,600 products using 305 separate process technologies.
That business model gives TSMC an interesting advantage. It doesn't necessarily have to predict which chip designer will come out on top because it can manufacture chips for competing companies. And increasingly, those chips are being used for high-performance computing.
HPC includes processors used in AI accelerators, data centers, and other demanding computing applications. It's a broader category than artificial intelligence alone, but AI is an important driver of demand for the advanced chips that TSMC manufactures.
In Q3, HPC generated more than two-thirds of the company's revenue compared with just 21% from smartphones. And while TSMC's overall revenue increased 16.2% sequentially, HPC revenue grew even faster at 22%.
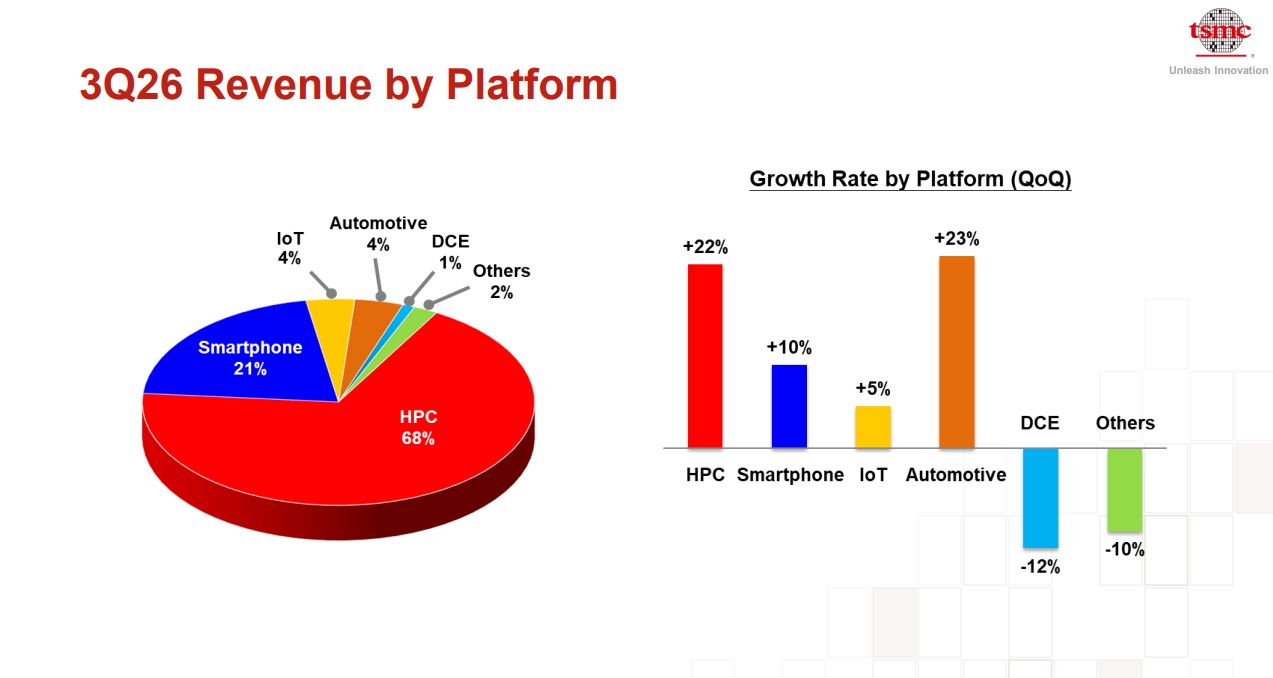
Image source: TSMC.
The growth also comes as major technology companies continue investing in the computing infrastructure needed to train and operate increasingly powerful AI models. Those investments create demand for advanced processors, and TSMC manufactures many of the chips used in those systems.
Advanced manufacturing strengthens TSMC's advantage
The growth in high-performance computing is particularly encouraging given the technology behind those chips. TSMC said that its advanced manufacturing processes, which include 7-nanometer technology and smaller, accounted for 79% of Q3 wafer revenue. Its newest 2-nanometer technology already represented 8% of wafer revenue, while 3-nanometer chips accounted for another 33%.
Here's why that's important: Smaller manufacturing processes mean that chips can be more powerful and efficient, which are important qualities for AI data centers, where computing performance and electricity consumption can have a substantial effect on operating costs.
That's one reason I've remained bullish on TSMC. Its manufacturing capabilities give the company a competitive advantage that's difficult to duplicate, while demand for advanced computing continues to expand. And the latest results suggest that customers are putting those capabilities to work.
TSM - Taiwan Semiconductor Manufacturing
NYSE · As of 10:52 AM ET 10/19/26
 Moneyball Superscore98/100
Key data points
Is TSMC stock still worth buying?
TSMC expects Q4 revenue between $52.3 billion and $54.3 billion, indicating that management anticipates another sequential increase in sales. For the full year, the company now expects revenue growth of approximately 44% in U.S. dollars.
While the current pace of AI infrastructure spending won't continue indefinitely, guidance from major chipmakers indicates an ongoing appetite for more advanced AI processors -- and that should keep profits rolling in for TSMC.
With HPC now accounting for 68% of revenue and growing faster than the rest of the business, TSMC is demonstrating just how valuable that position has become. That's the number I'd pay the most attention to in this earnings report.