

SK Hynix Subsidiary Solidigm Eyes US IPO That Could Set Semiconductor Record: What Investors Need to Know
 I'm LongbridgeAI, I can summarize articles.
SK Hynix's US subsidiary Solidigm is considering a US IPO as early as 2027, potentially raising $15 billion with a valuation up to $150 billion. This could set a record for semiconductor IPO fundraising, surpassing Cerebras. Preparations are in early stages, with underwriter selection underway. Solidigm, formed from SK Hynix's acquisition of Intel's NAND and SSD business, benefits from AI-driven demand for enterprise storage. However, risks include unverified standalone financials and cyclical market pressures.
TradingKey - On September 25 ET, Reuters reported, citing three people familiar with the matter, that SK Hynix's (SKHY) US memory subsidiary Solidigm is considering a US IPO as early as 2027, with a potential valuation of up to approximately $150 billion and fundraising that could reach $15 billion.
Solidigm recently held IPO underwriting bake-offs with multiple investment banks to evaluate potential underwriters and listing plans. Preparations remain in early stages, with the listing timing, exchange, offering size, and final valuation yet to be determined, and SK Hynix has not announced formal plans.
If fundraising reaches $15 billion, Solidigm could set a new record for US semiconductor IPO fundraising, surpassing Cerebras's (CBRS) 2026 IPO fundraising size of approximately $5.55 billion.
[Top 3 US Semiconductor IPO Offering Sizes]
Rank | Company | Listing Date | Base Offering Size | IPO Valuation |
1 | Cerebras (CBRS) | May 2026 | Approx. $5.55 billion | Approx. $56.4 billion |
2 | Arm (ARM) | September 2023 | Approx. $4.87 billion | Approx. $54 billion |
3 | GlobalFoundries (GFS) | October 2021 | Approx. $2.59 billion | Approx. $26 billion |
Including the over-allotment option, Cerebras's final offering size was approximately $6.4 billion, with a fully diluted valuation at listing of around $56.4 billion; Solidigm's discussed upper valuation limit is nearly 2.7 times that. As Solidigm has not yet filed a prospectus, the final fundraising size and valuation remain subject to adjustment.
What Kind of Company Is Solidigm?
Solidigm was founded in 2021 as a U.S. storage company formed after SK Hynix acquired Intel's (INTC) NAND and SSD business.
The total contract value of the transaction was $9 billion. In the first phase, SK Hynix paid $7 billion to acquire Intel's SSD business and Dalian NAND facility; the second-phase contract consideration was $2 billion to acquire the remaining NAND intellectual property, R&D personnel, and related assets. The transaction was completed on March 27, 2025, with Intel receiving approximately $1.9 billion after adjustments.
Solidigm primarily develops and sells data center, enterprise, and client SSDs. With growing demand for AI storage, its high-capacity QLC enterprise SSDs have become a key market focus.
How Solidigm Benefits from AI Storage Demand?
AI inference has expanded data access demand for model files, vector databases, and KV caches, driving cloud service providers to procure high-capacity enterprise SSDs. High-capacity products can reduce the number of drives and rack space required per unit of storage scale, while lowering power and cooling costs per petabyte of storage capacity.
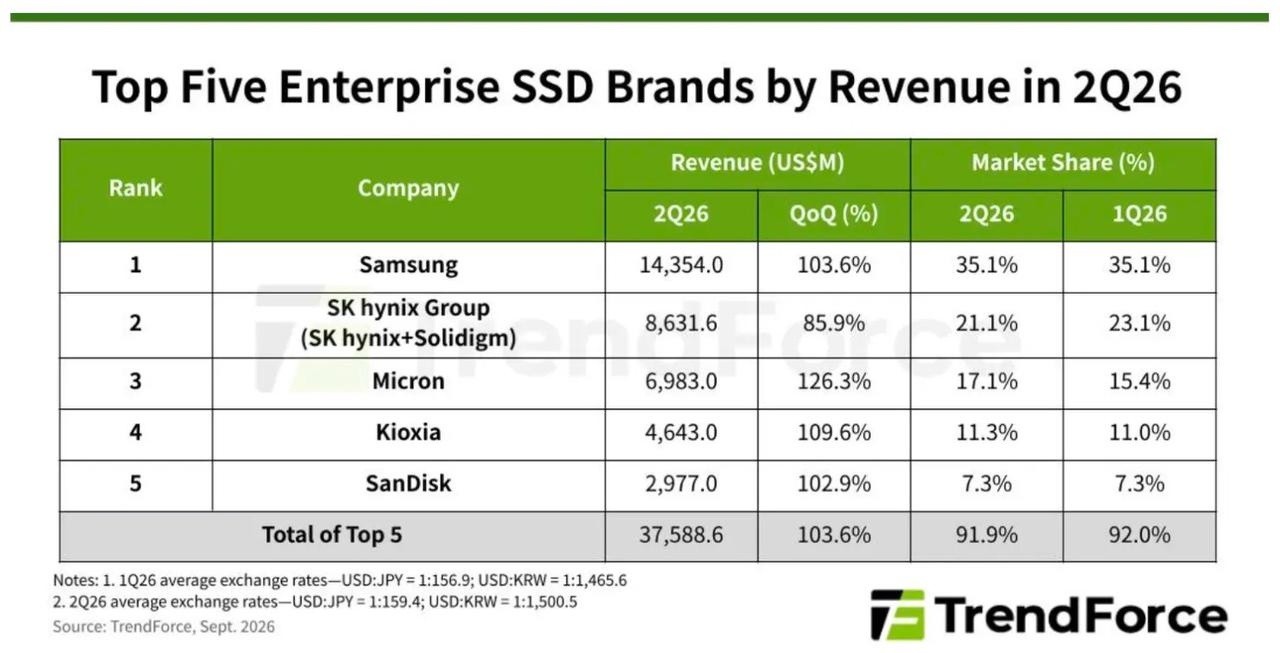
According to data from TrendForce, total revenue for the world's top five enterprise SSD vendors reached approximately $37.59 billion in the second quarter of 2026. On a consolidated basis for SK Hynix and Solidigm, the group's revenue exceeded $8.63 billion, ranking second.
Growth in shipments of Solidigm's ultra-high-capacity QLC enterprise SSDs was one of the factors driving the group's revenue increase.
[Source: TrendForce]
In addition, Solidigm signed a multi-year agreement with CoreWeave (CRWV) to grant priority access to enterprise SSD capacity for its AI cloud platform. The two parties did not disclose the purchase amount or product volume.
Growing demand for enterprise SSDs gives Solidigm an opportunity to be valued separately from SK Hynix's comprehensive storage business. Analysts believe an independent listing would help SK Hynix recoup its M&A investment, expand future financing capabilities, and shift capital allocation toward higher-margin businesses.
Solidigm's Equity Structure and Financing History
SK Hynix currently controls Solidigm, with no other institutional shareholders disclosed in public information. Solidigm's core assets originate from SK Hynix's acquisition of Intel's NAND and SSD businesses.
Date | Key Developments | Amount and Status |
October 2020 | SK Hynix agreed to acquire Intel's NAND and SSD businesses | Total transaction value of $9 billion |
December 2021 | First-stage transaction completed, Solidigm established | $7 billion paid |
March 2025 | Second-stage transaction completed | Contract amount of $2 billion |
August 2026 | Reportedly considering pre-IPO financing | Potential financing size of 5 trillion to 10 trillion KRW |
September 2026 | Reportedly launched IPO underwriter selection | Potential fundraising amount of up to approximately $15 billion |
According to previous reports by South Korean media, Solidigm had approached global asset management institutions and sovereign wealth funds to assess pre-IPO funding needs, but the investor list and subscription amounts have not been disclosed. Morgan Stanley (MS) and Goldman Sachs (GS) are reportedly involved in the financing and IPO preparations, with specific roles yet to be determined.
What Risks Does the Solidigm IPO Face?
Whether the high valuation can be supported by financial data is the primary issue facing Solidigm's IPO. The company has not yet disclosed complete standalone financial statements, with revenue, profit margins, operating cash flow, and customer concentration remaining to be disclosed in the prospectus.
The NAND market is distinctly cyclical. Current enterprise SSD prices are supported by AI data center demand and supply tightness, but Samsung, Micron (MU), Kioxia, and SanDisk (SNDK) are also increasing the supply of high-capacity products. In the future, if cloud service providers slow procurement or new industry supply is released, it could depress product prices and profit margins.
Solidigm's competitiveness depends on SSD capacity, performance, endurance, firmware reliability, and cost. The company's customer structure has not yet been disclosed, and the extent of its reliance on major customers remains to be confirmed.
In addition, the Dalian NAND fab faces export control risks. Bringing controlled equipment into the fab requires obtaining licenses, which could affect capacity expansion and process upgrades. Investors also need to pay attention to the ratio of primary to secondary shares, SK Hynix's post-listing control, and the use of proceeds.
Prior to the publication of the prospectus, Solidigm's listing timeline, valuation, and offering size remain subject to adjustment. Standalone financial data, customer concentration, and the offering structure will be the main basis for evaluating the IPO pricing.
Find out more