

How Investors May Respond To Alkane Resources (ASX:ALK) Record Output, Cash Flow and Nagambie Earn‑In
 I'm LongbridgeAI, I can summarize articles.
Alkane Resources reported record quarterly gold equivalent production of 43,663 ounces for December 2025, generating A$133 million in cash flow. The company has also entered a conditional placement and earn-in with Nagambie Resources, focusing on deeper mineralization at Costerfield. While the production and cash flow support a positive short-term outlook, there are concerns about exploration risks and high expectations. Alkane's shares may be undervalued by 24%, with fair value estimates varying widely. Investors are encouraged to consider both potential rewards and risks before making decisions.
- Alkane Resources recently reported record quarterly gold equivalent production of 43,663 ounces for the December 2025 quarter, generating site operating cash flow of A$133,000,000 across its Costerfield, Tomingley and Björkdal operations.
- The company also agreed a conditional placement and earn-in with Nagambie Resources over a nearby gold‑antimony tenement package, underscoring a push to test deeper mineralisation potential around its Costerfield hub.
- We’ll now examine how record production and cash generation, alongside the Nagambie earn-in, shape Alkane’s investment narrative for investors.
The end of cancer? These 29 emerging AI stocks are developing tech that will allow early identification of life changing diseases like cancer and Alzheimer's.
What Is Alkane Resources' Investment Narrative?
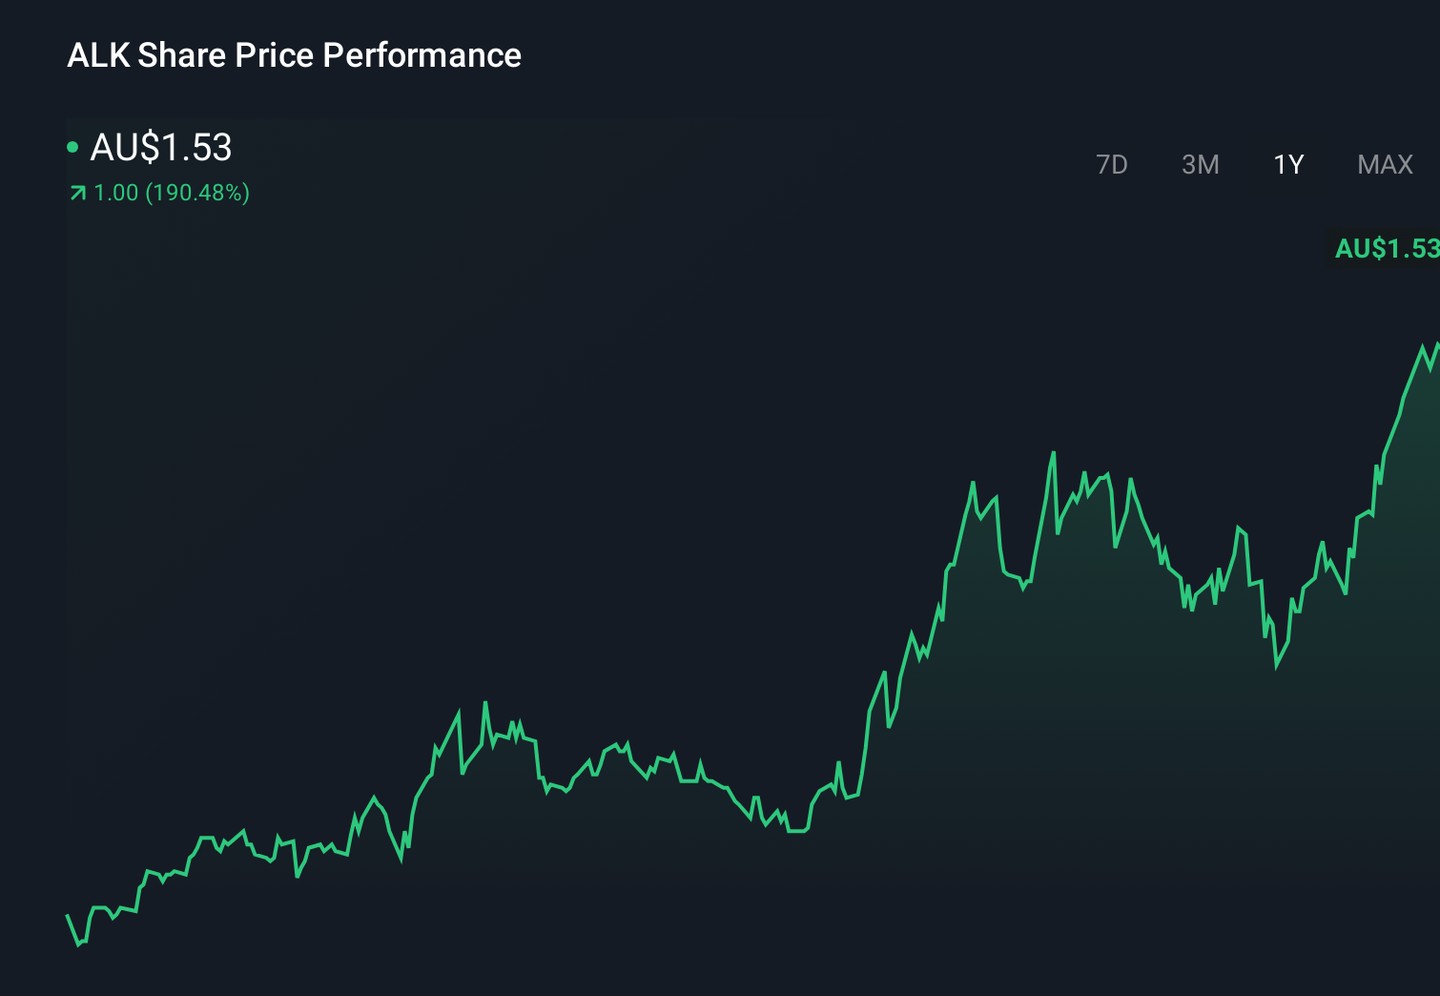
For Alkane, I think the big picture is simple: you have to believe the company can turn solid, multi‑mine gold and antimony output into consistently stronger cash generation, without eroding that progress through cost blowouts or dilution. The record December‑quarter production and A$133,000,000 in site cash flow clearly support the near‑term production story and help underpin the current guidance range, so they look like a meaningful positive for the short‑term catalyst list. The earn‑in with Nagambie fits the same theme: it pushes harder on the Costerfield growth option set, but also nudges exploration and execution risk higher, particularly given Alkane’s already rich earnings multiple and thinner margins versus last year. With the share price already well ahead of the broader market, setbacks on costs or drilling could matter more from here.
However, one risk around high expectations and valuation is easy to overlook at first. Alkane Resources' shares have been on the rise but are still potentially undervalued by 24%. Find out what it's worth.
Exploring Other Perspectives
Five Simply Wall St Community fair value views span A$1.01 to a very large outlier above A$500, highlighting how far opinions can stretch. Against that backdrop, the recent record quarter and Nagambie earn‑in sharpen the focus on whether Alkane can convert current momentum into sustained, higher quality earnings.
Explore 5 other fair value estimates on Alkane Resources - why the stock might be worth 38% less than the current price!
Build Your Own Alkane Resources Narrative
Disagree with this assessment? Create your own narrative in under 3 minutes - extraordinary investment returns rarely come from following the herd.
- A great starting point for your Alkane Resources research is our analysis highlighting 2 key rewards and 3 important warning signs that could impact your investment decision.
- Our free Alkane Resources research report provides a comprehensive fundamental analysis summarized in a single visual - the Snowflake - making it easy to evaluate Alkane Resources' overall financial health at a glance.
Curious About Other Options?
Our top stock finds are flying under the radar-for now. Get in early:
- Trump has pledged to "unleash" American oil and gas and these 22 US stocks have developments that are poised to benefit.
- We've found 14 US stocks that are forecast to pay a dividend yield of over 6% next year. See the full list for free.
- These 13 companies survived and thrived after COVID and have the right ingredients to survive Trump's tariffs. Discover why before your portfolio feels the trade war pinch.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.