

SpaceX Stock Pressured Despite Its Wireless Hopes as Credit Risk Jumps
 I'm LongbridgeAI, I can summarize articles.
SpaceX stock faced pressure, closing at $162.57, despite acquiring a $8 billion low-band spectrum portfolio to expand Starlink's wireless ambitions. Rising credit risk drove the decline, with investors jittery over plans to raise $40 billion for Nvidia chips, evidenced by widening credit default swap spreads and rising bond yields. However, analysts remain bullish on revenue growth, projecting full-year earnings of $45 billion driven by AI deals, maintaining an average price target of $219.
SpaceX (NASDAQ:SPCX) stock remained under pressure last week, even after the company outlined its wireless ambitions. It closed the week at $162.57, down from this month’s high of $176.30. The weakness is largely due to rising credit risk, following reports that the company is seeking to borrow more money.
SpaceX Stock Pressured Despite Wireless Milestone
Space Exploration Technologies wavered after the company acquired a nationwide portfolio of licenses in the low-band spectrum. This is a major milestone because it will now become a bigger competitor to other telecom companies like AT&T, Verizon, and T-Mobile. The deal is reportedly worth over $8 billion.
SpaceX aims to make Starlink a big name in the internet industry. This is important because it is now its biggest cash generator. In the last earnings report, the company said that Starlink generated over $4.29 billion in revenue in the second quarter and over $1.65 billion in profits.
SpaceX faces some major challenges ahead. One of them is that it will need to deploy towers across major urban centers in the US, a process that will cost billions of dollars. At the same time, the industry is already highly competitive, with legacy carriers like AT&T and T-Mobile having a significant market share.
Read Also: Why Micron Stock is Struggling Despite Revenue Growth and a Low Valuation
SpaceX Credit Risks are Rising
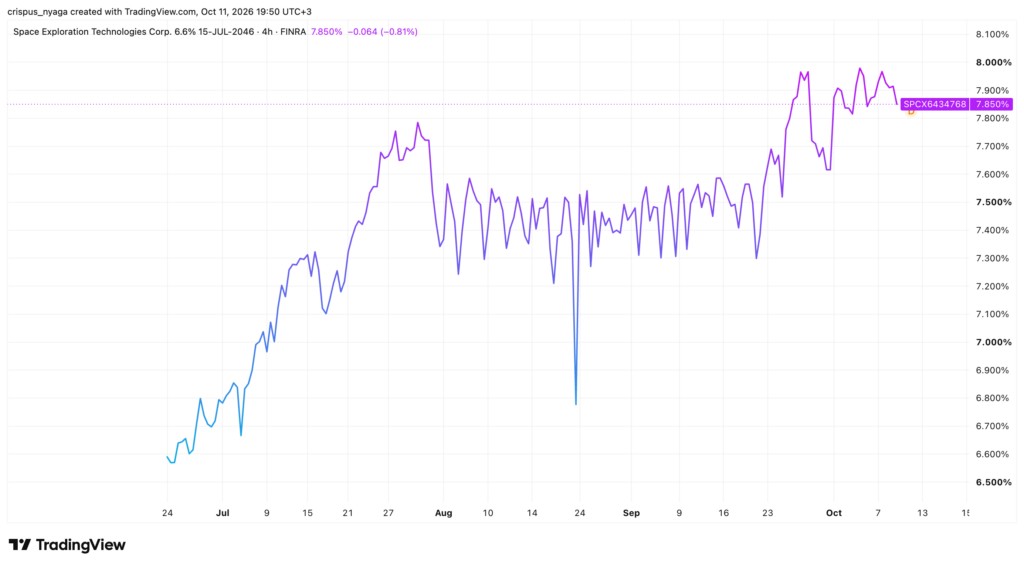
Meanwhile, investors in the bond market are getting jittery about its debt. These fears jumped after the FT reported that it was seeking to raise $40 billion to buy Nvidia (NASDAQ:NVDA) chips. $10 billion of these funds will be in the form of bank loans, with the remaining amount being in investment-grade bonds.
Recent data shows that the cost to insure against SpaceX’s debt has widened recently. The spread on its five-year credit default swaps rose to 195 basis points on Friday. This means that it costs about $19,500 annually to protect $1 million of its debt against default. SpaceX’s bond yields have also continued rising.
Analysts Expect SpaceX’s Revenue Growth to Continue
On the positive side, analysts expect SpaceX’s business to keep growing for the foreseeable future. Second-quarter revenue soared 92% to more than $7.8 billion, and analysts expect that momentum to continue in the near term.
The upcoming earnings report is expected to show that third-quarter revenue rose to $12.9 billion. Full-year revenue is projected to jump to $45 billion, driven by the company’s artificial intelligence business, which has already secured major deals with companies such as Google, Reflection AI, and Anthropic.
Analysts are also bullish on the shares, with the average price target of $219 implying a 35% upside from the current level.
Read Also: DRAM ETF Stuck in Bear Market: Top Catalysts for a Rebound in Memory Stocks
Image: Shutterstock