

TSMC Reports Oct. 15. It's the Best Early Read on Nvidia's Next Quarter.
 I'm LongbridgeAI, I can summarize articles.
TSMC reports Q3 results on Oct 15, serving as an early indicator for Nvidia's upcoming fiscal quarter. TSMC guided for revenue of $44.6B-$45.8B, up 12% sequentially. Key metrics to watch include high-performance computing revenue growth and packaging capacity constraints, which may limit customer expansion. While TSMC does not disclose specific customer breakdowns, Nvidia is believed to be its top client. The report will help assess whether AI demand supports Nvidia's $108B guidance.
Nvidia (NVDA -0.52%) likely won't post its fiscal third-quarter results until November. Last year, the artificial intelligence (AI) chip leader put out the same quarter's numbers on Nov. 19.
But investors will see the demand behind that quarter long before then. Taiwan Semiconductor Manufacturing (TSM -1.02%), which makes Nvidia's chips, reports its third-quarter results on Thursday, Oct. 15. And TSMC's quarter ran from July through September, covering around two of the three months in Nvidia's fiscal quarter, which closes in late October.
TSMC has guided for third-quarter revenue of $44.6 billion to $45.8 billion. At the midpoint, that would be 12% higher than the second quarter and 37% more than a year before.
I think it's the best early look investors will have at Nvidia's next quarter. But it covers the whole AI chip market, not just Nvidia, and that limits what it can show.
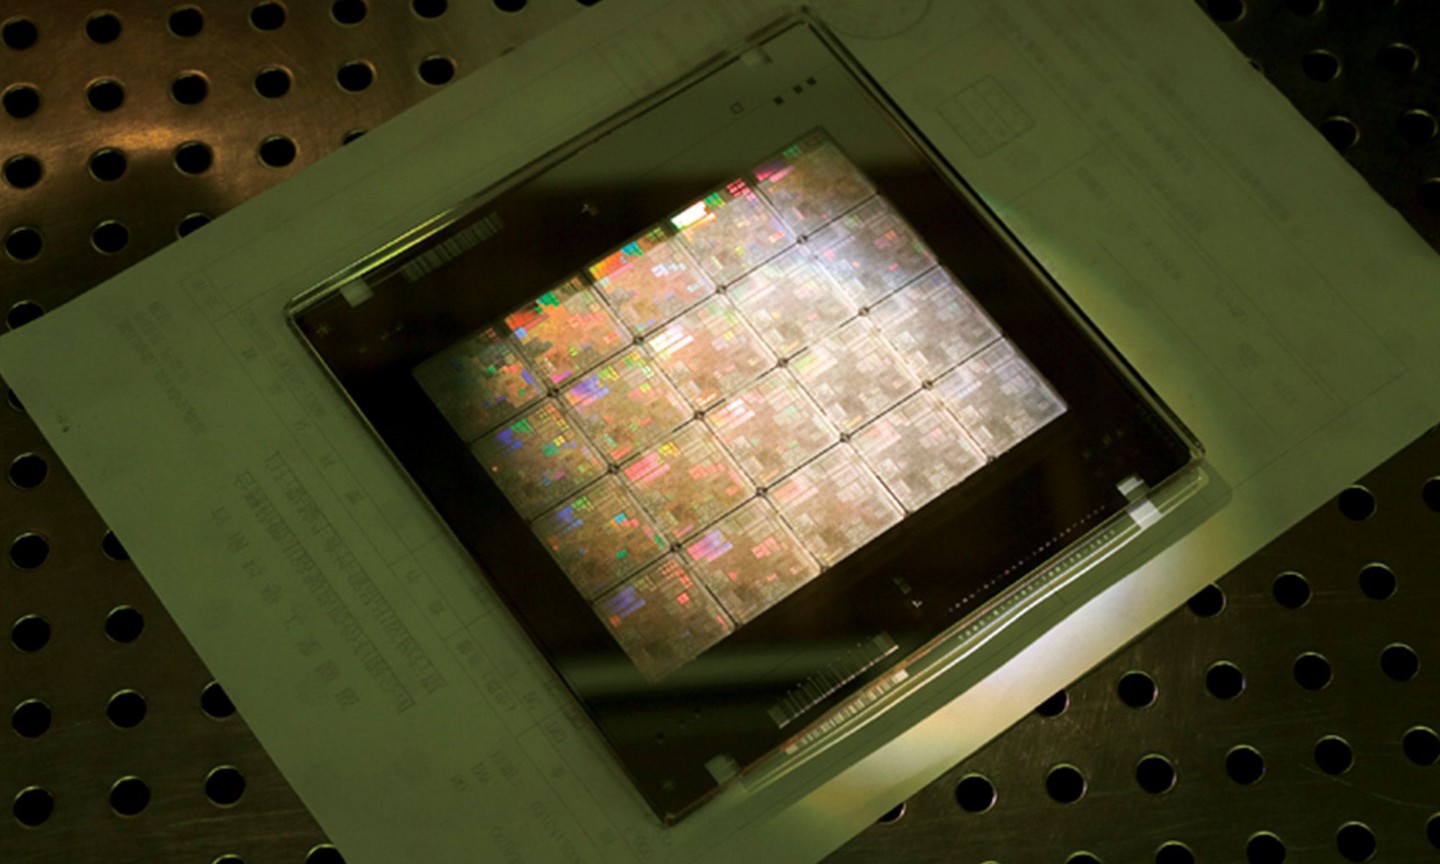
Image source: TSMC.
A head start
Nvidia's annual report says it uses foundries like TSMC and Samsung to make its chip wafers, and it depends on a packaging process called CoWoS. CoWoS is TSMC's technology for joining processors with stacks of fast memory in one package.
TSMC's results usually track the AI build-out, and they come first. Its monthly sales through August already pointed to a strong quarter. July revenue rose around 45% year over year in New Taiwan dollars, and August revenue climbed about 53%.
Nvidia, for its part, has guided for about $108 billion in fiscal third-quarter revenue, plus or minus 2%. Hitting that figure would put growth around 89% over the $57.0 billion it posted for the same period a year before -- a slowdown from 106% growth in fiscal Q2 (which ended July 26, 2026).
Notably, both companies' AI businesses have moved together lately. Showing how much AI demand is fueling TSMC, its revenue from high-performance computing (the platform that includes AI chips) jumped 20% from the first quarter to the second. In Nvidia's fiscal second quarter, which largely overlapped the same months, its data center revenue climbed 18% sequentially to $89.0 billion.
TSMC won't name Nvidia
TSMC doesn't say how much of its revenue comes from Nvidia. Its 2025 annual report lists its top customers just by letter, and the one it labels "Customer A" grew from 12% of revenue in 2024 to 19% in 2025. Nvidia is reportedly that customer.
That still leaves around four-fifths of TSMC's revenue coming from other customers.

NYSE: TSM
Key Data Points
TSMC's AI numbers also lump Nvidia in with its competitors. The company defines AI accelerators as graphics processing units, custom AI chips, and the controller chips for high-bandwidth memory used in data centers. So part of any jump may be from custom chips designed by other companies, not from Nvidia.
And TSMC's report can't show what Nvidia charges for its systems. Nvidia's gross margin was 75% last quarter, and that figure depends on Nvidia's pricing much more than on how many wafers TSMC ships.
Which TSMC numbers matter most for Nvidia?
The first number I'd watch is revenue from high-performance computing. This platform made up 66% of TSMC's second-quarter revenue, compared to 61% in the first quarter and 60% a year before. Another double-digit sequential gain in high-performance computing may suggest the demand behind Nvidia's $108 billion guidance is holding up.
The second is TSMC's packaging capacity, which has been below what customers want.
"[O] ur packaging capacity is so tight that now it limits my customers' growth," TSMC Chairman and CEO C.C. Wei said in July, on TSMC's second-quarter earnings call.
If that's still true, Nvidia's sales in the next few quarters could depend as much on TSMC's capacity as on customer demand. Of course, TSMC's full-year forecast also matters. Management expected 2026 revenue growth close to 30% in January, upped that to above 30% in April, and lifted it again in July to just above 40% in U.S. dollar terms. Another raise on Oct. 15 would arguably be a stronger sign of AI demand than the quarter's revenue alone.

NASDAQ: NVDA
Key Data Points
As for Nvidia's stock, shares trade near $237 as I write this. That's about 15 times expected earnings for the fiscal year ending in January 2028, using analysts' average forecast -- a price that already allows for growth to slow from today's pace.
Ultimately, TSMC's report can support the case for Nvidia stock or cast doubt on it, though it can't settle it. I'd say the stock looks reasonably priced for a business still guiding for growth around 90%.