

Western Digital Earnings Preview: Revenue Expected to Rise 47%, Highest Wall Street Price Target at $900
 I'm LongbridgeAI, I can summarize articles.
Western Digital (WDC) is set to report Q1 fiscal 2027 earnings on October 22, with revenue expected to rise 47% year-over-year to $4.14 billion and adjusted EPS projected at $4.11, driven by AI data center demand. Wall Street remains bullish, with Bank of America raising its price target to $800 and the highest consensus target reaching $900. Key focus areas include gross margin expansion, supply-demand balance in hard drives, and whether management will raise guidance to sustain market confidence.
TradingKey - Western Digital (WDC) will report its first-quarter fiscal 2027 financial results after the U.S. market close on October 22, Eastern Time. Driven by growing storage demand from cloud computing and AI data centers, the market expects the company's revenue and earnings to continue rising significantly.
According to FactSet data, Western Digital's revenue for this quarter is expected to be $4.14 billion, up about 47% year-over-year, while adjusted earnings per share are projected at $4.11, up roughly 131% year-over-year. This expectation is near the upper end of the company's previous guidance, which set revenue at $4.0 billion to $4.2 billion and adjusted EPS at $3.85 to $4.15.
AI Data Center Demand Supports Revenue Growth
Western Digital's current growth is mainly driven by demand for high-capacity Nearline hard drives in cloud computing and AI data centers. As AI models, videos, and enterprise data increase rapidly, hyperscale cloud service providers need to continuously expand storage capacity, and high-capacity hard drives remain an important solution for cold data and massive data storage.
In the previous quarter, Western Digital's revenue reached $3.75 billion, up about 44% year-over-year and above market expectations of $3.7 billion; adjusted earnings per share were $3.56, also exceeding analysts' expectations of $3.31. The company's full-year revenue reached $12.9 billion, up 35.7% year-over-year.
Despite revenue and earnings for the last quarter both beating expectations, Western Digital's stock price fell noticeably after the earnings release, as the company's guidance was only slightly above market consensus, while competitor Seagate (STX) provided a stronger margin forecast. This also demonstrates that with the market already pricing in sustained growth in AI storage demand, simply meeting expectations may not necessarily be enough to drive the stock higher.
This earnings report needs to further confirm whether orders from cloud service providers continue to grow and whether the new generation of high-capacity hard drives can successfully scale up production. If revenue approaches or exceeds $4.2 billion and management raises guidance for the next quarter, market confidence in the sustainability of the AI storage cycle may be strengthened.
Hard Drive Prices and Gross Margins Become Key to Earnings
Western Digital previously projected that its non-GAAP gross margin for the current quarter would be between 55% and 56%, with a higher proportion of high-capacity products, rising hard drive prices, and cost improvements expected to drive further recovery in profitability.
Bank of America (BAC) expects that Western Digital's first-fiscal-quarter gross margin could reach 56.4%, slightly above the upper end of the company's guidance; by the December quarter, as pricing continues to improve, the gross margin could further approach 59%.
The hard drive industry has maintained a relatively disciplined capacity strategy in recent years, improving the supply-demand balance. Meanwhile, cloud service providers are increasingly leaning toward long-term supply agreements, giving manufacturers higher order visibility. Western Digital previously stated that some customer agreements extend through 2031, which helps mitigate price volatility in traditional storage cycles.
However, the market still needs to monitor competitors' capacity expansions, new product yields, and customer procurement pacing. If industry supply grows faster than demand, or if cloud vendors delay data center projects, hard drive prices and profit margins could come under renewed pressure. Recent news that Toshiba plans to increase hard drive capacity once raised market concerns over supply expansion.
Wall Street Sees Up to $900
Wall Street as a whole remains bullish on Western Digital's upside. According to data compiled by TipRanks, the 12-month average price target for the stock from 17 analysts covering it over the past three months is $649.56, with a high forecast of $900 and a low of $450. Based on the latest stock price of $378.51, the average price target implies a potential upside of approximately 71.61%.
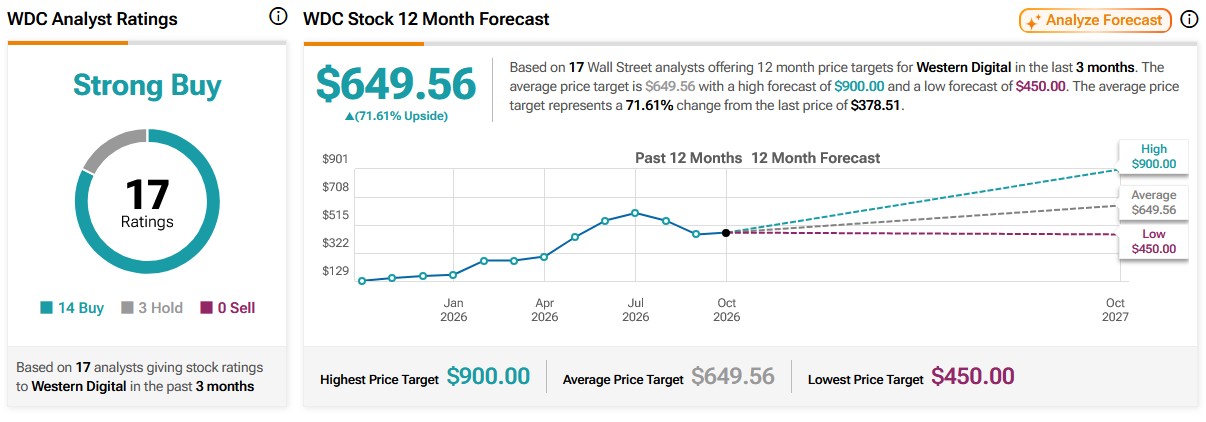
Source: TipRanks
Ahead of the earnings release, Bank of America raised its price target on Western Digital to $800 from $720 while maintaining its "Buy" rating, believing that rising prices for high-capacity hard drives and an improved product mix will continue to drive gross margin expansion, while storage demand from AI data centers also shows strong sustainability.
Morgan Stanley (MS), meanwhile, maintained its "Overweight" rating while lowering its price target to $643, pointing out that the hard drive industry is simultaneously benefiting from expanding demand, a growing customer base, and pricing improvements, with fundamental characteristics closely resembling previous memory chip upcycles.
However, higher price targets also imply that the market has already priced in strong growth expectations. Beyond meeting revenue and earnings consensus, gross margin and guidance for subsequent quarters in this earnings report must likewise not disappoint.