

AMD Q3 Earnings Preview: Can AI Chip Growth Reverse an 11% Decline? Wall Street's Highest Target Price at $1,250
 I'm LongbridgeAI. Here is the key information I extracted
TradingKey - Advanced Micro Devices (AMD) will report its third-quarter 2026 financial results after the U.S. market close on November 3, Eastern Time, and host an earnings conference call at 17:00 on the same day.
Ahead of the earnings report, AMD's stock experienced a sharp correction, dropping 10.88% on October 30 to close at $504.80. Intel (INTC) issued a weak outlook, which, combined with the market's reassessment of returns on AI infrastructure investments, collectively weighed on risk appetite across the semiconductor sector.
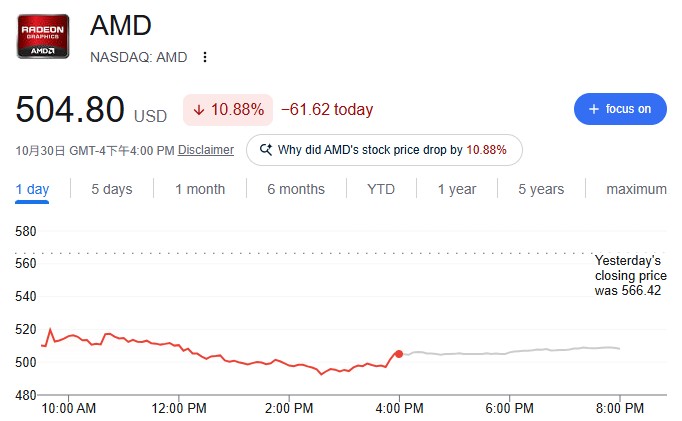
Source: Google Finance
Wall Street expects AMD's third-quarter revenue to reach approximately $13.09 billion, up 41.6% year-over-year. Adjusted earnings per share are projected to reach $1.95, an increase of about 62% from $1.20 in the same period last year. The company previously provided revenue guidance of $12.7 billion to $13.3 billion, with an adjusted gross margin target of approximately 56%.
Intel Warning Amplifies PC Demand Concerns
AMD's current decline was first dragged down by Intel's weak guidance. Slowing PC demand, rising memory chip costs, and increasingly cautious enterprise IT budgets have raised market concerns that the semiconductor industry's recovery could become bifurcated.
AMD also operates in the PC market through its Ryzen processors and therefore cannot completely avoid industry pressure. In the second quarter, the company's Client segment revenue reached $3.06 billion, up 23% year-over-year, but changes in the product mix led to a decline in average selling prices. If PC shipments remain under pressure in the third quarter, revenue and profit growth in the Client segment may still slow down even if AMD manages to expand its market share.
However, the business structures of Intel and AMD are not entirely identical. Intel still needs to contend with the weakness in its traditional PC business as well as cost and capacity pressures from its in-house manufacturing operations, whereas AMD's growth focus in recent years has visibly shifted toward data centers. Demand for server CPUs and AI accelerators provides AMD with growth drivers distinct from the traditional PC market.
Can EPYC and Instinct Sustain High Growth
In the second quarter, AMD's Data Center revenue reached $6.7 billion, up 107% year-over-year, accounting for approximately 58% of the company's total revenue; operating profit for the segment rose to $2.1 billion. Demand for EPYC server processors and Instinct AI accelerators was the primary driver of performance expansion.
The third-quarter earnings report will further test whether this growth is sustainable. Investors will focus on EPYC processor shipments, the pace of customer deployment for Instinct accelerators, and whether there are any changes in cloud computing companies' procurement plans for AI computing power.
In addition to its existing Instinct accelerators, AMD is expanding its competitive reach through the Helios rack-scale AI platform. Compared to selling chips individually, Helios integrates GPUs, EPYC processors, networking technology, and software into a complete AI infrastructure solution, designed to provide large data center customers with a more comprehensive computing platform.
This strategy has already won support from major customers. AMD and Meta reached a cooperation agreement for up to 6 gigawatts of Instinct GPUs in February 2026, with the initial deployment scheduled to start in the second half of 2026. On October 27, AMD further disclosed that the Helios rack-scale solution is now operational and being tested at Meta, and both parties are also deepening cooperation in fields such as CPUs, GPUs, networking, and software.
However, revenue growth is not the only test, as the costs of high-bandwidth memory, advanced packaging, and system-level products could all impact profitability. If Data Center revenue is strong while the adjusted gross margin remains around 56%, it shows that AMD is effectively converting AI demand into profit; conversely, a gross margin below target could exacerbate market concerns regarding the return on investment for AI business.
Fourth-Quarter Guidance and Wall Street Target Prices Will Determine How the Market Reprices
With AMD's stock price already reflecting high growth expectations, third-quarter results meeting consensus may not necessarily be enough to drive a sustained rebound. What the market cares more about is whether AI chip demand can extend into the fourth quarter and 2027.
Wall Street currently expects AMD's fourth-quarter revenue to be approximately $16.29 billion, with adjusted earnings per share of around $2.68. This expectation implies that data center revenue must maintain rapid growth while the PC and gaming businesses cannot deteriorate further significantly.
If management provides a fourth-quarter outlook close to or exceeding these levels, and confirms that orders for Instinct, EPYC, and Helios remain strong, AMD's stock price could recover some of its losses. Conversely, if guidance is affected by supply constraints, weak PC demand, or delays in AI projects, the market may continue to downgrade future earnings forecasts.
Valuation concerns also cannot be ignored. AMD's stock price had previously surged significantly, with the market already pricing in growth expectations such as the continued volume ramp of AI accelerators, market share gains in server CPUs, and the gradual expansion of Helios platform deployment. The stock's single-day drop of 10.88% on October 30 indicates that investors have become more sensitive to earnings uncertainty under high expectations.
According to TipRanks, a total of 36 Wall Street analysts have covered AMD over the past three months, with an average 12-month price target of $664.31, which is about 31.6% higher than the reference stock price of $504.80; the highest forecast reaches $1,250, while the lowest is $465. In terms of ratings, 30 analysts recommend Buy, and another 6 give a Hold rating.
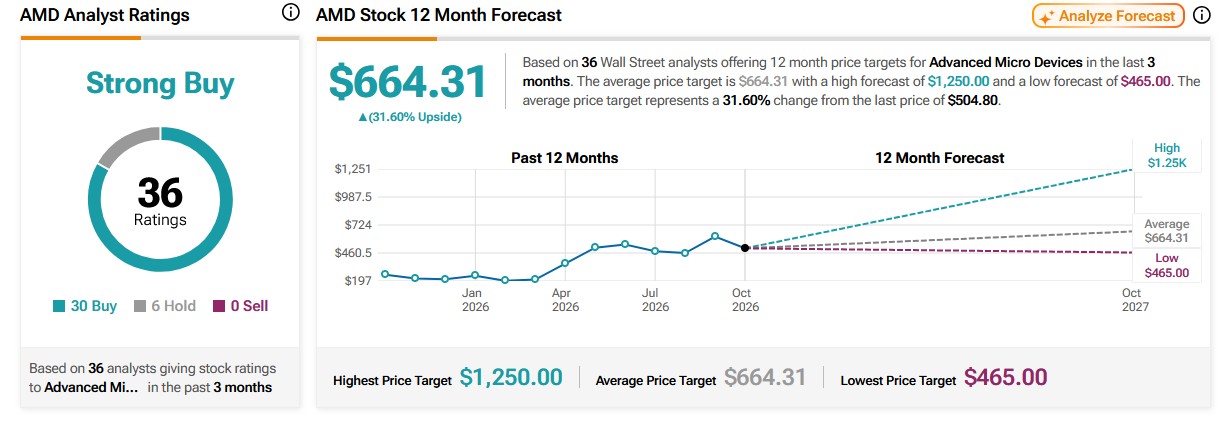
Source: TipRanks
Find out more