

Oracle Has Incredible News for Intel Stock Investors
 I'm LongbridgeAI. Here is the key information I extracted
Intel (INTC -7.80%) witnessed a brutal sell-off last week after releasing its third-quarter results on Oct. 29, primarily due to weaker-than-expected guidance that led investors to press the panic button.
Intel's personal computer (PC)-focused client business is not in the best shape now due to a steep drop in PC sales. Of course, Intel needed to live up to Wall Street's expectations to justify the impressive surge the stock has witnessed since the beginning of 2025. However, the weakness in the PC market is beyond Intel's control.
Moreover, Intel is doing well in data centers, with its artificial intelligence (AI)-focused server chips in solid demand from hyperscalers and AI companies. Oracle (ORCL -5.27%) is one such company that will deploy Intel's server central processing units (CPUs) in large numbers. Let's look at the reasons why the Oracle contract could be a big one for Intel.

Image source: Getty Images.
Intel is poised to win big from Oracle's AI data center build-out
Just a couple of days ahead of Intel's quarterly report, the semiconductor giant announced a multiyear collaboration with Oracle to deploy its Xeon server CPUs. Oracle will deploy Intel's current and future generations of Xeon server CPUs to handle agentic AI workloads on Oracle Cloud Infrastructure (OCI).
INTC - Intel
NASDAQ · As of 10:19 AM ET 11/05/26
 Moneyball Superscore65/100
Key data points
This bodes well for Intel, given that OCI revenue has been growing at a brisk pace. Oracle reported a 121% year-over-year increase in OCI revenue in the previous quarter to $7.4 billion. This segment can sustain its terrific momentum over the long run owing to Oracle's $664 billion in remaining performance obligation (RPO), the total value of contracts the company has yet to fulfill.
Oracle expects to accelerate the conversion of its RPO into revenue going forward, driven by the company's significant investments to bring additional data center capacity online. Intel will provide Oracle with "additional capacity and planned processor capabilities as customers extend existing enterprise systems with AI."
This should ensure strong growth in Intel's server CPU business. Notably, Intel estimates that the total addressable market (TAM) for server CPUs could increase 5x over the next five years, reaching $400 billion. Chipzilla's ability to land a major customer like Oracle should allow it to capture a significant share of this massive opportunity.
As a result, I won't be surprised to see Intel's data center and AI (DCAI) segment sustain the healthy growth that it has been clocking.
Intel's data center growth is accelerating
Intel's DCAI segment revenue increased by 78% year over year in Q3 to $7.3 billion. For comparison, the company's DCAI revenue increased by 22% year over year in Q1 and by 59% in Q2.
Importantly, Intel management's comments on the latest earnings call indicate that its DCAI revenue will continue to grow at a solid pace, which isn't surprising, given the interest in its server CPUs from a hyperscaler such as Oracle. Specifically, Intel notes that demand signals from its data center customers are strengthening, primarily due to the growing adoption of agentic AI, which is driving increased server CPU demand.
As a result, Intel expects demand for its data center CPUs to outstrip supply in 2027 and 2028. This should allow Intel to implement more price hikes given its position as the dominant player in the x86 server CPU market. Though Intel has been losing ground to Advanced Micro Devices in this niche, it still holds an impressive market share of 65.5%, according to Mercury Research.
The Oracle partnership should help Intel maintain its dominance in server CPUs, paving the way for further growth in revenue and earnings. After all, Intel is expected to increase CPU prices by 10% next year, which could positively impact the company's bottom-line performance.
What's worth noting is that there has been a substantial improvement in Intel's long-term earnings per share (EPS) growth expectations this year.
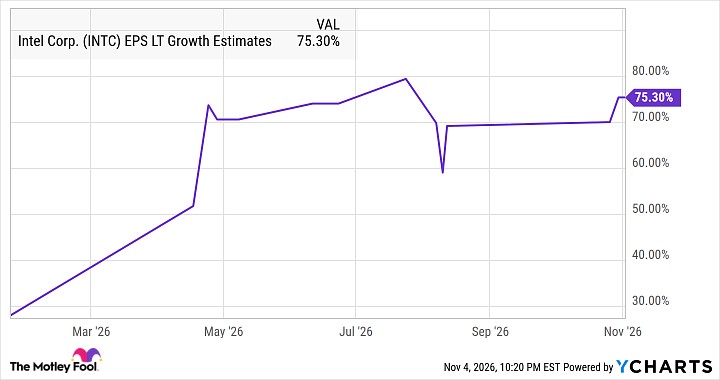
INTC EPS LT Growth Estimates data by YCharts
So, while Intel stock has taken a big beating after its latest quarterly report, the long-term prospects still appear to be sound. Throw in the fact that Intel is trading at an attractive 34 times forward earnings, a discount to the Nasdaq Composite index's average earnings multiple of 39, and it is easy to see why the stock is worth buying following its recent pullback.
So, savvy investors would do well to look at the bigger picture and consider using this semiconductor stock's drop to buy more shares, as its accelerating data center business could eventually help it step on the gas once again.