

22nd Oct 🇸🇬 Blink Fans: Singapore Market & Interest Rates Update
 I'm LongbridgeAI, I can summarize articles.
22 October 2026 · Singapore market perspective
📊 1️⃣ Singapore market: What should investors watch?
Singapore’s market is influenced by three major forces: bank earnings, interest-rate expectations and global market sentiment.
For investors watching the Straits Times Index (STI), DBS, OCBC and UOB, the key question is whether banks can continue generating healthy earnings while interest rates and funding costs change.
- 🏦 Singapore banks: Net interest margins, loan growth, deposit costs and credit quality remain important. Lower interest rates can put pressure on lending margins, although stronger loan demand and other income may offset some of the impact.
- 📉 Global risk sentiment: When Wall Street sells off, Singapore shares can face pressure too, particularly when investors reduce exposure to equities.
- 💰 Dividend appeal: Singapore banks may continue attracting income-focused investors, but dividends are not guaranteed and share prices can still fall.
- 🇸🇬 STI outlook: Watch whether the index is supported by bank shares or whether weakness spreads across multiple sectors.
The important lesson? A falling share price does not automatically mean a stock is cheap. I would examine earnings, valuation, dividend sustainability and the reason behind the decline before deciding whether to buy.
💹 2️⃣ Latest Singapore market snapshot
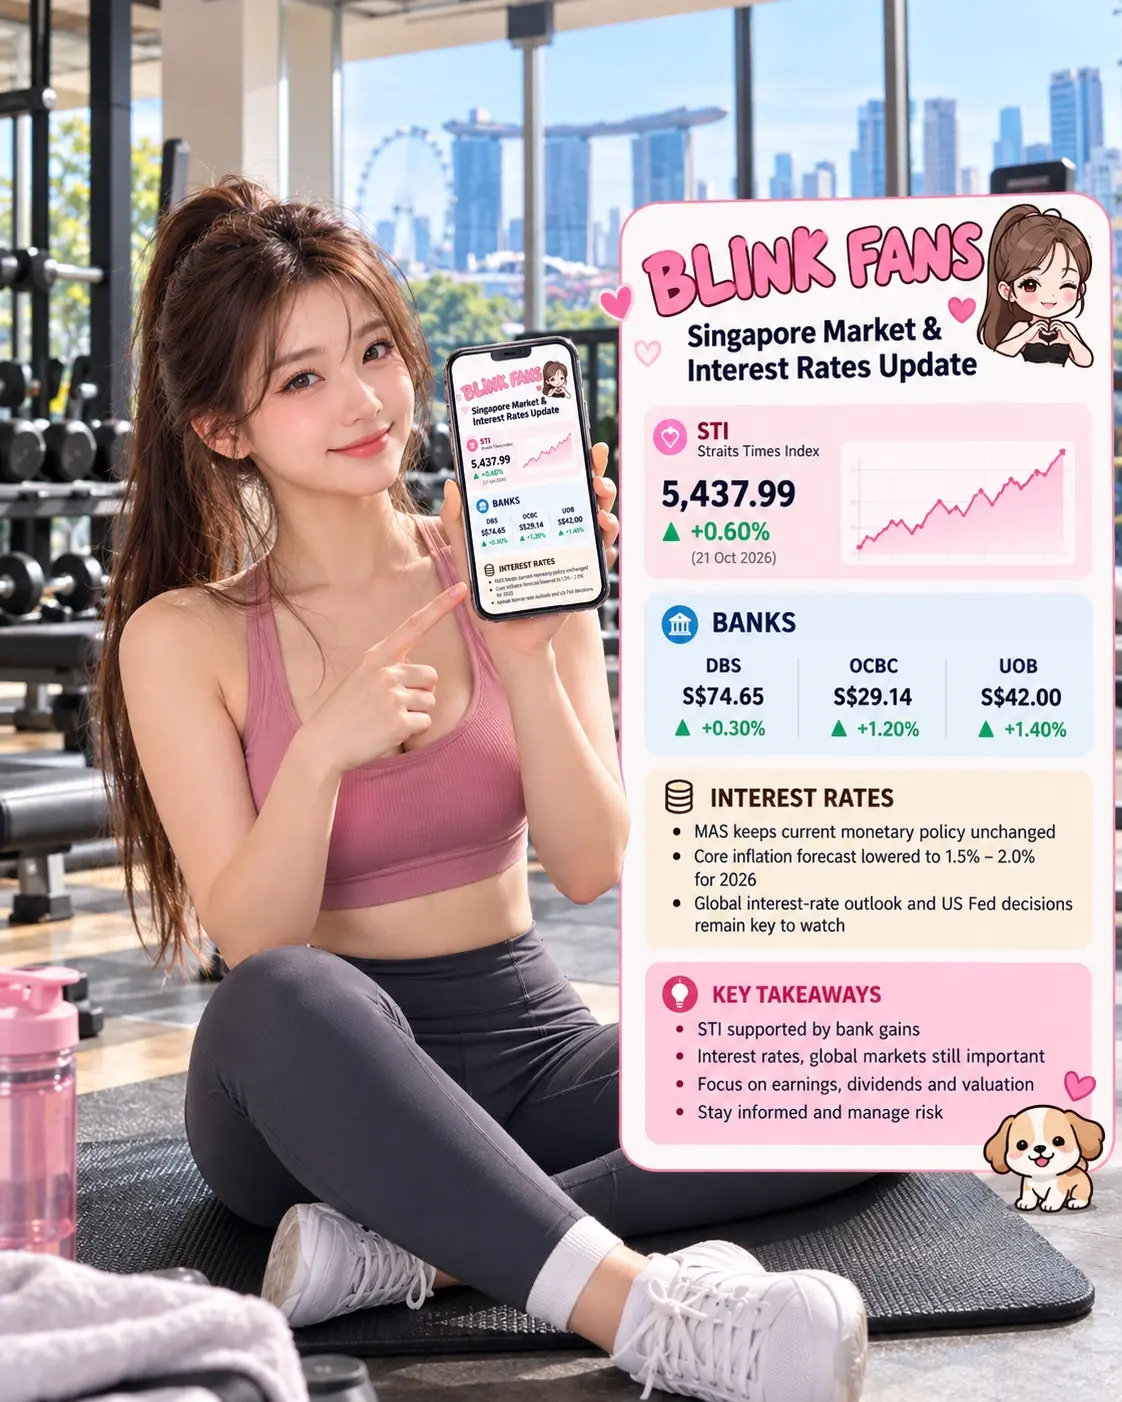
The STI gained 0.6% on Wednesday, supported by gains in all three major local banks. However, global growth concerns and elevated borrowing costs remain risks for equities.
🏦 3️⃣ Interest rates: The big story for Singapore
The latest important development is that the Monetary Authority of Singapore (MAS) maintained its existing Singapore dollar appreciation policy in its October review. Singapore manages monetary conditions mainly through the exchange rate rather than a conventional policy interest rate.
🏠 Homeowners and mortgages
Higher market interest rates can increase floating-rate mortgage costs. Homeowners should compare their actual loan packages and refinancing terms instead of assuming that every mortgage moves in line with the US Federal Reserve.
🏦 DBS, OCBC and UOB
Higher lending rates may support margins if loan yields rise faster than deposit costs. But rising deposit competition can eat into that benefit. Banks also earn money from wealth management, fees and other services.
🏢 Singapore REITs
Higher borrowing costs can raise refinancing expenses and make dividend yields less attractive relative to bonds. REITs with manageable debt, longer debt maturities and sustainable distributions may be better positioned.
💰 Cash, T-bills and bonds
Rising yields can improve returns on newly purchased fixed-income securities. Existing fixed-rate bonds, however, may decline in market value when yields rise. Compare actual yields, maturity dates and liquidity before committing funds.
🌏 4️⃣ Why the US Federal Reserve matters
The US Federal Reserve’s rate decisions affect global bond yields, the US dollar and financial conditions. Singapore is not required to copy every Fed move, but the effects can flow through to local borrowing costs, the Singapore dollar and investor sentiment.
The current backdrop is particularly interesting because MAS expects core inflation to average 1.5–2.0% in 2026 and 1.5–2.5% in 2027, while inflation risks remain tilted to the upside. MAS also expects Singapore’s unusually strong AI-related economic expansion to moderate in 2027.
🎯 5️⃣ My Blink Fans investment game plan
1️⃣ Why am I making this trade now?
I am watching the Singapore market because bank valuations, interest-rate expectations and global risk appetite can create opportunities even when the overall market is uncertain. I would not buy a bank simply because its share price falls, nor sell it simply because interest rates rise. I want to understand whether the change improves or weakens its future earnings.
2️⃣ What’s my plan from here?
- 🏦 Banks: Monitor net interest margins, deposit costs, loan growth and upcoming earnings.
- 🏢 REITs: Look for sustainable distributions, reasonable gearing and refinancing risks.
- 💵 Cash and bonds: Compare available yields against the risk and liquidity of equities.
- 📈 STI: Watch whether bank-led gains broaden across the market or begin to fade.
- 🌍 Global markets: Follow the Fed’s next policy decision and inflation data for clues about the direction of global borrowing costs.
My approach is to keep cash available, avoid chasing rallies and add to positions only when valuation and fundamentals justify the risk.
🐶 Blink Fans final takeaway: Singapore’s market still offers opportunities for income investors, but the interest-rate story is no longer as simple as expecting rates to fall. I want to know who benefits, who pays more to borrow, and whether the price already reflects those expectations.
This is a market commentary, not personalised financial advice.
Track Singapore market and interest-rate updates
$STI ETF(ES3.SG)


The copyright of this article belongs to the original author/organization.
The views expressed herein are solely those of the author and do not reflect the stance of the platform. The content is intended for investment reference purposes only and shall not be considered as investment advice. Please contact us if you have any questions or suggestions regarding the content services provided by the platform.