
longbridgelongbridge
  • Platform Features
    Features
    Investment ProductsPrivate Wealth ManagementTrading ToolsMarket Data ServicesAnalysis ToolsNews ServicesFor Developers
    Account Types
    For IndividualsFor Institutions
  • Café
longbridge
© 2026 Longbridge|Terms of ServicePrivacy Policy
Analyst Ratings Review
T
TheInvestingIguanaAJBURate Of Return1 day ago, 04:48 AM

FeaturedMaybank’s BUY Case for Addvalue Rests on a Viasat Deal. My Screen Runs on a Different Number Entire

Maybank’s BUY Case for Addvalue Rests on a Viasat Deal. My Screen Runs on a Different Number Entirely.Third-party validation from a US partner and a zero-dividend balance sheet are two different quest...

Maybank's BUY Case for Addvalue Rests on a Viasat Deal Third-party validation an
Every BUY Call Needs a LCTEAN Story fle Column Chart with Index Labels Maybank's
Strong Results-Not in Dispute 59.9% 147.5% 0% Revenue Growth Net Profit Growth D
2 In hThis Article+18
NASDAQ Composite Index

NASDAQ Composite Index

US.IXIC

Stock Safety AuditAnalyst Ratings Review
T
TheInvestingIguanaAJBURate Of ReturnSep 8 at 08:43 AM
Featured

$Addvalue Tech(A31.SG) Iggy's Journal: A Great Growth Story That Answers the Wrong Question


8 September 2026, PM


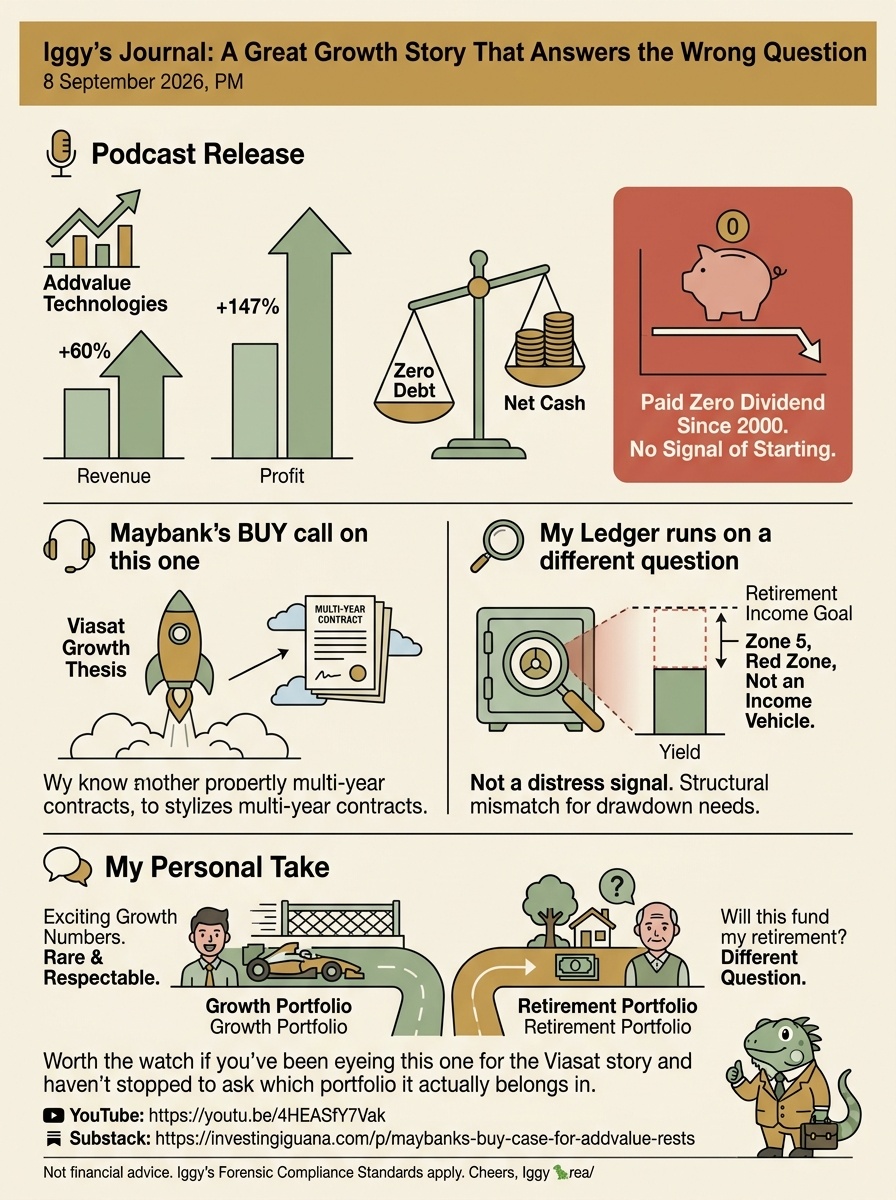
Podcast Release

New video's up on Addvalue Technologies, and this one's a genuinely interesting split. Revenue up 60%, profit up 147%, balance sheet cleaner than it's been in years, net cash, zero debt. By almost any growth measure, this is a good year for the company. And none of that changes the fact that Addvalue has paid zero dividend since it listed back in 2000, with no signal of starting now.


Maybank's BUY call on this one leans on Viasat converting into multi-year US defence contracts, a real growth thesis. My Ledger runs on a different question entirely, whether the yield is there to support income, and on that measure this lands as Zone 5, Red Zone, Not an Income Vehicle. Worth being precise about what that actually means here, it's not a distress signal, the underlying business is structurally sound. It's a mismatch between what this stock is built to do and what a retirement drawdown portfolio actually needs from it.


My Personal Take

Genuinely like the growth story here, that's not sarcasm, 147% profit growth with a fortress balance sheet is rare and worth respecting. But I keep seeing CPF and SRS holders get pulled toward names like this because the growth numbers are exciting, and exciting isn't the same question as "will this fund my retirement." Those are two completely different portfolios asking two completely different questions. Worth the watch if you've been eyeing this one for the Viasat story and haven't stopped to ask which portfolio it actually belongs in.


📺 YouTube: https://youtu.be/4HEASfY7Vak

📩 Substack: https://investingiguana.com/p/maybanks-buy-case-for-addvalue-rests

Not financial advice. Iggy's Forensic Compliance Standards apply.

Cheers, Iggy 🦖
Maybank's BUY Case for Addvalue Rests on a Viasat Deal. My Screen Runs on a Different Number 🦖

Maybank's BUY Case for Addvalue Rests on a Viasat Deal. My Screen Runs on a Different Number 🦖

🟢 Third-party validation from a US partner and a zero-dividend balance sheet are two different questions. Only one of them decides if this belongs anywhere ...

YouTube
Iggy's Journal: A Great Growth Story That Answers the Wrong C Question 8Septembe
Analyst Ratings Review
T
TheInvestingIguanaAJBURate Of ReturnSep 2 at 12:05 PM

Iggy's Journal: Maybank Just Put a $13 Target on Keppel, Betting the Old Conglomerate Story Is Over

2 September 2026, AM

Analyst Rating

Maybank Research has initiated coverage on Keppel Ltd (BN4) at Buy with a S$13.00 target price. The case rests on Keppel's shift away from a traditional conglomerate model toward asset management and infrastructure operations, spanning power generation, data centres, cooling, and subsea connectivity. Maybank's thesis is that this produces more recurring, capital-light earnings than the old business mix, supported by ongoing asset recycling that frees up capital for growth.

The numbers behind the call: FY25 to FY28 earnings growth of 10% to S$1.37 billion, asset management fees rising 17%, recurring income growing at a 12% CAGR, and core ROE improving from 19% to 23%. Maybank's sum of the parts splits value 52% operating businesses, 40% asset management, the remainder non-core. Forecast dividends are 42, 45, and 49 cents for FY26E, FY27E, and FY28E. Maybank flags slower asset recycling, weaker power spreads, softer digital demand, and non renewal of concessions as the key risks. Worth repeating, these are broker forecasts, not Keppel's own guidance.

My Personal Take

The dividend forecast is the number that actually catches my eye here, not the target price. My own numbers currently have Keppel sitting in my most cautious tier purely on distribution, the trailing payout still falls well short of what I look for. Maybank's 42 cent forecast for next year would be a real step up from that. If it lands, it changes the picture. If it doesn't, the capital light story still has to prove itself in the dividend, not just in the earnings growth line.

Not financial advice. Iggy's Forensic Compliance Standards apply.

Cheers, Iggy 🦖
Keppel's Evolution: From Industrial Conglomerate to AssetManagement Powerhouse TLong image
Analyst Ratings Review
T
TheInvestingIguanaAJBURate Of ReturnSep 2 at 06:52 AM

Iggy's Journal: UOB Kay Hian Says DBS Is Too Expensive. My Screen Says the Real Problem Is the Yield

2 September 2026, AM

New Video

New video is up. UOB Kay Hian and a blended fair value model looked at the same DBS share price this week and landed in different places. UOB Kay Hian calls the 2.97 times 2027 price to book stretched and trimmed its stance. The blended model puts fair value at S$85 against a S$76.85 price, still room to run on that read. Both are defensible on their own terms. Neither one answers the question a retirement portfolio actually needs answered.

My Personal Take

The number I keep coming back to is the yield, not the multiple. A fresh buyer at S$76.85 locks in 4.18%, short of my 4.7% hurdle. Someone who bought DBS years ago at S$30 is sitting on the same dividend and a yield closer to 10.6% on their original capital. Same stock, same payout, two completely different income realities depending on when you got in. Iggy's Forensic Zone: Zone 4, Caution. November earnings, and whatever dividend comes with them, is where this arithmetic moves next.

📺 https://youtu.be/3udV6XvlZYo

📩 https://investingiguana.com/p/uob-kay-hian-says-dbs-is-too-expensive

Get everything, zero-day access on both platforms, full Red Zone watchlist, institutional-grade cheatsheets, with Iggy's Elite Investors, S$12/month.

Not financial advice. Iggy's Forensic Compliance Standards apply.

Cheers, Iggy 🦖
UOB Kay Hian Says DBS Is Too Expensive. My Screen Says the Real Problem Is the Yield 🦖

UOB Kay Hian Says DBS Is Too Expensive. My Screen Says the Real Problem Is the Yield 🦖

🟢 A downgrade to Hold cites a stretched valuation. My screen finds the stock still missing its own income hurdle by 52 basis points, price up, yield down.UO...

YouTube
DBS TOO EXPENSIVE? ANALYST REAL PROBLEM: THE YIELD. IRATING 回 1o REVIEW 回 DBS PR
Analyst Ratings Review

Total Heat

Who to follow

LongbridgeAI