D
 +10
QCOM: Handset base erodes — even AI can't offset it?
Data center ramp is strong, but GPM is still compressing
+10
Data center ramp is strong, but GPM is still compressing
+10Data center ramps from FY27, with Q1 revenue over $650mn and the full-year $5bn target reaffirmed, lifting non-handset QCT revenue by over 60% YoY.
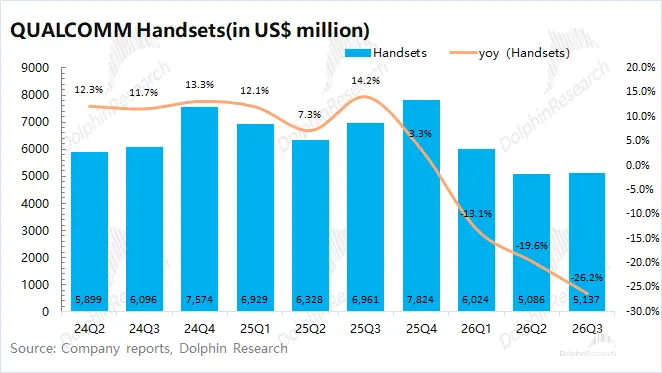
However, the handset market next year looks flat to slightly down, and price increases will not be fully reflected in GPM until 2H. Meanwhile, the company is betting on $15bn in data center revenue by FY29 via partnerships with AWS and SpaceX.
On Sep 8, Qualcomm announced a multi-generation partnership with Amazon to co-develop custom, scalable chips for large-scale AI data centers, focused on AI inference. The two will also jointly develop optical interconnect solutions supporting up to 1.6T rates, along with next-gen, forward-looking technologies.
$Qualcomm(QCOM.US) had disclosed at its Jun 24 Investor Day that it had secured hyperscale customers in custom ASICs and connectivity. This announcement reveals its collaboration with $Amazon(AMZN.US)...Qualcomm (QCOM) released FY26 Q3 results after U.S. market close, corresponding to the morning of Jul 30, 2026 Beijing time. The quarter ended Jun 2026, and key points include: 1) Core metrics.
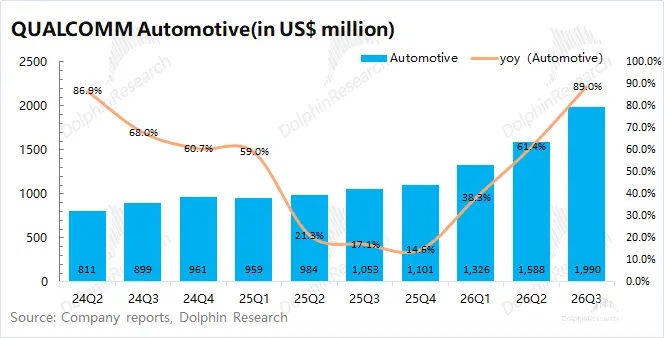
Revenue was $9.95bn (-4% YoY), beating the $9.6bn consensus. Auto grew sharply, but handsets remained a drag on the top line.GPM was 53.1% (-250bps YoY). This was below market expectations (54.6%). ...The following is Dolphin Research's Trans for the $Qualcomm(QCOM.US) FY26 Q3 earnings call.
1) Shareholder returns: $2.3bn was returned to shareholders this quarter, including $1.4bn in buybacks with the balance in cash dividends.
2) Results recap: FQ3 revenue was $9.9bn, at the high end of guidance, and non-GAAP EPS was $2.21; by segment, QCT delivered $8.5bn in revenue with a 26% EBT margin...
Below is Dolphin Research's Trans of QCOM 2026 Investor Day. Key financial highlights are as follows.
Shareholder returns: $40 bn returned to shareholders over the past five years, and 30% of shares repurchased and retired over the past decade. Looking ahead, dividend growth will stay in the low to mid single digits, with most FCF returned to shareholders.Financial targets were materially raised. The FY29 non-handset revenue target was lifted to $40 bn from $22 bn set 18 months ago, nearly doubling...Below are Dolphin Research's Trans for QCOM FY26 Q2 earnings call. For our take, see 'Qualcomm: Will This AI Booster Shot Offset the Handset Weakness?'.
I. $Qualcomm(QCOM.US) key takeaways.1) Shareholder returns: $3.7bn was returned to shareholders this quarter. This includes $2.8bn in buybacks and $945mn in dividends, with the capital return program running at an accelerated pace.2) Next quarter (FY26 Q3) guide. Revenue of $9.2-10.0bn...QCOM reported FY26 Q2 (quarter ended Mar 2026) after the U.S. close on Apr 30 (Beijing time).
Key takeaways: 1) Core metrics.Revenue was $10.6bn, down 3.5% YoY, in line with consensus ($10.56bn).
The renewed decline reflected a sluggish downstream handset market.GPM was 53.8% (-120bps YoY), below consensus at 54.6%.
Amid memory shortages...Below is Dolphin Research's Trans of Qualcomm's FY2026 Q1 earnings call. For our earnings analysis, see 'Qualcomm: Memory Crunch Deepens — Are Handset Stocks Doomed?'.
Key takeaways: 1) Memory shortage. Over the next few quarters, the smartphone industry will face constrained DRAM supply and higher prices. As memory suppliers shift capacity to HBM to meet AI data-center demand, shortages and price hikes are emerging, which could determine the industry's overall scale this fiscal year.2) OEMs. Several smartphone makers are adopting a cautious stance, especially Chinese brands. ...QCOM reported FY2026 Q1 results (quarter ended Dec 2025) in after-hours trading on Feb 5 (Beijing time). Key takeaways: 1) Core metrics.
Revenue was $12.25bn, up 5% YoY, in line with market expectations ($12.2bn). Growth decelerated again this quarter, mainly due to a sluggish downstream smartphone market.
GPM was 54.6%, down 120bps YoY and below consensus (55.2%). Amid tight memory supply...