D
 +9
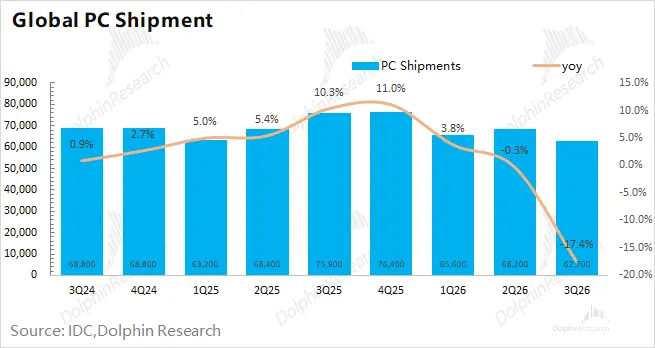
INTC: PCs 'crashed' — blip or real capitulation?
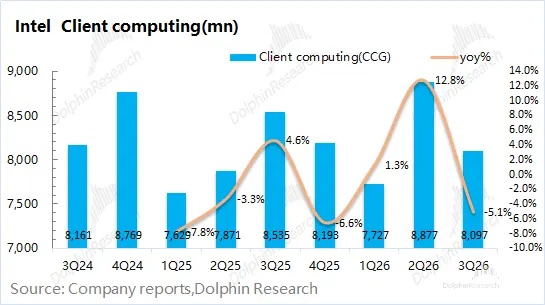
Guidance came in well below estimates. The PC pillar has crumbled.
+9
Guidance came in well below estimates. The PC pillar has crumbled.
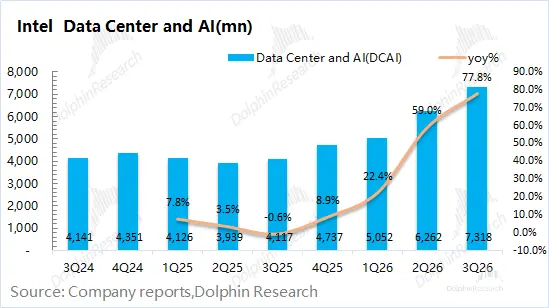
+9DCAI revenue rose nearly 80% YoY. Full-year revenue is on track to beat the initial outlook by almost $10bn.
However, an Israel fab shutdown and PC destocking drove Q4 guidance down to $15–16bn and GPM to 38%. The company expects the server CPU TAM to top $200bn within five years and is ramping 2027 capex.
On Muse's impact on CPUs, there is a different take circulating on X: 'In a base case, serving 100 mn DAUs requires ~1 GW of power, and only ~0.1 GW comes from the CPU/VM layer.' Depending on how many inference-equivalent model calls each Muse DAU generates per day, 3–4 GW makes complete sense. ...
Meta launched Muse on Sep. 8. Each Muse runs on a dedicated virtual machine, the Muse Secure VM, which stores both the agent and user data. Long-running jobs keep executing even after the app is closed, then re-engage the user when something changes or an approval is needed.
The product went viral, briefly topping the US mobile download charts. For details on Muse and its implications for Meta, see Dolphin Research's take 'Muse goes viral: real inflection or hype peak?'...INTC reported Q2 2026 results after the US close on Jul 24 (Beijing time). The quarter covered the period ended Jun 2026.
Key points: 1) Core metrics. $Intel(INTC.US) delivered revenue of $16.1bn (+25% YoY), well above company guidance of $13.8–14.8bn.
Growth was driven by the Client business and the Data Center & AI segment, with CPU price increases the largest factor.
GPM was 40.4%. That was above the Street's 37.6%...
Below is Dolphin Research's recap of $Intel(INTC.US) FY26 Q2 earnings call Trans. I. Core results review. 1) Q2 results beat guidance across the board, marking a seventh straight beat.
Revenue was $16.1bn, $1.8bn above the midpoint of guidance. AI-driven businesses grew over 70% YoY and contributed ~70% of revenue, including record growth in the data center. Non-GAAP GPM was 41.8%, ~280bps above guide, helped by higher revenue and yield improvements...
Below is Dolphin Research's transcript summary of $Intel(INTC.US) FY26 Q1 earnings call.
For our take, please see 'Intel: Leaving the darkest hour behind as the old champion mounts a counterattack.'1) Q1 beat across the board.
Revenue was $13.6bn, $1.4bn above the midpoint of guidance. Non-GAAP GPM came in at 41%, ~650bps ahead of guide.Non-GAAP EPS was $0.29 vs. breakeven guided.
This included approx. $0.06 from interest and other one-off gains...Intel released its Q1 2026 results (through Mar 2026) after the US market close on Apr 24, Beijing time. Key takeaways: 1) Core metrics: $Intel(INTC.US) reported revenue of $13.6bn (+7% YoY), well above company guidance ($11.7–12.7bn), driven by stronger server CPU demand and pricing.
GPM was 39.4%, far ahead of the market’s 32.5% expectation. The QoQ expansion in GPM...
Below is Dolphin Research's earnings call Trans for $Intel(INTC.US) Q4 2025. For our earnings review, see 'Intel: AI CPU hype meets cold guidance, dousing expectations?'
Key takeaways from the briefing: 1) 18A progress: Panther Lake announced, with three SKUs shipped ahead of plan (vs. one planned). Yields are improving by 7–8% per month, with efforts focused on containing process variation and stabilizing delivery. Defect density is coming down and the overall trend is improving...
Intel released its Q4 2025 results after the U.S. close on Jan 23, 2026 (Beijing time), for the quarter ended Dec 2025.
Key highlights are as follows.1) Core metrics: $Intel(INTC.US) posted revenue of $13.67bn, down 4% YoY, in line with guidance of $12.8–13.8bn, driven by softer Client Computing. GPM was 36.1%, matching the Street (35.6%). The QoQ GPM decline was mainly due to lower initial yields during the 18A mass-production ramp...