

China Mobile: Pricing slide not over; high dividend may be inflated?
 I'm LongbridgeAI, I can summarize articles.
China Mobile (600941.SH/0941.HK) released its Q3 2026 results (to Sep 2026) after the H-share market close on Oct 20, Beijing time. Key takeaways are as follows:
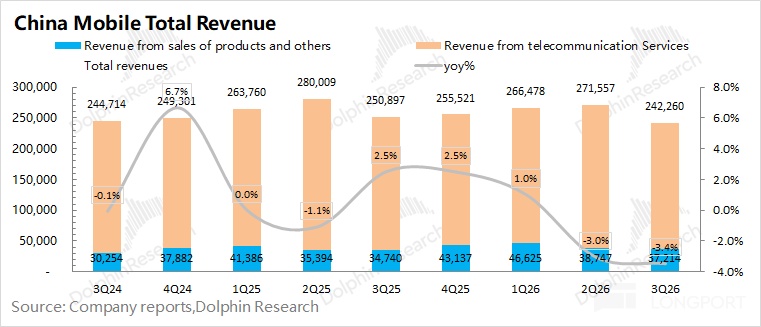
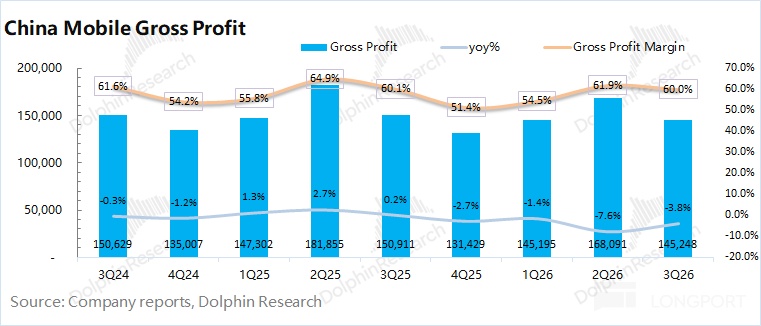
1) Operating metrics:$CHINA MOBILE(00941.HK) Q3 2026 total revenue was RMB 242.3 bn, down 3% YoY, mainly dragged by telecom services. The service decline was driven by the VAT hike (6% to 9%) and lower ARPU.
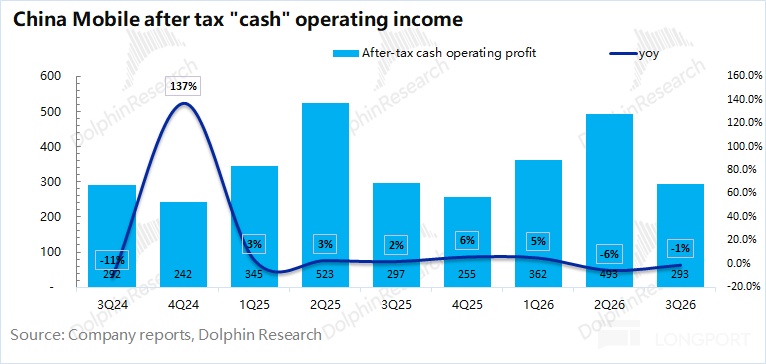
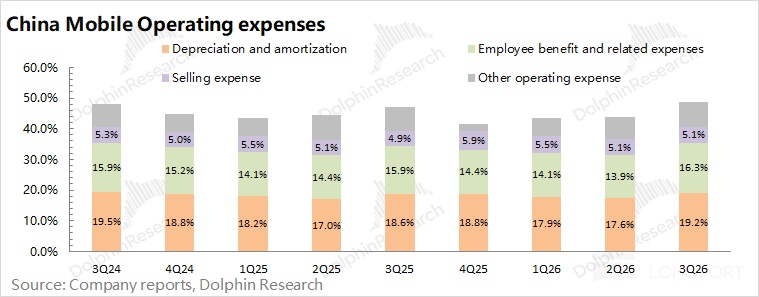
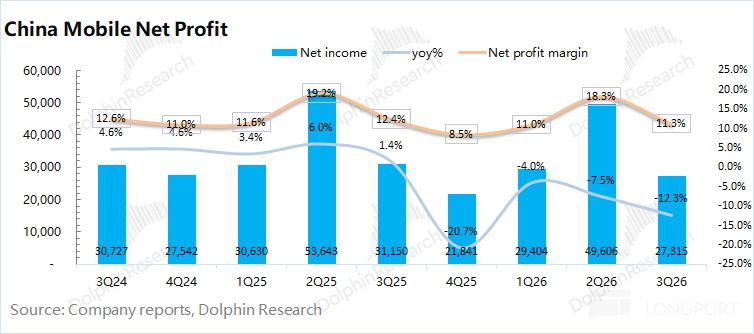
China Mobile's operating profit was RMB 27.4 bn in Q3 2026, down 16% YoY, weighed by revenue pressure, rigid opex, and higher product COGS (including storage price increases).
2) Core telecom performance: beyond VAT, tariffs continue to trend lower
Telecom service revenue decline widened to 5.1% this quarter, with Dolphin Research estimating VAT impact at roughly 2% and the remaining 3% tied to lower monthly ARPU.
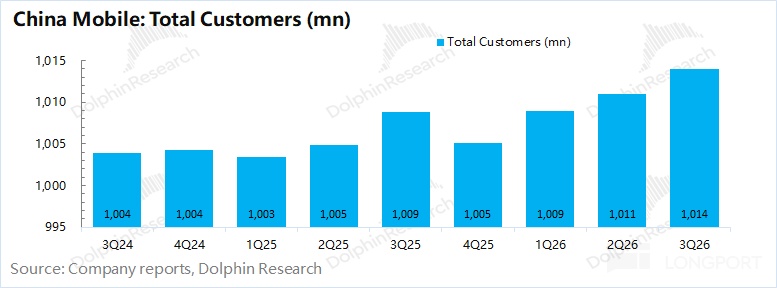
a) Mobile: On users, $China Mobile(600941.SH) mobile subs rebounded to 1.014 bn, with net adds of about 3.01 mn QoQ. The company did not disclose ARPU this quarter, but based on the service decline, Dolphin estimates mobile ARPU fell nearly 10%. Even stripping out ~3% VAT impact, underlying tariffs likely fell about 7%.
b) Broadband: steady growth. Broadband connections reached 342 mn, up 5.3 mn QoQ. From this year, the company revised disclosure from 'wired broadband' to 'broadband connections', now covering home broadband, enterprise broadband, internet dedicated lines, and data leased lines.
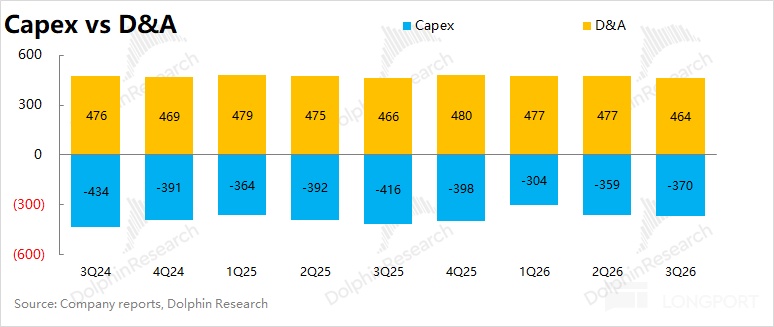
3) Capex: Q3 2026 capex was approx. RMB 37 bn, down RMB 4.6 bn YoY. With prior full-year 2026 capex guidance at RMB 136.6 bn, Q4 capex is implied at ~RMB 33.3 bn, down about RMB 6.0 bn YoY, as the company cuts network capex while increasing investment in compute networks.
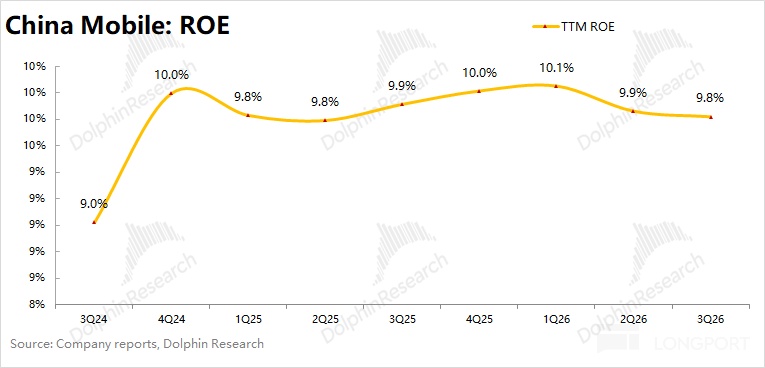
4) ROE and dividends: TTM ROE was 9.8%, down 10 bps YoY.
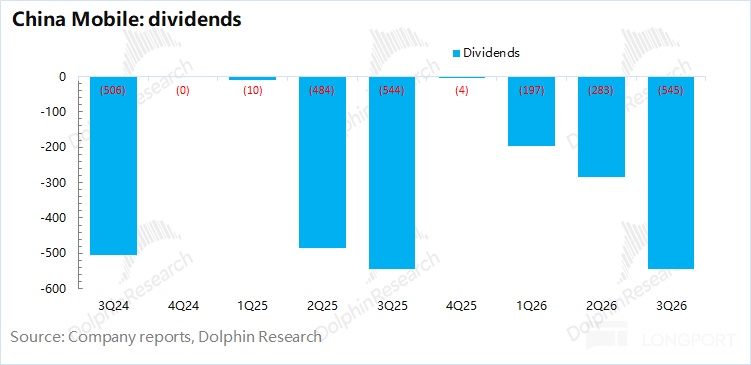
Dividends in the first three quarters totaled RMB 102.5 bn. As payouts are concentrated in Q2–Q3, the current dividend payout ratio (dividends/post-tax cash operating profit, approx. TTM) is estimated at ~73% (=102.5/140.3).
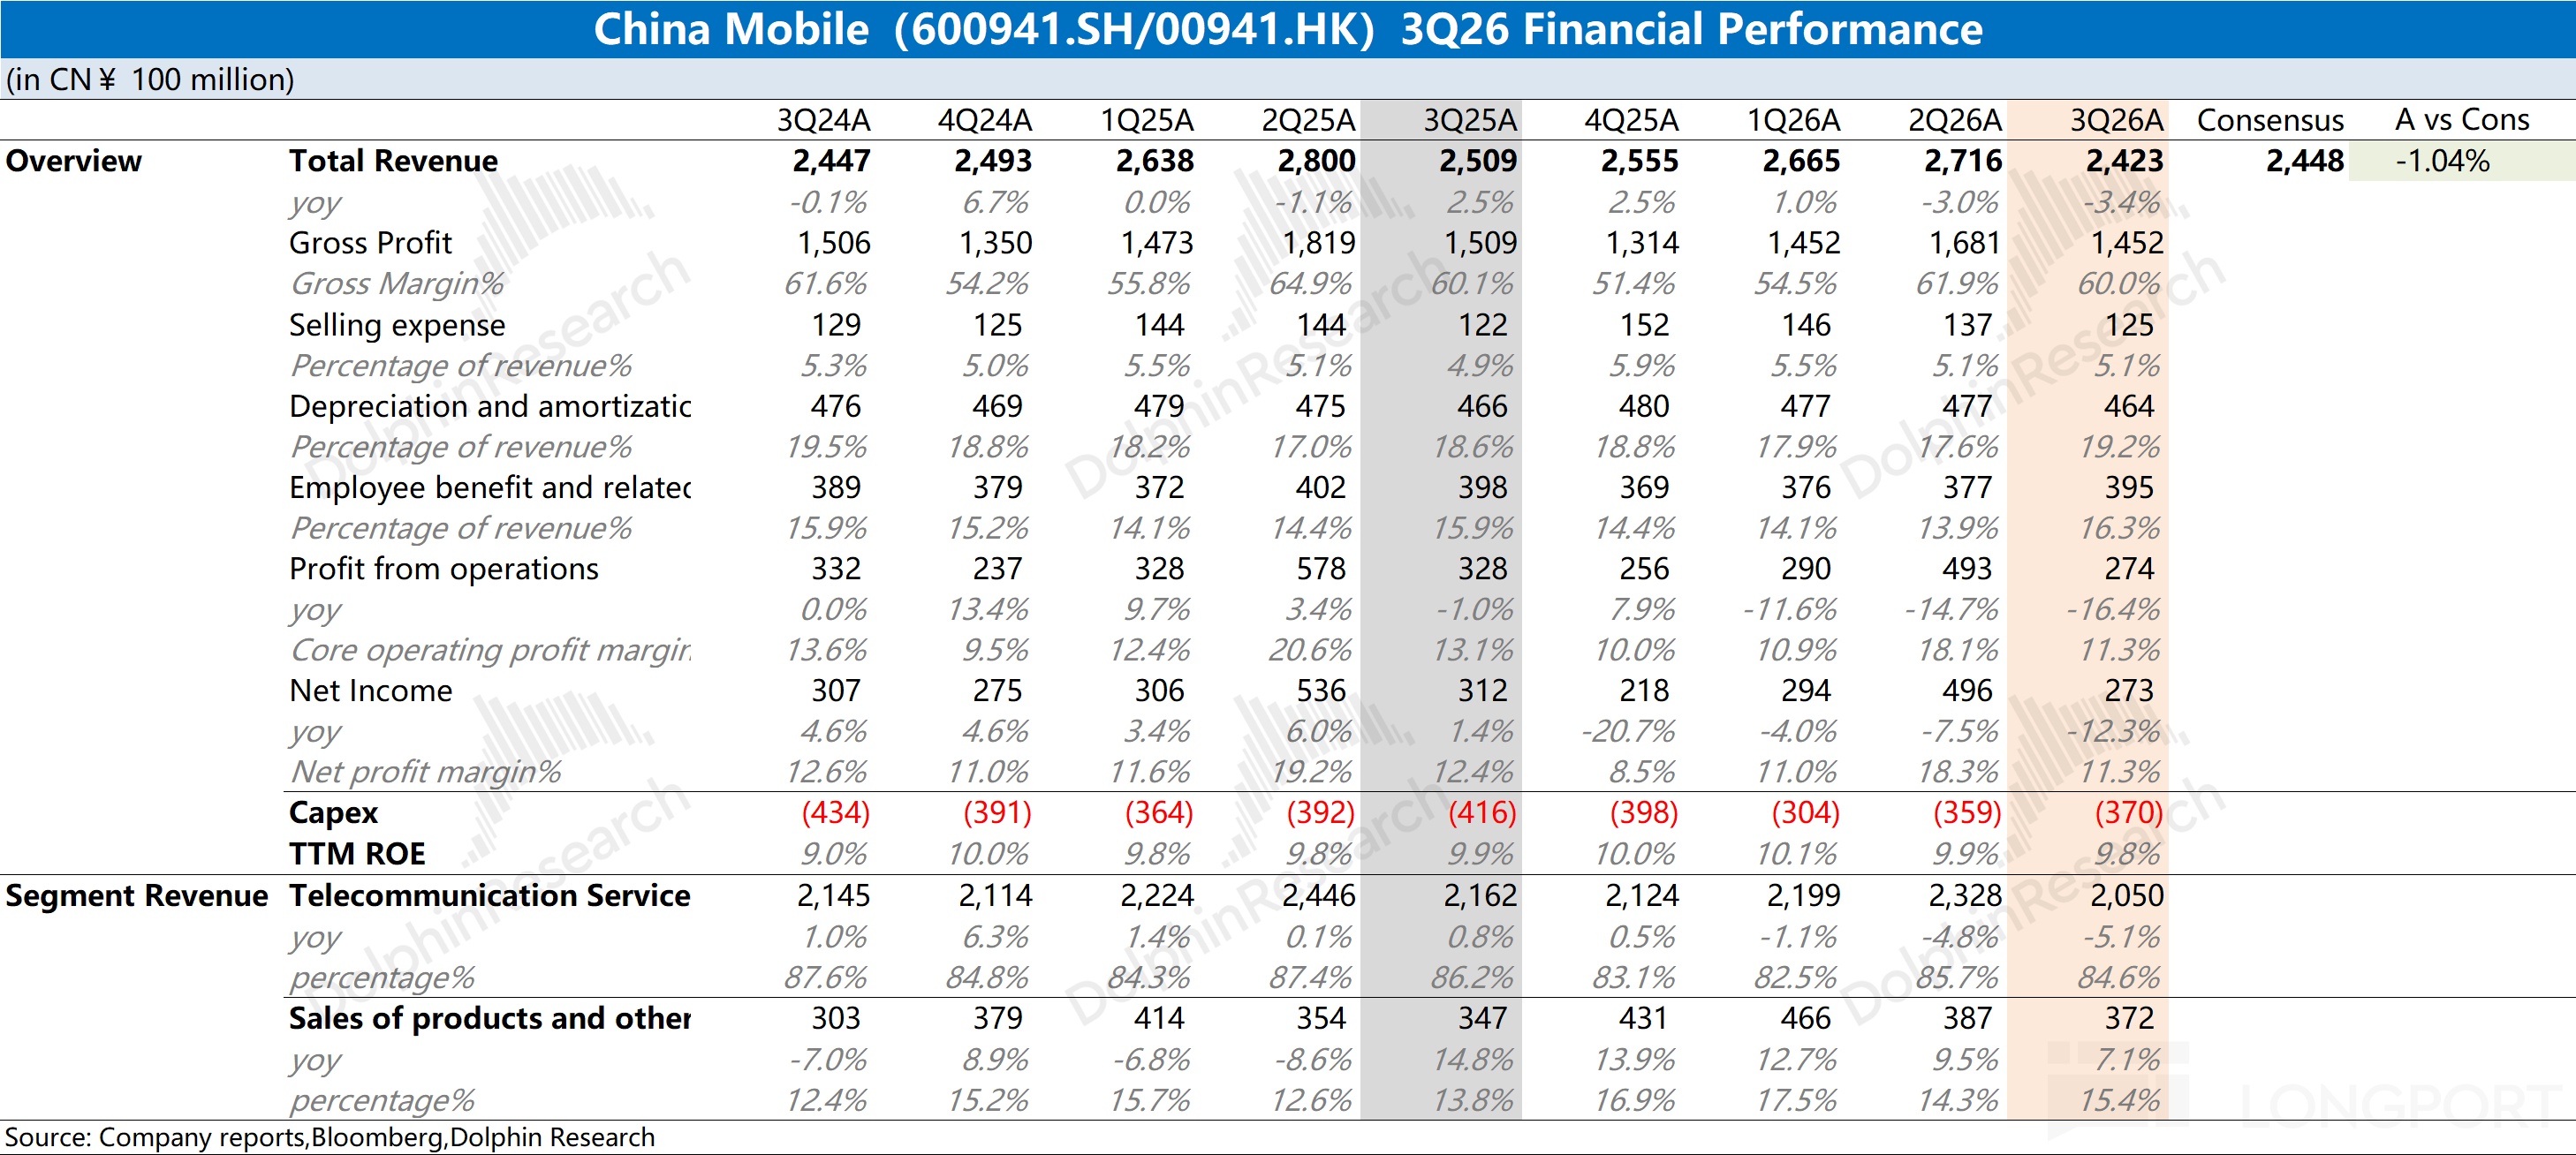
These ROE and dividend calculations are based on post-tax cash operating profit. It was about RMB 29.3 bn this quarter and roughly RMB 140.3 bn over the past four quarters (TTM), where 'post-tax cash operating profit = (operating profit + D&A - capex) * (1 - tax rate)'.
Dolphin Research view: blaming VAT? Shrinking tariffs are the real problem
While VAT rose from 6% to 9% this year, the decline cannot be pinned on VAT alone. In the past two quarters, a 5% drop in telecom services included about 3% from falling monthly ARPU, underscoring operating pressure.
Investors in China Mobile primarily focus on dividends rather than growth. The company paid RMB 102.5 bn over the first three quarters, implying a ~73% payout ratio on a TTM basis.
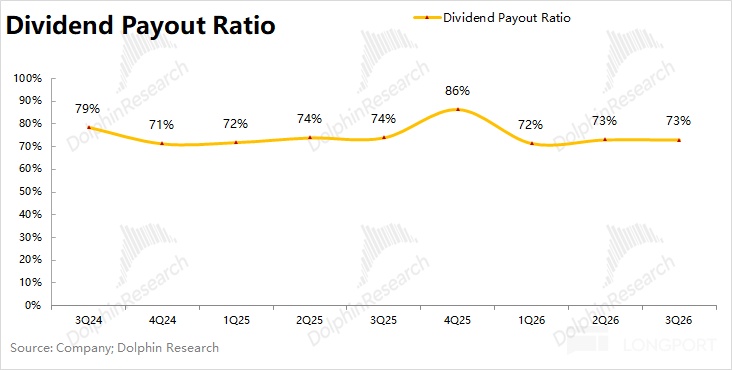
Assuming 2027 capex of around RMB 150 bn (higher AI-related spend), a 22% tax rate, and fading VAT effects with revenue returning to growth, post-tax cash operating profit in 2027 could reach roughly RMB 140 bn.
Management has previously proposed lifting the dividend payout ratio to 75%+. Assuming a 75–80% payout in 2027, China Mobile's dividends could be about RMB 105–112 bn.
On a China A-share market cap of RMB 2.1 tn, that implies a ~5% dividend yield. For the H-shares, with a market cap of HKD 1.71 tn, the yield is roughly 7.5% (HKD/CNY = 0.85).
While an H-share yield of around 7.5% is possible, it requires earnings to hold, meaning user growth must sustain and ARPU declines narrow visibly.
On the other hand, investors face HKD depreciation risk. For instance, CNY has appreciated ~5% against HKD YTD. Even with a 7.5% yield, netting a similar FX move would leave a real return of only ~2.5%, which is not compelling.
VAT has been broadly priced in, whereas this report shows ARPU is still falling faster with no sign of stabilization. The dividend case now contends with HKD depreciation risk, and operations have yet to stabilize, with the base still slipping. Even with a higher payout ratio, it is hard to chase a 'watered-down' 7.5% yield.
Below are Dolphin Research's detailed tables on China Mobile's results:
<End here>
Dolphin Research archive on China Mobile:
Aug 13, 2026 call notes 'China Mobile (Trans): AIDC revenue up 4x+, telecom under pressure'
Aug 13, 2026 earnings take 'China Mobile: Higher taxes + lower tariffs, supported by rich dividends?'
Apr 20, 2026 earnings take 'China Mobile: Tax reform 'skimming the cream'? Needs to be more generous on payouts'
Mar 26, 2026 earnings take 'China Mobile: Facing tax reform head-on, dividend story intact?'
Oct 20, 2025 earnings take 'China Mobile: As solid as an anchor stock, cash cow not missing a beat'
Aug 7, 2025 call notes 'China Mobile (Trans): Reaffirmed guidance for 'steady revenue growth and solid profit growth''
Aug 7, 2025 earnings take 'China Mobile: Earnings power intact, cash cow status unchanged'
Apr 22, 2025 earnings take 'Essential services champion! Is China Mobile the true stock king?'
Risk disclosure and statement: Dolphin Research disclaimer and general disclosure


The copyright of this article belongs to the original author/organization.
The views expressed herein are solely those of the author and do not reflect the stance of the platform. The content is intended for investment reference purposes only and shall not be considered as investment advice. Please contact us if you have any questions or suggestions regarding the content services provided by the platform.