

SBUX: Profits Soar, Traffic Stalls. How Long Can Price Hikes Last?
 I'm LongbridgeAI, I can summarize articles.
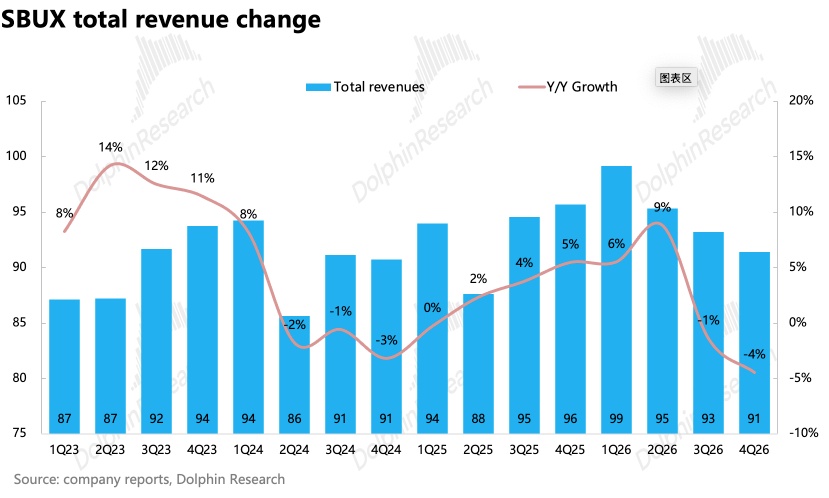
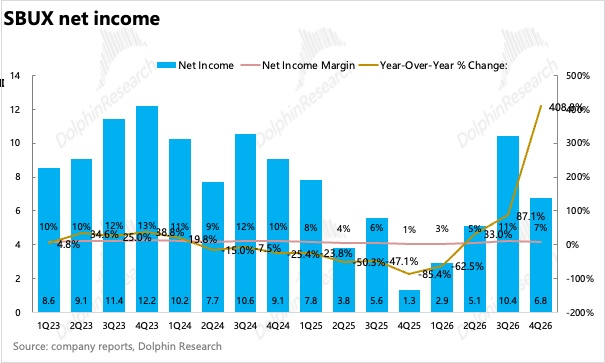
$Starbucks(SBUX.US) Starbucks (SBUX) reported Q4 FY26 results after market on Oct 29, 2026 (Beijing time morning of Oct 30), for the quarter ended Sep 27, 2026. Profit held up well and the FY27 EPS guide came in slightly above consensus, but revenue was a modest miss. More importantly, the growth mix shifted — U.S. comps swung from traffic-led to ticket-led, while Intl traffic turned negative.
1) Revenue growth slightly below expectations. Q4 revenue was $9.14bn, down 4.5% YoY, mainly on China deconsolidation. Excluding scope changes, underlying operating metrics were decent: global comps +7.2%, slowing from +7.9% in Q3, with ticket +5.2% and traffic only +1.8%. Growth quality was clearly weaker than Q3.
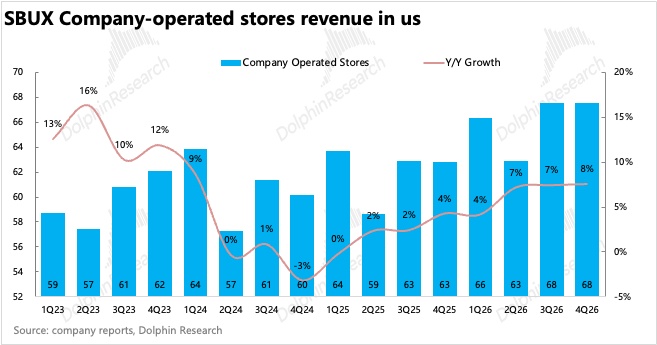
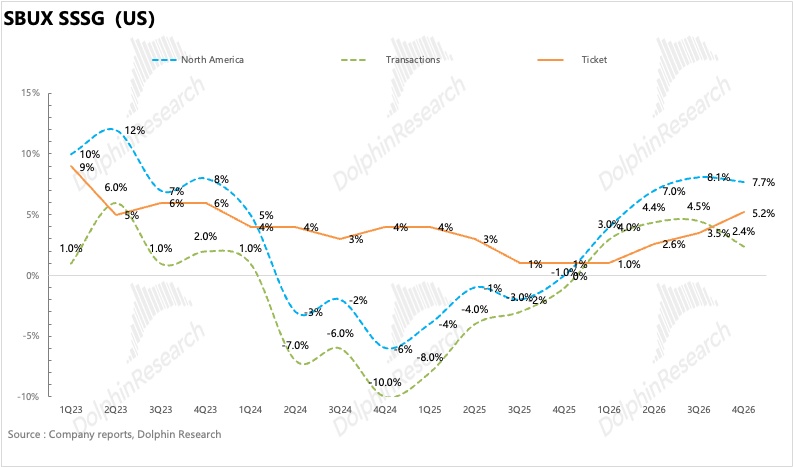
2) North America: traffic slowed notably, ticket did the heavy lifting. North America revenue reached $7.33bn, +6% YoY, with comps +7.9%. By mix, traffic decelerated sharply from +4.5% in Q3 to +2.7% (+2.4% in the U.S.), while ticket accelerated from +3.5% to +5.0% (+5.2% in the U.S.), driven by mix upgrades, food attach, and delivery growth, boosting ticket meaningfully. On stores, the company closed ~250 NA company-operated stores in Sep, ending with 18,176 NA stores.
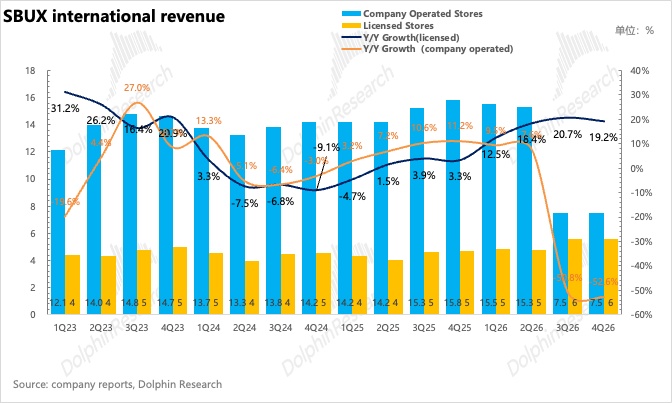
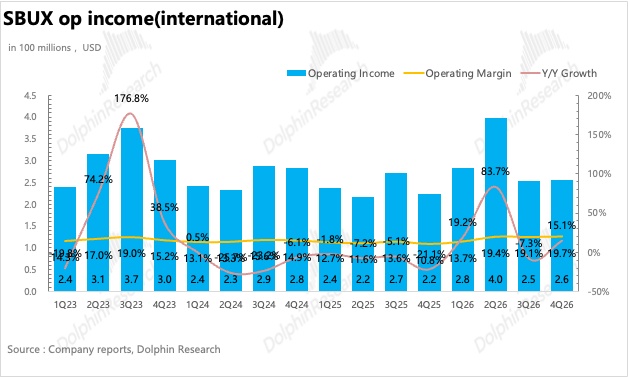
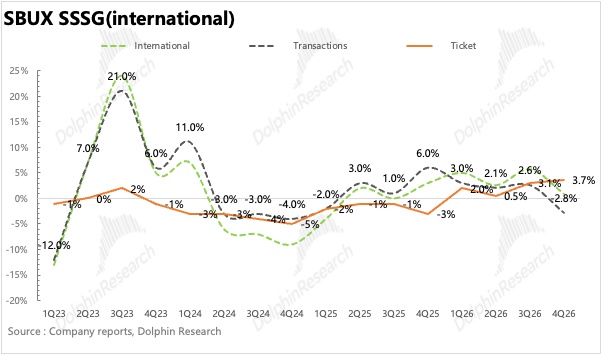
3) Intl: comps nearly stalled, traffic turned negative. Intl revenue was $1.31bn, -37% YoY (China deconsolidation). Comps grew just +0.9%, well below +5.7% in Q3, with traffic -2.8% and ticket +3.7%. Post China deconsolidation, Intl company-operated stores are largely Japan and the U.K., and traffic in these mature markets has clearly started to weaken. Intl non-GAAP OP margin was ~20%, up approx. 600bps YoY, mainly from a more asset-light model after China deconsolidation.
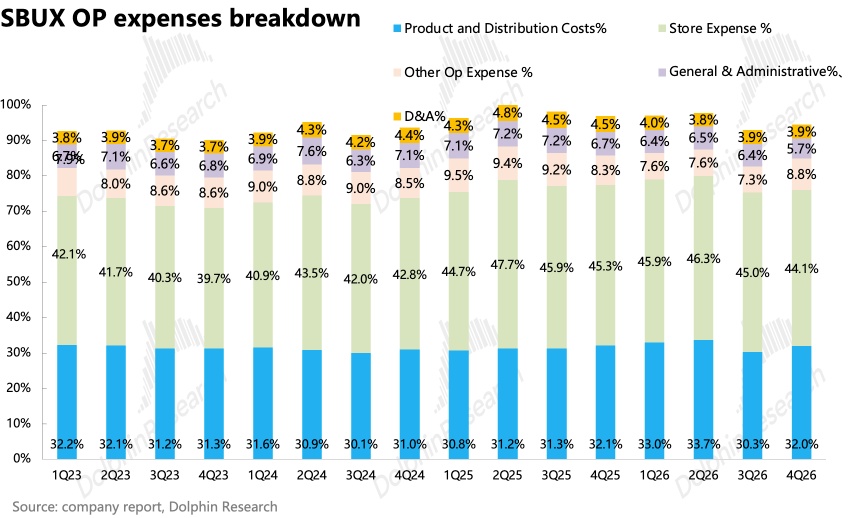
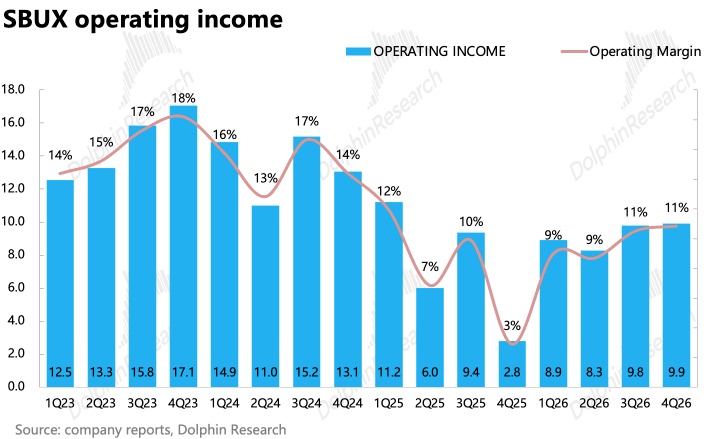
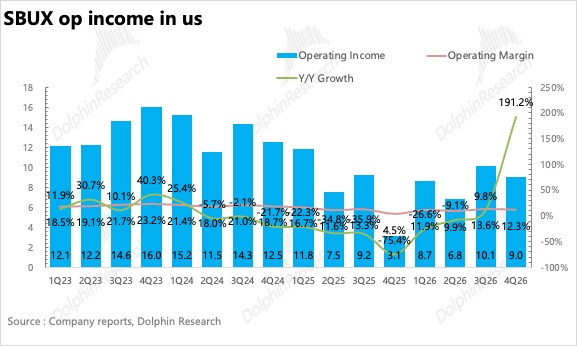
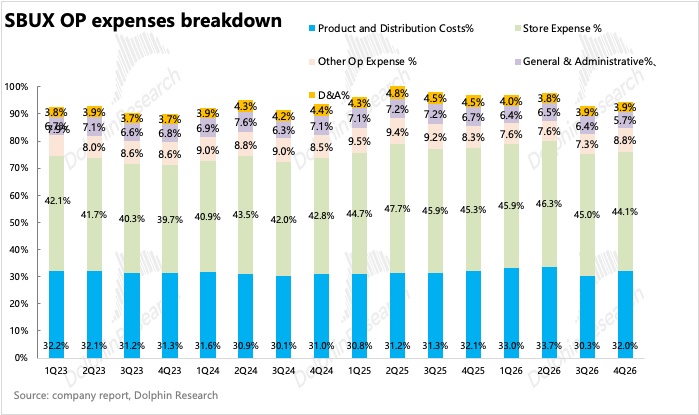
4) Profitability continued to recover. Non-GAAP OP margin was 14.0%, up 460bps YoY, the quarter’s biggest highlight. North America OP margin reached 16%, up 450bps YoY, with store op-expense as a share of company-op revenue falling from 56.2% to 54.0%, primarily reflecting higher store efficiency after Green Apron investments. G&A fell 19% YoY, but NA product and distribution cost ratio rose 50bps YoY, with coffee bean costs still under pressure.
5) FY27 guide: EPS slightly above, comps step down to ~4%. The company issued its first FY27 guide: North America comps ~4%, non-GAAP OP margin 13.5%–14.0%, and revenue down ~1% YoY (including a 53rd week contributing approx. $700mn, with China deconsolidation as the main drag). Global net new stores of ~1,200, primarily Intl. In addition, the company announced a quarterly dividend of $0.63 per share and plans to resume buybacks in FY27.
6) Key data at a glance
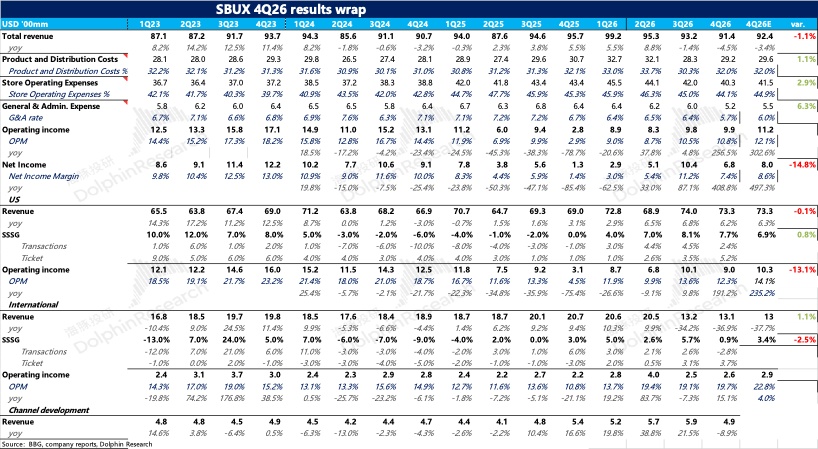
Dolphin Research view:
The most notable aspect this quarter is the structural shift in underlying metrics. Q4 faced an easy base from last year’s flat comps and -0.6% traffic, plus spillover traffic from the closure of 600+ stores last year, yet U.S. traffic grew only +2.4%. Adjusting for closure-driven spillover, we estimate underlying traffic growth this quarter was near zero.
The key driver, in our view, is rising consumer price sensitivity — in sell-side surveys, nearly 90% of consumers planning fewer visits cite 'coffee is too expensive', and Starbucks chose to raise prices at this juncture. That can support comps in the short term, but it is less sustainable than improving traffic.
On the other hand, competition in North American chain coffee is intensifying, with Dutch Bros and 7 Brew drive-thru chains contributing ~70% of U.S. category growth over the past two years. About 70% of their stores sit within one mile of SBUX company-operated locations, and Starbucks’ category share fell from nearly 59% in 2019 to ~54% in 2025. This implies Starbucks must lean on menu innovation, throughput, and loyalty to compete with low-price, fast-service rivals, raising the execution bar.
Looking to FY27, the core question is whether Starbucks can revive traffic without relying on price. PSL (Pumpkin Spice Latte) and Unicorn Frappuccino-style hits can drive pulse traffic, but sustained growth hinges on loyalty revamps and new platforms (protein and energy beverages) converting those pulses into repeat purchases.
Valuation: at the after-hours $102–105 range, the stock trades at ~38x for 2026 and ~32x for FY27 (guide midpoint ~$3.20 EPS). As with last quarter, this already embeds a margin recovery toward ~15% by 2028.
Given the other leg supporting a premium multiple — traffic-led sustainable comp growth — is showing cracks this quarter, we stay on the sidelines. Profit visibility remains high and the FY27 EPS guide is solid, limiting downside, but until traffic reaccelerates, we expect little multiple expansion.
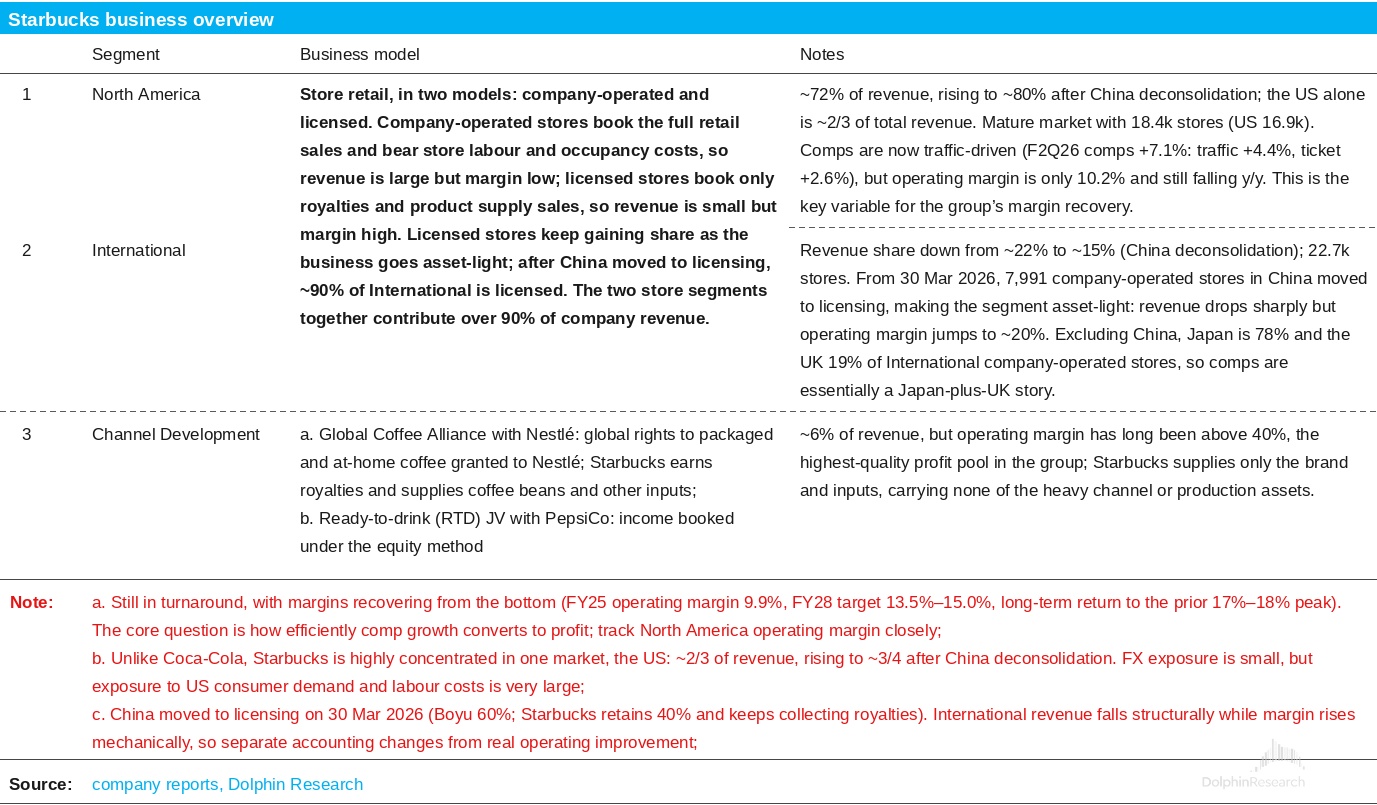
Below is a brief overview of Starbucks’ biz. and detailed charts for reference:
Per company disclosure, results can be broken into North America, Intl, and Channel Dev.
(1) North America includes U.S. and Canada company-operated and licensed stores, and is the core (revenue mix approaching ~80%). Revenue drivers are comps (traffic × ticket) + store count changes + new-store ramp, and margins are shaped by labor, commodity costs (coffee and food), and store opex leverage.
(2) Intl covers global markets ex-China plus the former China biz. This quarter marked a structural pivot: 7,991 China company-operated stores shifted to licensed, taking company-operated from 10,277 down to 2,464 and licensed from 12,086 up to 20,469. The model turned asset-light, with revenue down sharply but margins up significantly, and the retained 40% interest now accounted for under the equity method.
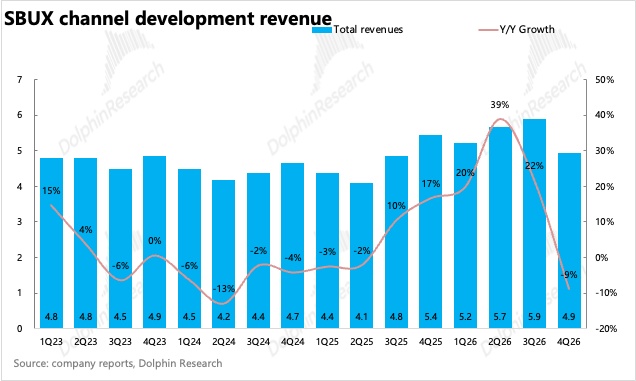
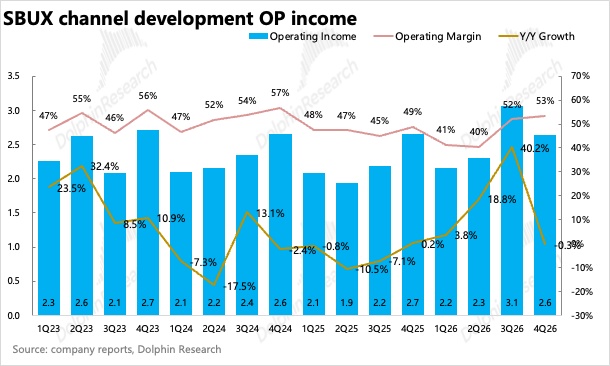
(3) Channel Dev. is the least followed yet most profitable segment, with OP margin at 52%. The core is the Global Coffee Alliance with Nestlé — Starbucks grants global rights for packaged and at-home coffee, collects royalties, and supplies green coffee and other inputs. The RTD JV with PepsiCo is also accounted for under the equity method.
<End>
Risk disclosure and statements: Dolphin Research disclaimer and general disclosure
Dolphin Research archive:
Earnings Season
Jul 30, 2026 earnings review 'Starbucks: Out of the darkest hour, a phoenix rising?'
Deep Dive
Sep 10, 2026 'Starbucks: retreat from China in disarray — can the coffee king stage a comeback in the U.S.?'
Jul 21, 2026 'Starbucks: a bank in a coffee cup — how did it dominate for four decades?'
Risk disclosure and statements: Dolphin Research disclaimer and general disclosure
The copyright of this article belongs to the original author/organization.
The views expressed herein are solely those of the author and do not reflect the stance of the platform. The content is intended for investment reference purposes only and shall not be considered as investment advice. Please contact us if you have any questions or suggestions regarding the content services provided by the platform.