

Kweichow Moutai: Past the trough; needs one last push to stand up
 I'm LongbridgeAI, I can summarize articles.
On Oct 30 Beijing time, Kweichow Moutai (600519.SH) reported Q3 2026 results. Revenue and profit returned to positive growth, broadly in line with market expectations. See: $Moutai(600519.SH)
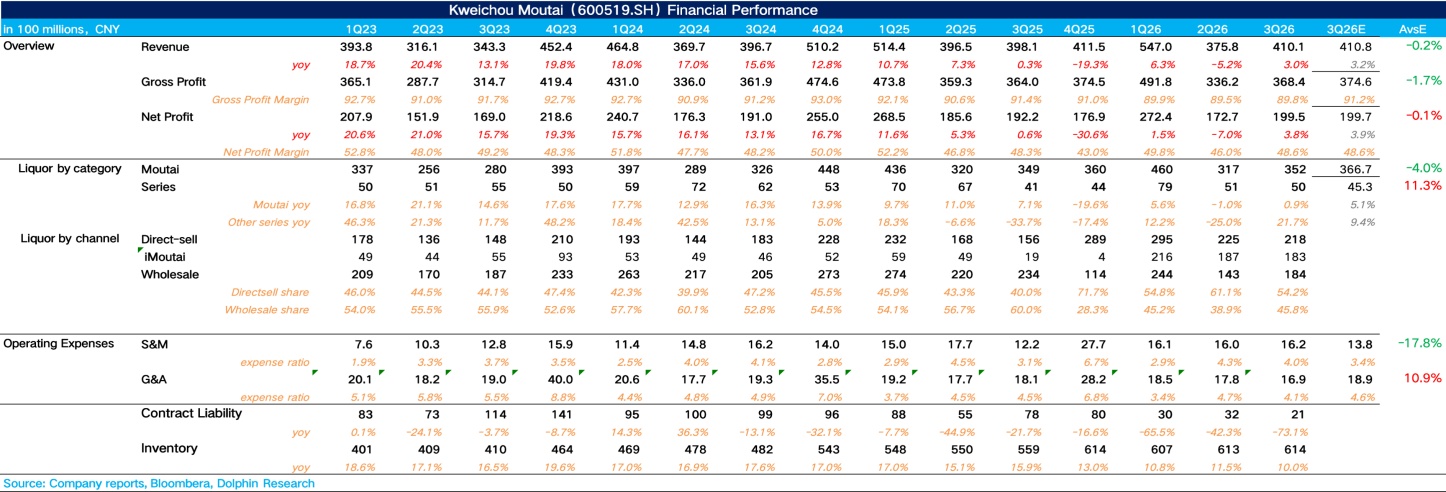
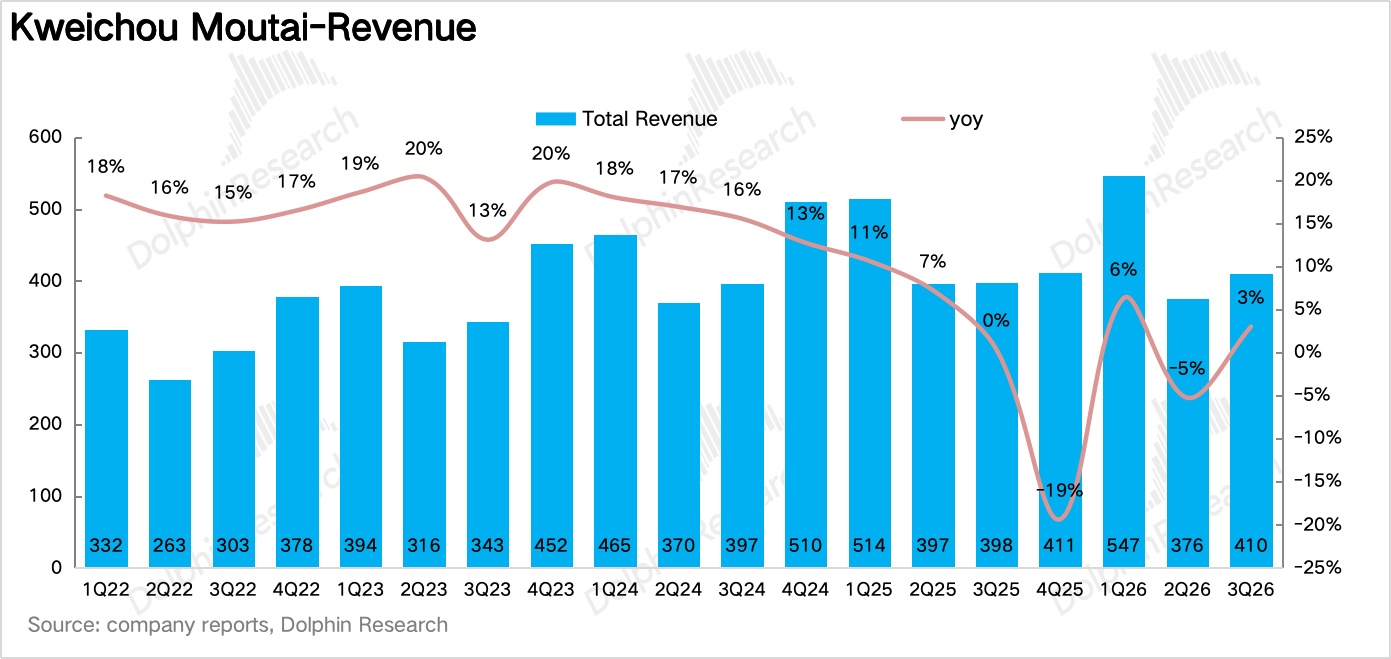
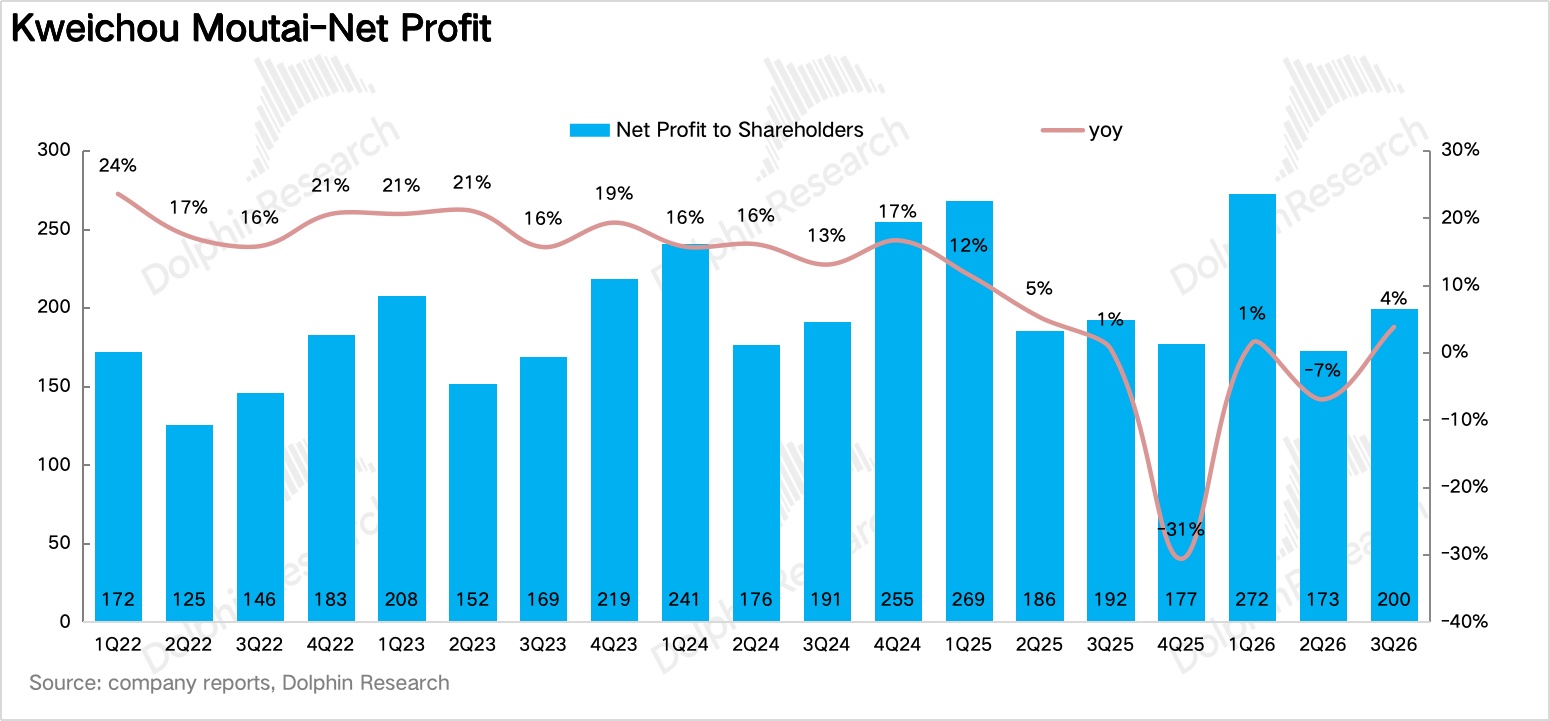
1) Revenue and profit back to growth. Moutai delivered revenue of RMB 41.0bn in Q3, up 3.0% YoY, reversing the decline in Q2. Net profit attributable to shareholders was RMB 19.95bn, up 3.8% YoY, slightly outpacing the topline.
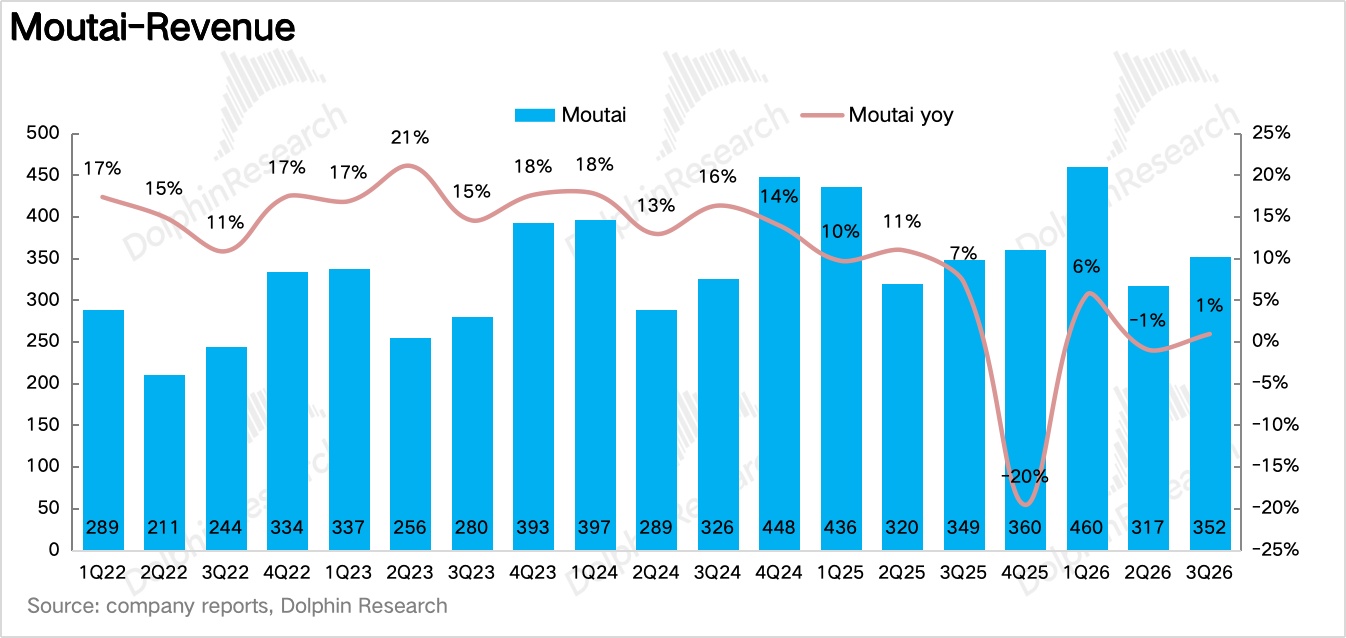
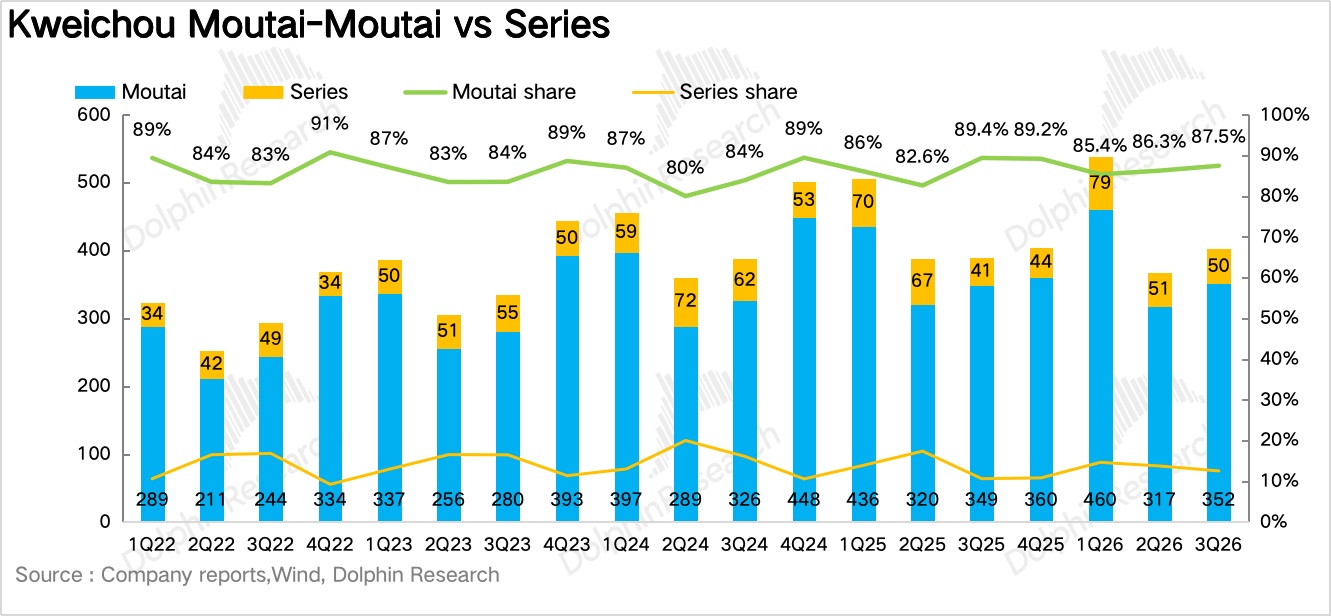
2) Core Moutai liquor remains a weak growth driver; price-hike dividends not yet visible on the P&L. By product, core Moutai liquor revenue was RMB 35.2bn, up only 0.8% YoY. Q3 was the first full quarter after the Feitian contract price was raised to RMB 1,369, a 17% YoY increase, yet revenue barely grew. Dolphin Research estimates two main reasons: first, Feitian quotas were front-loaded in H1, leaving fewer volumes YoY to release in H2; second, price cuts of over 30% on non-standard SKUs early in the year are still weighing on blended ASPs for Moutai liquor.
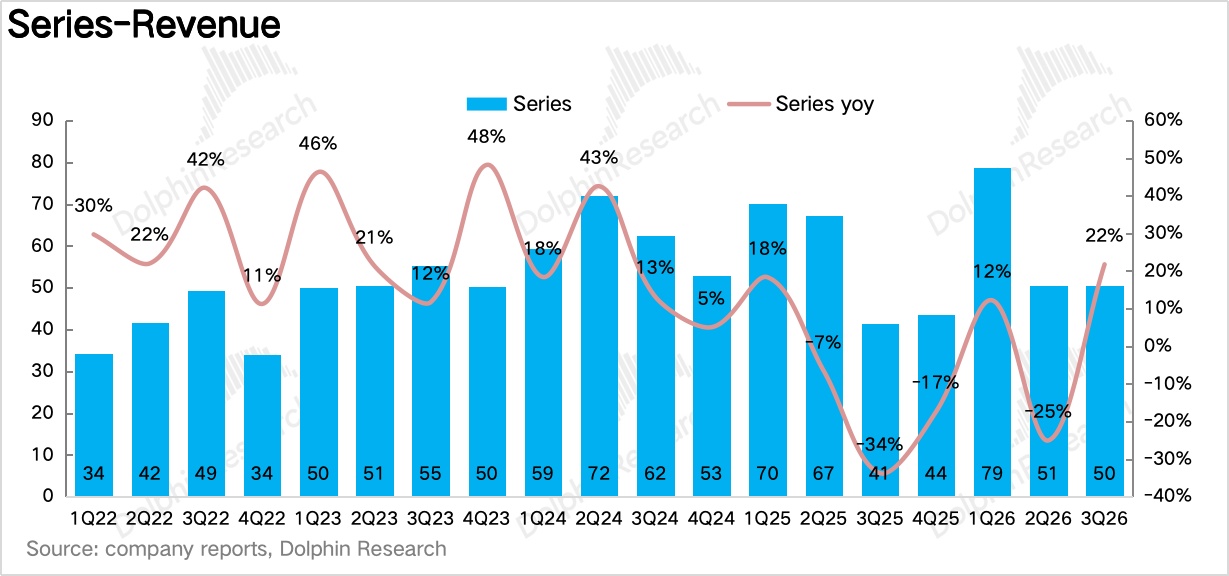
3) Series products rebounded sharply. Series liquor revenue reached RMB 5.0bn, +22% YoY, a major reversal from -25% in Q2. On one hand, last year's low base in Q3 (series liquor down 34%) helped; on the other, after deep destocking in prior quarters, channel inventory returned to low levels and restocking demand was released. That said, domestic distributors still fell by a net 68 in Q3, and the company indicated most of the changes were among series liquor distributors, suggesting channel restructuring is not yet over.
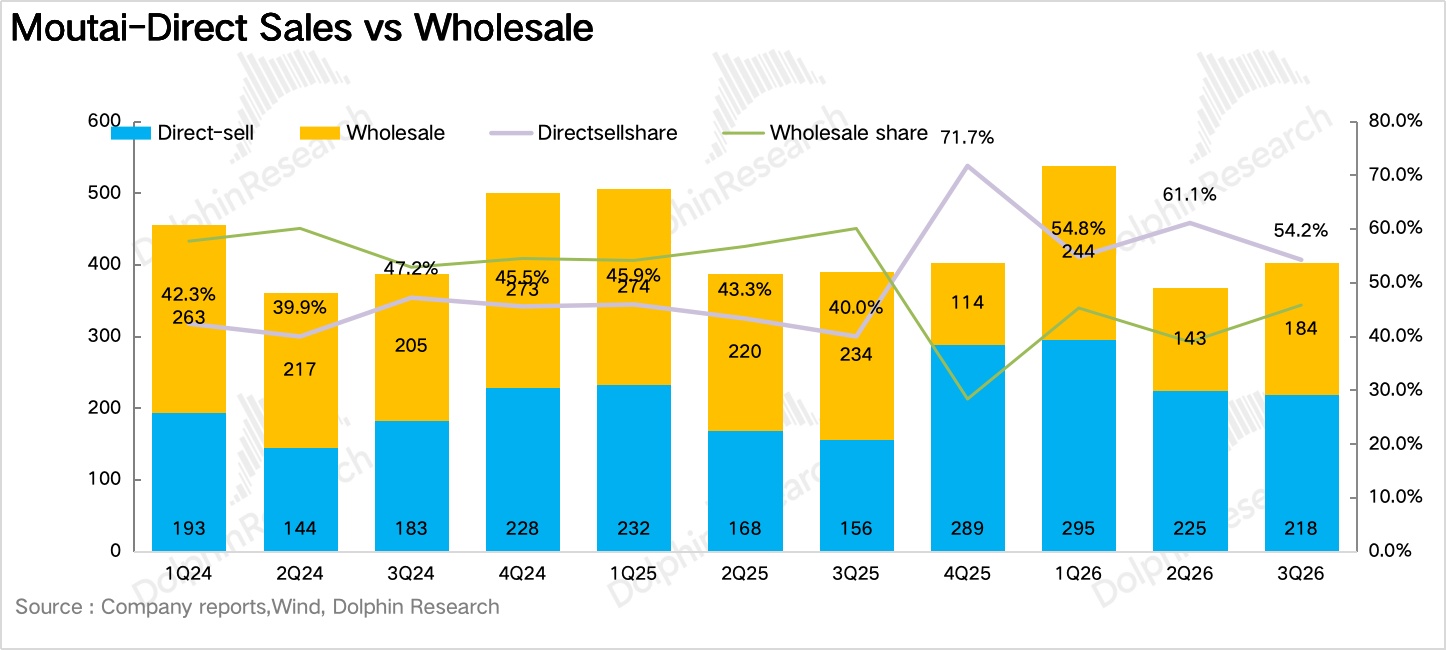
4) Direct-sales mix fell QoQ as wholesale recovered post price hikes. By channel, direct sales revenue was ~RMB 21.8bn in Q3, +40% YoY; within that, iMoutai was RMB 18.3bn, roughly flat vs. Q2. Wholesale revenue was RMB 18.5bn, still down 21% YoY, but the decline narrowed vs. Q2. Direct sales mix fell from 61% in Q2 to ~54% in Q3, indicating that with higher contract prices and Mid-Autumn/National Day stocking, traditional distributors showed renewed willingness to remit payments.
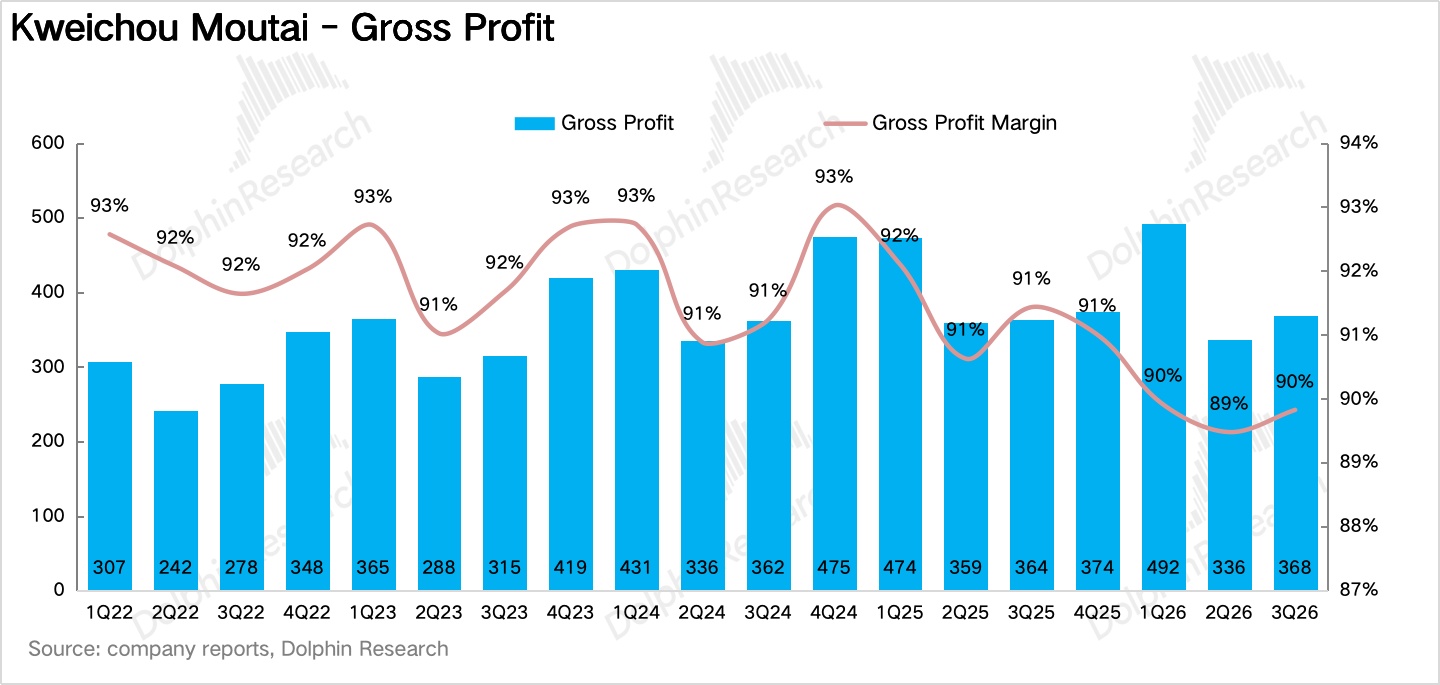
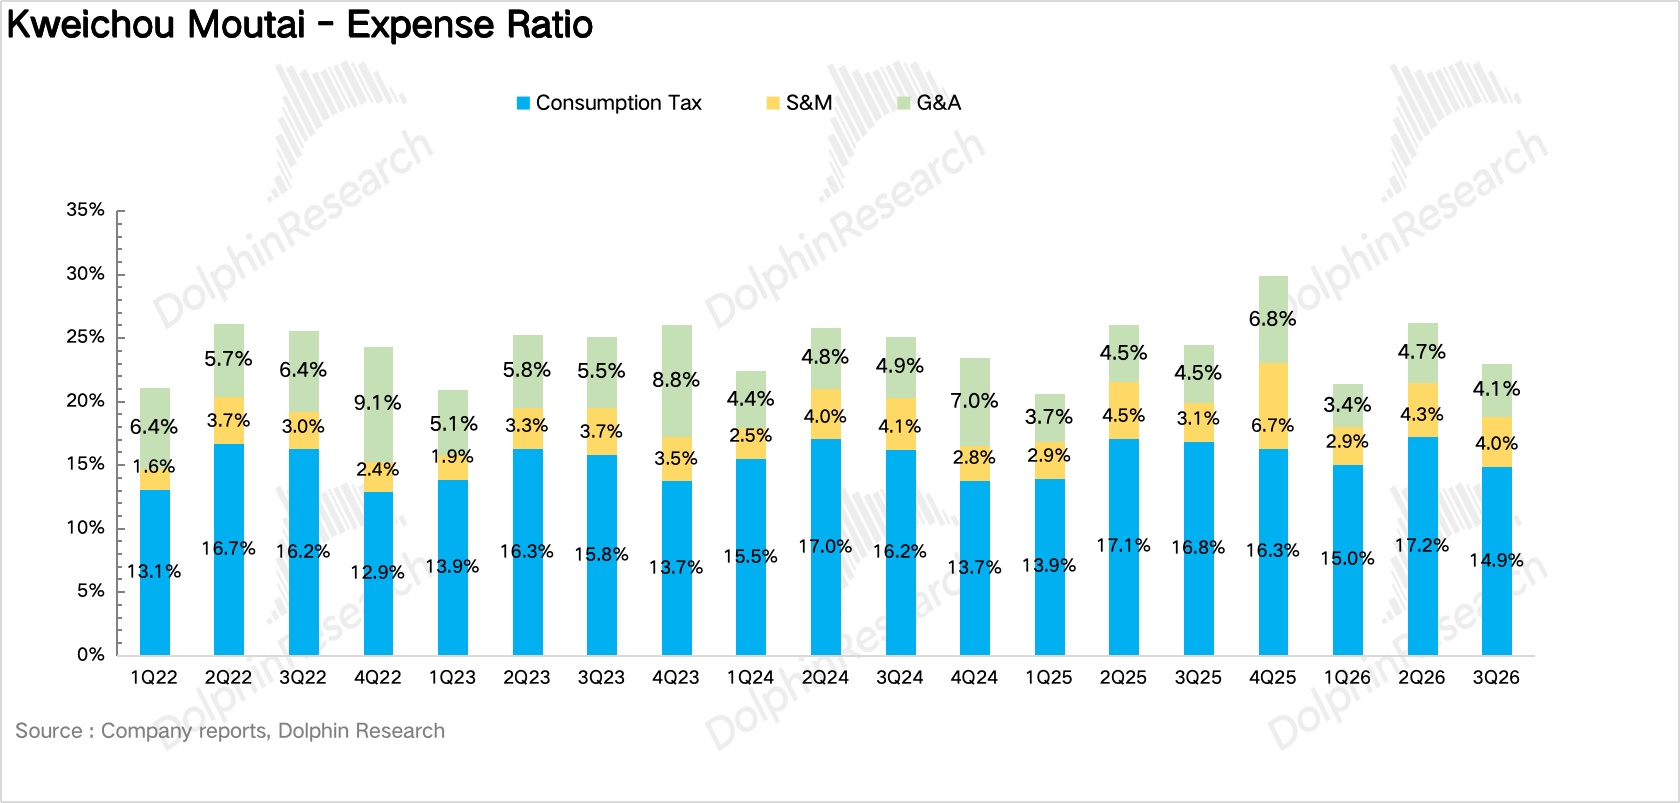
5) GPM under pressure, but NPM edged up. Dragged by mix due to non-standard SKU price cuts, Q3 GPM was 89.8%, down 1.6pct YoY (160bps). Taxes and surcharges as a percentage of revenue declined (helped by higher direct-sales mix), and admin expenses continued to compress. As a result, Q3 NPM was ~49.5%, up 0.3pct YoY (30bps). The current dividend and buyback yield is ~4%.
6) Financial highlights at a glance
Overall view from Dolphin Research:
The market expected that as the first full quarter after Feitian's contract price rose to RMB 1,369 — contract price up 17% YoY and iMoutai retail up 9% YoY — Q3 revenue would turn positive with core Moutai liquor acting as the main growth driver. In reality, although total revenue turned positive, growth was driven by series products still in cleanup, while core Moutai liquor with the largest price hike saw almost no growth. Based on this, Dolphin Research discusses several questions behind the print that the market cares about:
a) Where did the nearly 20% cumulative price-hike dividend on Feitian go this year?
Dolphin Research previously noted that raising the Feitian contract price from RMB 1,169 to RMB 1,369, even with flat volume, should add low-teens growth to core Moutai liquor. Actual growth was just 0.8%. We believe one factor is reduced H2 Feitian release volumes. Channel checks suggest shipments were faster than usual in H1, pulling forward annual quotas and lowering H2 volumes YoY, so 'higher price, lower volume' partially offset each other. Another factor is the lingering drag from non-standard SKUs: after shifting non-standard from distributor sales to iMoutai and consignment, prices fell by over 30%, and the ASP drag will only be fully absorbed on a YoY basis by Q1 next year. Therefore, meaningful P&L elasticity from price hikes should emerge from Q2 2027 onward, once Feitian release pacing normalizes.
b) What does the shift in channel mix mean as direct-sales share falls and wholesale recovers?
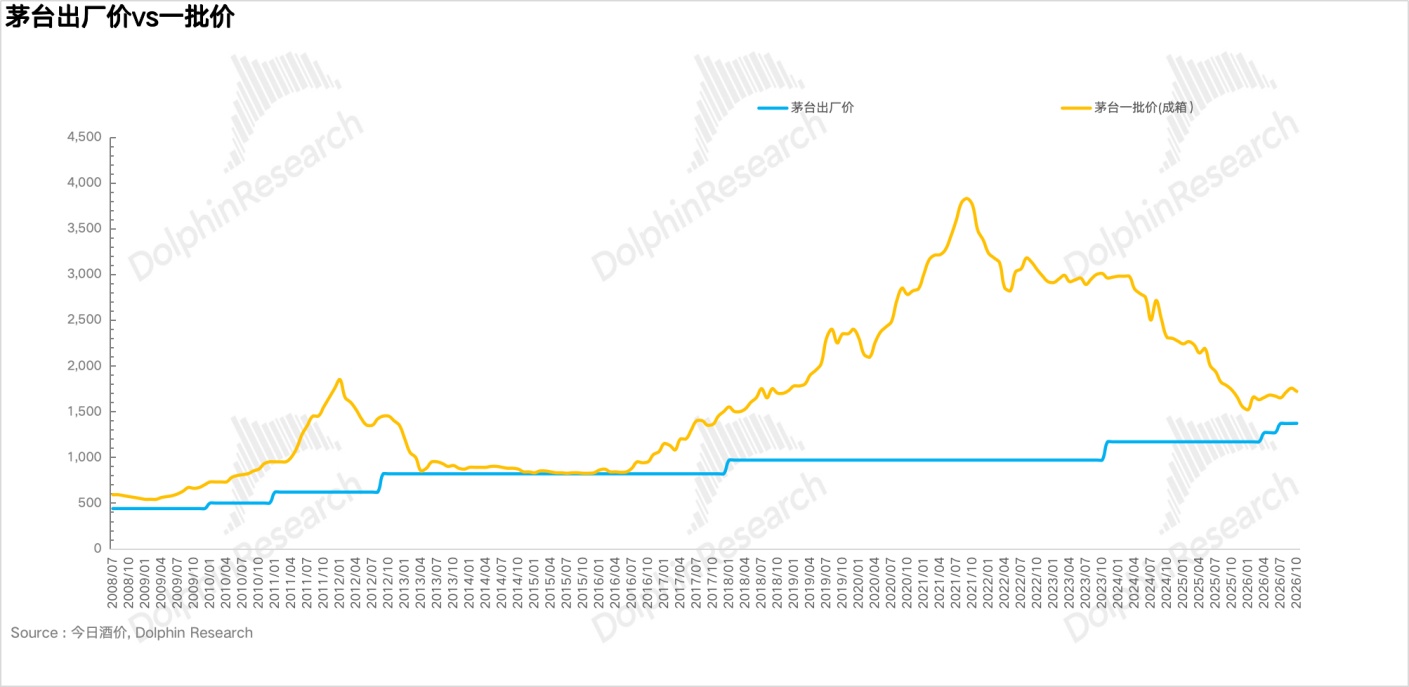
As analyzed, direct-sales share spiked to 61% in Q2 but fell to 54% in Q3, with iMoutai revenue flat QoQ and wholesale revenue up QoQ. Dolphin Research sees two implications: First, after contract price hikes and ahead of the holiday season, distributors' willingness to remit payments is recovering, indicating that with wholesale prices holding above RMB 1,700, channels have regained profitability.
Second, iMoutai's volume ramp is constrained by supply. Moutai liquor supply was largely set years ago, and H2 Feitian quotas shrank. Given iMoutai and distributors share the same volume pool, and distributors provide network coverage and price stabilization while iMoutai is the lowest-price anchor across channels, excessive allocation to iMoutai would pressure wholesale prices. Thus with total supply shrinking, iMoutai volumes are unlikely to keep growing rapidly.
This implies the phase of rapid direct-sales growth driven by iMoutai scaling is ending. Going forward, direct-sales growth should slow materially, and Moutai's growth will rely more on repairing the price system across channels.
c) With the 'reservoir' emptied, how long until an earnings inflection?
Contract liabilities were just RMB 2.08bn at Q3-end, down 73% YoY and at a multi-year low. This reflects higher direct-sales mix (iMoutai is recognized immediately, without prepayments) and the company no longer collecting large advance payments from distributors. It also means Q4 revenue will depend almost entirely on shipment and sell-through without a buffer to smooth quarterly results.
The good news is Q4's base is very low (revenue -19% and profit -30% last year), and the 2027 Lunar New Year arrives early (early Feb), so holiday stocking could partly shift into Q4. Dolphin Research still expects a high likelihood of double-digit growth in Q4 revenue and profit.
Where are we in Moutai's turnaround? Wholesale prices have stabilized — Feitian remains above RMB 1,700 after official price hikes, without retracement or inversion. Earnings turned positive in Q3, but the true inflection depends on the low-base Q4 and next year's holiday season.
Valuation. With RMB 64.5bn net profit attributable in the first three quarters and assuming Q4 grows ~12% YoY, 2026 full-year net profit attributable would be ~RMB 84.3bn, +~2% YoY. At a ~RMB 1.7tn market cap, that implies ~20x. Historically, in wholesale price up-cycles, the market typically assigns Moutai 25–30x PE; in down-cycles, valuation falls to the 18–20x range. The current multiple still sits in the down-cycle band, reflecting 'wholesale price bottoming and stabilizing,' but not yet pricing a return to earnings growth.
Therefore, Dolphin Research maintains a constructive view on Moutai's market-oriented reforms. On one hand, Q3 revenue and profit turned positive, wholesale prices held above RMB 1,700 after consecutive hikes, and distributors' payment willingness recovered, signaling a gradual fundamental inflection. On the other, mutual funds' allocation to Food & Beverage has fallen to historical lows, suggesting sentiment-driven positioning is already pessimistic enough. If Feitian wholesale prices continue to rise into the holiday season, and Q4 earnings acceleration on a low base is validated, the multiple could move back toward the up-cycle range around 25x, implying ~20%–25% upside from current levels.
Detailed financials from Kweichow Moutai
<End here>
Dolphin Research archive on 'Kweichow Moutai':
Earnings season
Apr 17, 2026: 'Kweichow Moutai: Don't Be Spooked by Earnings; Marketization Is the Real Trump Card!'
Oct 29, 2025 earnings take: 'Kweichow Moutai: Channels Shed Burdens, Await Cycle Turn'
Apr 29, 2025 earnings take: 'Kweichow Moutai: Non-standard on the Left, Series on the Right—Unfazed by Slower Feitian?'
Apr 3, 2025 earnings take: 'Moutai: Barely Passable—How to Restore a Fractured Myth?'
Oct 26, 2024 earnings take: 'Moutai: Can the Mainstay Still Prop Up A-shares' Backbone?'
Apr 3, 2024 earnings take: 'Anyone Can Falter—Only Moutai the 'Weeble''
Risk disclosures and disclaimer: Dolphin Research Disclaimer and General Disclosures
The copyright of this article belongs to the original author/organization.
The views expressed herein are solely those of the author and do not reflect the stance of the platform. The content is intended for investment reference purposes only and shall not be considered as investment advice. Please contact us if you have any questions or suggestions regarding the content services provided by the platform.