D
 +26
AWS builds its net by buying: who are Trn3's pick-and-shovel suppliers?
Among cloud players developing in-house AI chips, AWS is the outlier. It designs its own silicon. For networking, it buys rather than builds whenever it can.
+26
Among cloud players developing in-house AI chips, AWS is the outlier. It designs its own silicon. For networking, it buys rather than builds whenever it can.
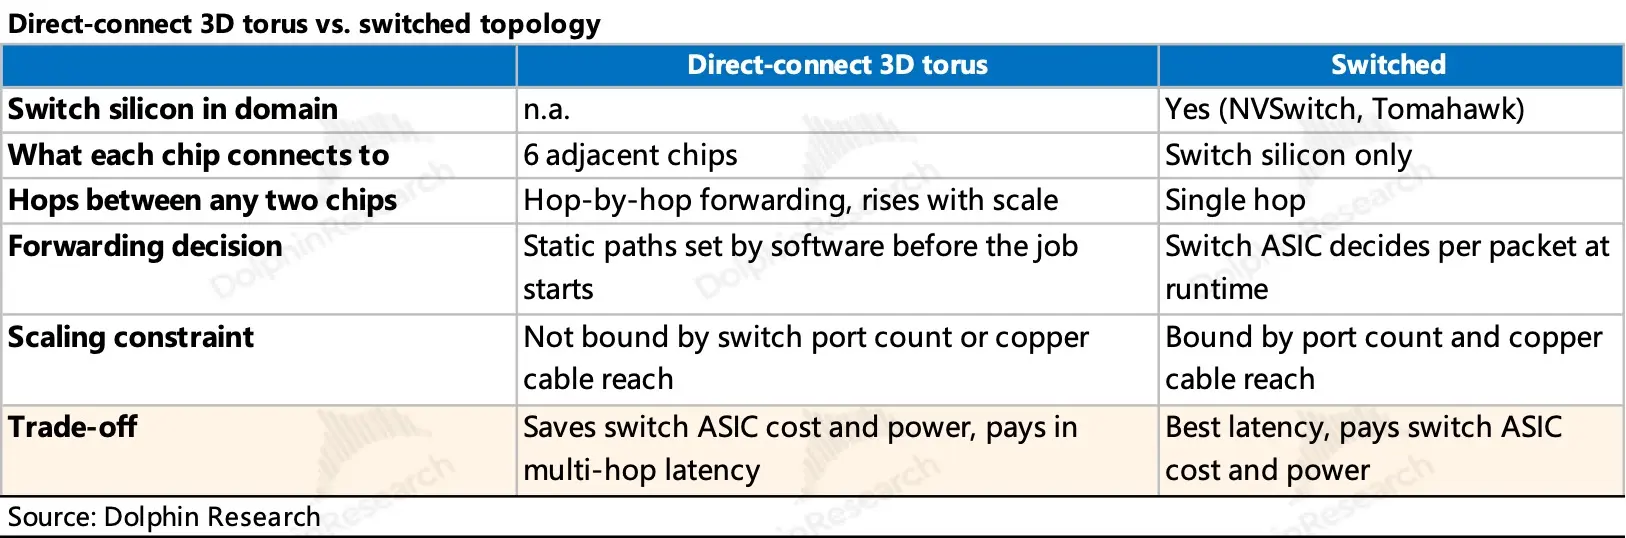
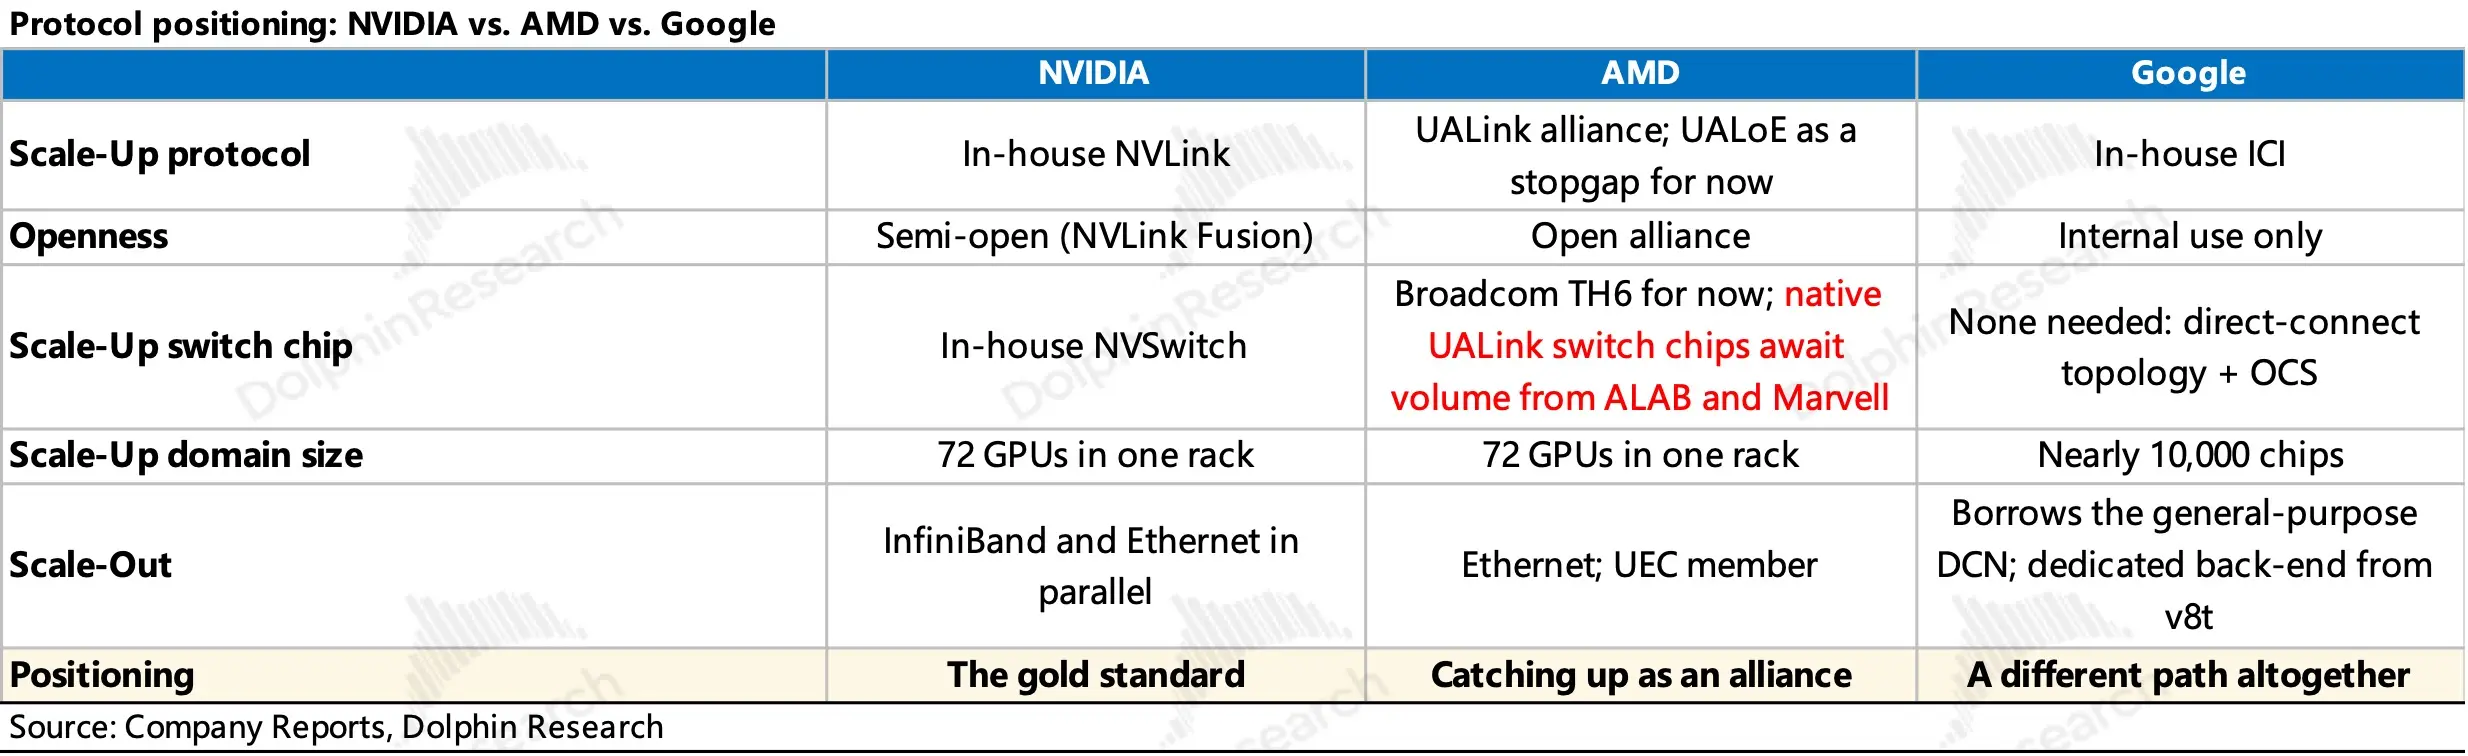
+26In our recent networking series, Dolphin Research reviewed 2D fat-tree switched fabrics. These are exemplified by Nvidia and AMD, while Google represents 3D torus direct-connect topologies.
$NVIDIA(NVDA.US) sets the industry benchmark. It develops the full stack in-house across hardware, protocols, and software, with tight HW/SW co-design delivering best-in-class performance. Its road map iterates quickly and in large leaps, prompting rapid shifts in supply-chain dynamics.$AMD(AMD.US) follows Nvidia but competes a generation behind. Helios largely copies the GB300 NVL72 networking architecture...
 +5
The bearish headline that OpenAI's ARR went from 70bn to 50bn triggered a global pullback in AI plays.
Dolphin Research offers a quick take on where expectations diverge.1) The 70bn vs 50bn gap mostly reflects definitional differences rather than a real shortfall. Many leading model vendors periodically disclose ARR, but methodology matters — gross vs net revenue, annualizing a 28-day avg x12 vs a single recent week x52, etc.
Disclosure timing matters too, e.g., whether it follows a blockbuster flagship launch or a promotion; without that context, cross-company comparisons are not apples-to-apples.Mega-caps are rolling out results, and $Amazon(AMZN.US) reported its Q2 2026 print after the U.S. close on Jul 31 Beijing time.
The results vindicate Dolphin Research’s call last quarter. It is Amazon’s turn to shine.1) AWS is taking off? YoY growth accelerated from 28% to 37%, with revenue at $42.2bn. Anthropic’s ARR surge has delivered tangible tailwinds to AWS.More importantly, unlike most cloud peers, AWS is seeing both faster top-line growth and faster margin expansion. Segment OPM expanded 170bps QoQ...Below is Dolphin Research's FY26Q2 earnings call Trans for $Amazon(AMZN.US). Key highlights from the release are as follows.
1) Q3 guidance: net sales of $197.0bn–$202.0bn. Operating income of $22.5bn–$26.5bn.The sequential slowdown in revenue growth from Q2 to Q3 is mainly due to two factors. First, Prime Day timing: in 2026 the event lands in Q2 across most major countries, including the U.S., whereas in 2025 it fell entirely in Q3...In Dolphin Research's earlier piece 'AMZN's AI Misfire: Can It Mount a Comeback?', we examined AWS's AI buildout from several angles.
From in-house chips and the Anthropic partnership to model performance, we saw a meaningful step-up in AMZN's end-to-end AI capabilities, with the gap vs. Alphabet clearly narrowing.Two questions still stand out for us. First, AI margins at cloud providers seem better than we had penciled in; second, they remain heavily dependent on their model partners...When OpenAI took off, Microsoft enjoyed the limelight. As Gemini gained traction, Google Cloud surged ahead.
That begs the question: with Anthropic now out in front, which cloud provider stands to benefit? In AI, whether in chip R&D or model development...Below is Dolphin Research's FY26Q1 earnings call Trans for $Amazon(AMZN.US).
For our earnings analysis, see 'Retail Steady, AI Breakthroughs: Is AMZN back in the top tier?'.
I. Core highlights recap — 1) Guidance: Q2 net sales of $194-199bn (FX headwind ~10bps); Q2 OP of $20-24bn...
$Amazon(AMZN.US) released its Q1 2026 results after the US market close on Apr 30 (Beijing time). It was an after-hours release.
Overall, AWS accelerated markedly, while the broader retail businesses posted steady gains. Both revenue and profit beat Bloomberg consensus.However, with the shares up over 30% from recent lows in recent weeks, the bar had already moved higher. From an expectations-gap perspective, there was little surprise.Specifically: 1) AWS accelerated as expected, with its competitive standing improving. On the key KPI, AWS revenue grew 28% YoY to $37.6bn...Is North America's power shortage a near- to mid-term supply-demand mismatch? Or a long-term structural issue?
---