D
 +35
From Sidekick to Star: How AI inference can rewrite NAND's destiny?
Storing KV cache is storing compute. SSDs are becoming 'token batteries'.
+35
Storing KV cache is storing compute. SSDs are becoming 'token batteries'.
+35In the prior piece, Dolphin Research examined the underlying tech to explain why AI's demand for memory capacity 'suddenly' surged and why HBM became the preferred memory for high-performance GPUs. It also outlined the core concepts and rationale of HBM.
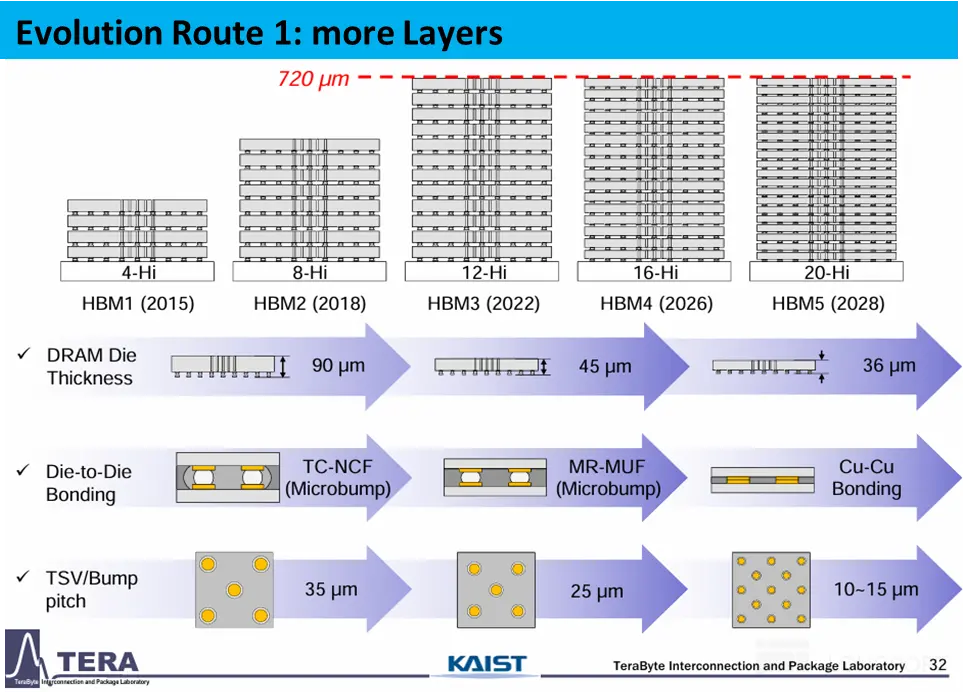
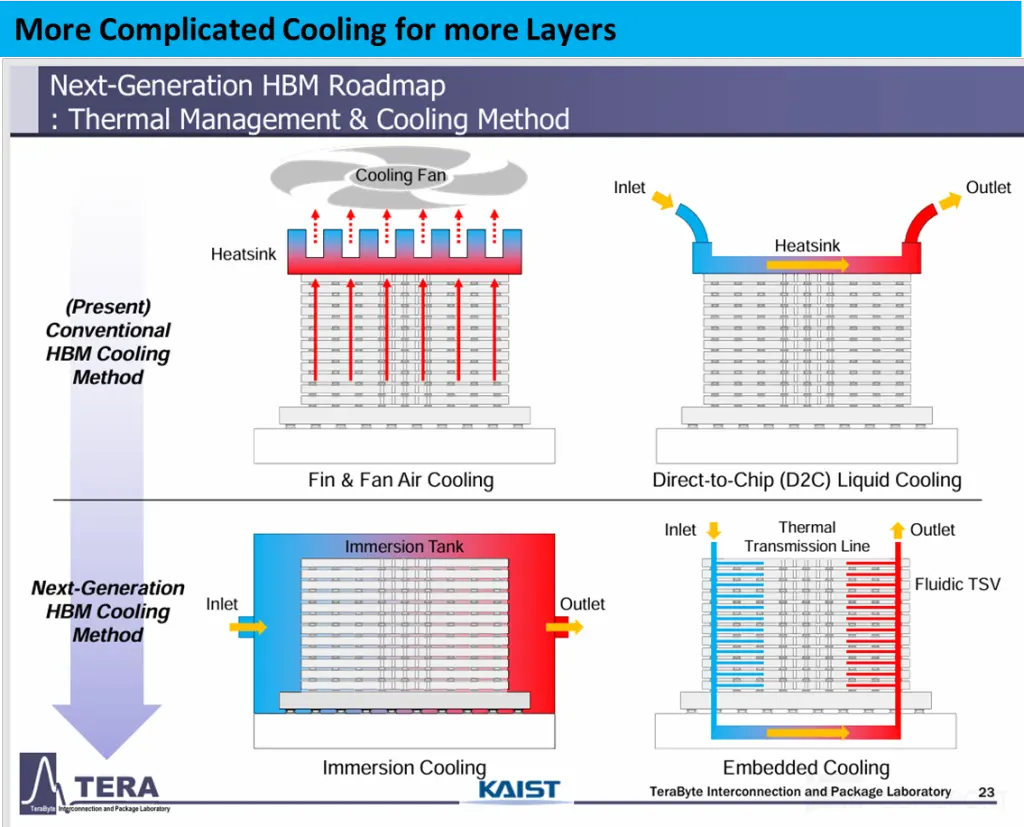
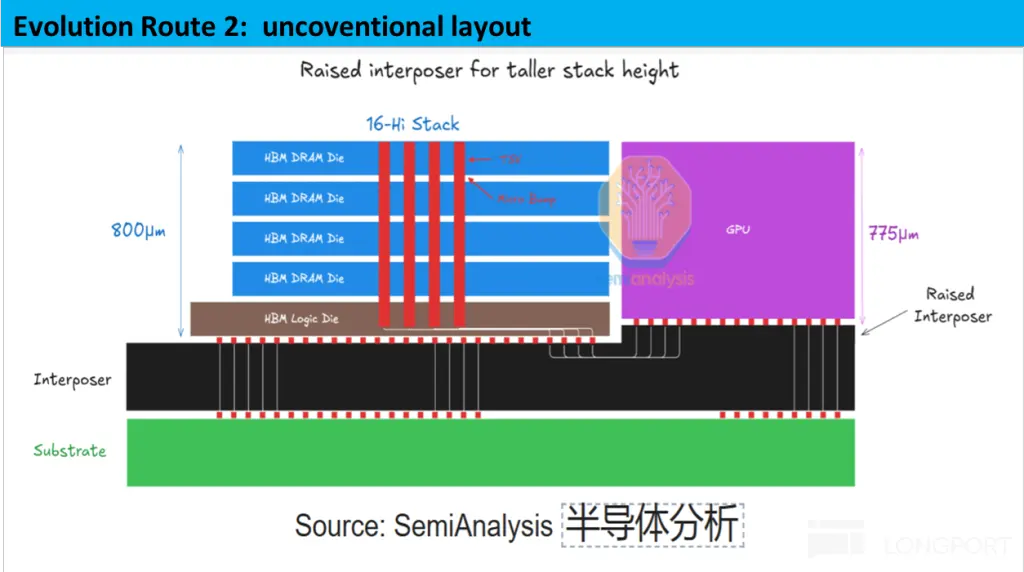
As AI advances, how will memory evolve to deliver larger capacity and higher bandwidth? Two seemingly conflicting signals have surfaced recently in the industry.On one side, the HBM roadmap keeps ramping, with stack counts moving from 12 to 16 and 20. On the other hand, per SemiAnalysis...
 +18
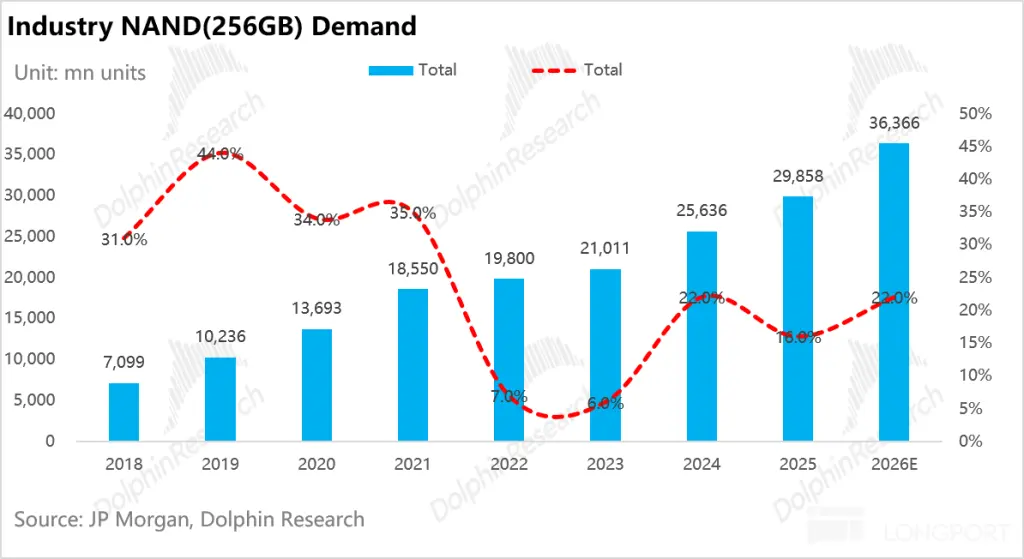
NAND is in a tight balance, with the call squarely on demand. Any let-up in supply discipline could cause the market to unravel.
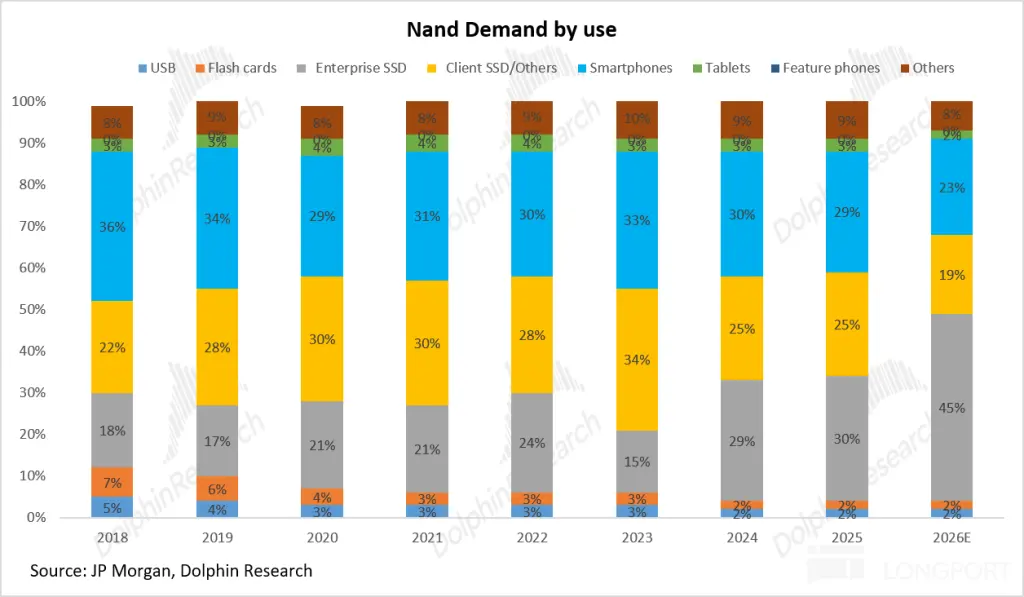
This AI wave has turned NAND flash from a cyclical, oversupplied commodity into a scarce strategic resource. SanDisk, spun off and freed from the drag of the legacy HDD business, is making a pure-play bet on NAND and data-center SSDs, catching the updraft.
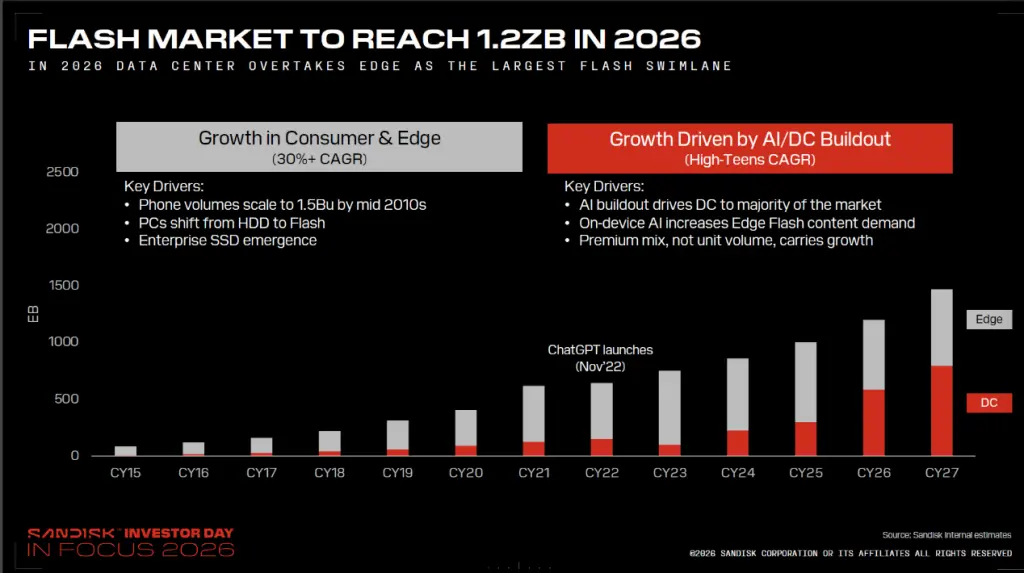
AI servers, when running inference, processing complex tokens and prompts, handling multimodal inputs (video, images), and generating synthetic data, need to read and write historical data at high frequency and in tight loops. Legacy cloud storage architectures can no longer keep up with these workloads...At the 2026 Investor Day (see Trans here), WDC laid out eye-popping metrics. Management provided the following outlook:
1) FY27 (through Jun-27): bit growth in the mid-teens, with prices edging up modestly each quarter. This implies the hyper-inflationary phase in NAND pricing has ended. The next four quarters should see steady, incremental price increases.2) FY28–FY30: a) Revenue to grow in the mid-to-high teens, driven mainly by bits (volume). Dolphin Research adds that the company is assuming bit demand CAGR of ~18%, with little to no price contribution...Below are Dolphin Research's Trans notes from $Sandisk(SNDK.US) FY26 Investor Day. Key takeaways: FY26 revenue of $20bn (+175% YoY) and a new biz model locking in $93.9bn in TCV, with floor-price GPM at ~80%.
Capex intensity to stay in mid-to-low single digits; Adj. OPM at 75%; Adj. FCF margin at 50%. All FCF will be returned to shareholders...


