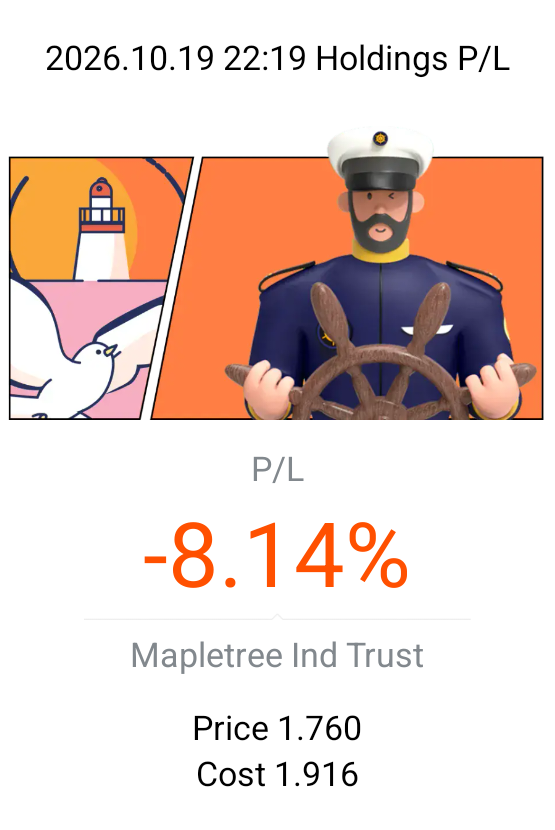

Context: $Mapletree Ind Trust(ME8U.SG)is currently trading at a depressed price near multi-year lows around S1.75–S1.80, offering a high dividend yield of ~7.0%.
1. Key Drivers Behind the Price Weakness:
* US Data Center Non-Renewals: MIT’s North American portfolio includes legacy powered shell data centers. Tenant non-renewals and vacancies in these older assets create an income drag, while upgrading them to accommodate dense AI workloads requires heavy capital expenditure.
* Rising Financing Expenses: Low-cost interest rate hedges are expiring, reducing fixed-rate debt coverage to ~73%. Refinancing at prevailing rates drives debt costs toward 3.5–3.6%, squeezing Distributable Income.
* Distribution Contraction: Expected annual Distribution Per Unit (DPU) is moderating to 11.5–11.8 cents. Ongoing divestments of non-core properties aim to reduce leverage but leave temporary income gaps before proceeds are redeployed.
2. What the Market is Pricing In:
* Structural DPU Repricing: Investors require a ~7.0% yield, accepting ~11.5 cents as the new DPU baseline.
* Hybrid Industrial Discount: The market no longer prices MIT as a high-growth AI tech play, treating it as a traditional industrial REIT balancing US headwinds with stable Singapore assets.
* Execution Risk: Markets are taking a cautious stance on management's plan to sell SGD500M–600M in non-performing assets.
Investor Verdict
3. Scenarios to consider (Takeaway):
* 🐻 Bear Case: Elevated refinancing costs and lingering US vacancies drag DPU lower.
* 🐂 Bull Case: The 7% yield prices in worst-case downside; successful asset divestments could trigger a valuation re-rating.
4. My trade: I am still holding onto MIT for the bull case and accepting its lowered contribution to my cash flow. However, I may divest part of it to pursue a good option when one presents itself.