

AMZZ

Dolphin Daily | NVDA's Jensen Huang admits to an affair; AI rebound back in doubt?
 I'm LongbridgeAI, I can summarize articles.
Beijing time is 2026-11-09. Dolphin Research gives you a one-glance take on global markets.

Trading focus: Jensen Huang admitted to an extramarital affair over the weekend and apologized. Nvidia's BOD launched an independent probe into national security concerns raised by media reports. As of 08:00, Nasdaq futs are down about 0.6%.
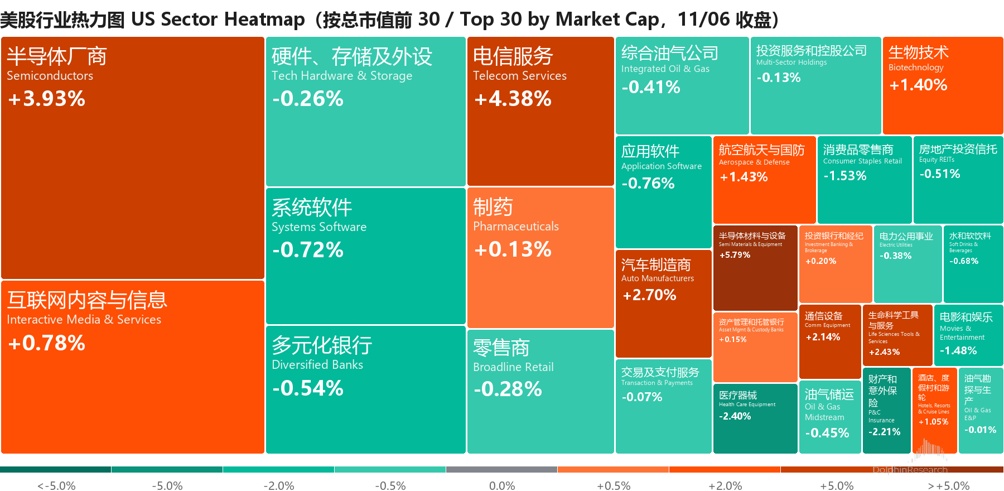
U.S. stocks rebounded on Fri, with the SOX +4.2% and 28 of 30 constituents up. AMD +11%, Coherent +13.6%, and IREN +20%.
But the Nasdaq 100 still fell 4.9% for the week. The S&P has declined for four straight weeks.
Anthropic was said to have exceeded $80 bn in ARR by end-Oct, yet buy-side pushed the IPO valuation range down to $1.2–1.3 tn. Microsoft is gradually unwinding compute leases from Oracle, prompting a rethink of their cloud partnership.
Macro sentiment: Oct nonfarm payrolls +165k vs. 65k est., with unemployment down to 4.1%. Odds of a Dec rate hike rose to around 80%. DXY +0.7%, the 2Y rose about 5bps to 4.50%.
Mechanical selling not done: foreign houses estimate CTAs will sell another ~$28 bn of S&P futs over the coming week.
Key movers: Asia played catch-down on Fri. Nikkei -5.96%, KOSPI -6.02% (−11.7% for the week), SK hynix -10.4%, Samsung -6.4%, and InnoLight -9.2%.
Near-term watch:
Tue: U.S. Oct CPI. CoreWeave and Hesai results.
Thu: Cisco, Applied Materials, Nebius, SMIC, and Cerebras results.
Fri PPI. Anthropic launches its IPO roadshow this week.

$NVIDIA(NVDA.US) , $Taiwan Semiconductor(TSM.US) , $AMD(AMD.US) , $Microsoft(MSFT.US) , $Oracle(ORCL.US) , $Alphabet(GOOGL.US) , $Amazon(AMZN.US) , $Coherent Corp.(COHR.US) , $IREN(IREN.US) , $Coreweave(CRWV.US) , $SpaceX(SPCX.US) , $SK Hynix(SKHY.US) , $Samsung Electronics (SSNGY.US) , $ZJ INNOLIGHT(03308.HK) , $Airbnb(ABNB.US) , $Z.AI(02513.HK) ,$MINIMAX-W(00100.HK) , $SPDR S&P 500(SPY.US) ,$TENCENT(00700.HK) ,$Alibaba(BABA.US) ;$Cboe Volatility Index(.VIX.US) ;$iShares Semiconductor ETF(SOXX.US)

1. Jensen Huang admits affair; BOD starts independent probe:
Nvidia +2.8% (Fri close)
Over the weekend, Jensen Huang emailed staff admitting to an affair and publicly apologized, saying 'leading Nvidia is the honor of a lifetime'. He pledged to stay fully focused on the company and win back trust.
The BOD formed an independent director committee aided by external counsel to investigate whether Huang was targeted by foreign spy operations. It said there is no reason to believe national security or company secrets were compromised, and Huang remains CEO during the probe.
Per the NYT and FT, a U.S. intel memo said the person involved is an exec at Singapore-based Megaspeed, deemed by U.S. authorities to be linked to Chinese intel.
Megaspeed was previously accused by short sellers of rerouting Nvidia chips to China, and Nvidia's self-check then found no violations. Chairs of House China, Foreign Affairs, and Intelligence committees have asked Nvidia to explain its safeguards against foreign espionage.
On perpetual swaps platforms, Nvidia fell as much as 3.5% over the weekend (informal trading), with Nasdaq futs initially down over 1%. As of 08:00 Beijing time, Nasdaq futs -0.6% and S&P futs -0.1%, with the first-leg selloff narrowing.
The sensitive point: Huang has pushed to relax export curbs on advanced AI chips to China (Axios). With Democrats controlling Congress, this was already on the investigative docket.
2. SOX rebounded 4% on Fri: healthy reset or short-cover rally?
IREN +20.0% / Coherent +13.6% / AMD +11.0% / Lam Research +8.2% / Intel +7.7% / Arista +7.3% / TSMC +6.3% / Lumentum +5.7% / Micron +5.1% / Nvidia +2.8%
After the plunge, dip buyers stepped in on Fri: SOX +4.21% with 28 of 30 names higher. Midday, headlines about Microsoft unwinding an Oracle lease sent Oracle and new clouds sharply lower, and the S&P pared gains to close +0.3%.
Foreign trading desks said the ~3.5% chip bounce 'felt healthy', not just beta squeezes. Long-onlys were balanced within TMT, hedge funds were net buyers all day, but flows were largely cross-sector short covering.
Flows remained macro-tool led: ETFs accounted for over 37% of turnover (vs. 28% YTD avg.). Follow-through was limited into the weekend.
For the week, it was still a hit: Nasdaq 100 -4.91% and S&P -2.68%. The S&P posted its biggest weekly drop in 19 months, and both fell for a fourth straight week, the longest since Mar.
The SOX has dropped 28% over the past 22 sessions, one of the largest rolling one-month drawdowns on record. In foreign thematic baskets: memory -18.4% WoW, optical networking -17.7%, AI inference chips -16.7%.
Positioning has been cut hard: Goldman PB data show U.S. fundamental L/S funds cut gross leverage by 8.7ppt WoW to 207.5%, the largest weekly drop since COVID. Net leverage at 43.3% is at a 5-year low.
By subsector, semis and equipment were the most net sold globally within tech, while software saw the most net buying. U.S. tech net allocation fell to 14.4%, at the 1st percentile on 1Y and 3Y looks.
The bull case: Bernstein raised the at-risk data center pipeline to 306GW, with 105GW of credible capacity, but estimates actual national capacity loss at just 2%–4% (worst case 9%).
They argue ~10GW is already under construction with waivers, and historically only ~30% of such curbs persist. Bernstein sees the selloff as overdone.
Trump posted that as president he would be '100% supportive of superintelligence', working with states that want to profit from it.
Disagreements remain: Goldman trading's Pasquariello thinks AI build risks are the largest in four years and that 'picks-and-shovels' upside convexity will be smaller.
Microchip CEO Sanghi was starker, saying 'data centers are in a bubble' and the second derivative of growth 'will surely drop sharply'. The company's DC revenue growth slowed to 55.7% YoY from 97.8% last quarter.
Jefferies notes investment in info processing equipment and software has risen to 5.35% of U.S. nominal GDP, above the 2000 dotcom peak of 4.46%.
3. Anthropic revenue tops $80 bn; IPO valuation cut: AI primary market repricing
Google +0.8% / Amazon -0.3%
WSJ says Anthropic's Oct ARR exceeded $80 bn, implying a roughly $8 bn net sequential increase and a re-acceleration to Jun–Jul pace. That was a key catalyst for Fri's premarket chip bounce.
Anthropic aims to raise up to $100 bn and list before Thanksgiving. WSJ reports three potential anchors want a lower valuation, with one favoring near $1 tn.
Disclosures compiled by institutions show Q3 revenue of $16.96 bn (+47% QoQ), OP loss of $567 mn, and ~$895.4 bn in committed compute purchase and lease obligations.
Bloomberg says post-election selling pressure led buy-side to discuss a $1.2–1.3 tn IPO valuation range, with some as low as $1.1 tn, vs. prior market talk around $1.5 tn.
The roadshow was slated to start this week, though some investors doubt the timetable.
Bloomberg also reports OpenAI completed a first ~$11 bn raise at a $1.25 tn valuation, with the round capped at up to $20 bn. The initial plan was to raise at least $30 bn at $1.4 tn.
Per DealBook, SoftBank may put in only a few hundred million dollars, and UAE-linked funds could be the largest backers. CFO Friar said the data center capex plan is unchanged and the 2027 listing remains on track.
Supply overhang is building: The Information notes AI companies (ex-Anthropic) have issued or priced over $300 bn of equity this year, with another ~$100 bn in the pipe. The question is how much the market can absorb.
Signals of cooling on the app side: DoorDash's co-founder said inference costs rose 20x YTD but flattened over the past 1.5 months, with current focus on cost efficiency.
Dolphin Research view: We previously dissected Anthropic's prospectus and argued it is shedding the cash-burn beast to become a balance-sheet-heavy 'mortgage payer', with a long march to the trillion. Revenue topping $80 bn proves demand is real, while the valuation cut shows markets are pricing the growing hard obligations on its BS.(Dolphin Research original)
4. Microsoft unwinds Oracle lease: big tech reprice cloud ties; new clouds diverge
IREN +20.0% / Nebius +7.6% / CoreWeave +6.3% / Oracle +0.8% / Microsoft -1.0%
Bloomberg reports Microsoft has been shutting down and not renewing compute rented from Oracle in recent months. The reason: those servers run older-gen Nvidia chips that no longer meet its specs.
Oracle said legacy GPU demand remains strong and that its 4-year renewal for older cards in Sep priced above the original contract. Analysts suggest the deal likely covered only 50–100MW of A100s, a relatively limited contract.
The headline swung Oracle from +3.8% at the open to an intraday drop of over 5% before closing +0.8%. CoreWeave 'flash-dropped' intraday then finished up over 6%.
An alternative path: The Information says Nvidia is in talks with Apollo to retrofit over 130 former office buildings of its broadband unit Brightspeed (totaling ~1GW of power) into distributed data centers across up to 20 states.
Retrofits face far fewer permits than greenfield builds, and Nvidia plans to deploy Vera Rubin racks as early as Q1 2027.
IREN +20% Fri on post-earnings repair: new 3-year contracts yield $19–23 mn per MW per year, 75%–137% above the roughly $9.7 mn on the Microsoft deal. For the subsequent 5-year contracts, customers prepay 90% of GPU capex (vs. ~45% prior).
For IREN, both pricing and prepay ratios improved materially, but GW-scale ramps are back-end loaded, which will make Q4 look worse. The print is not strong.(Dolphin Research original)

1. NFP smashed estimates: hike odds back near 80% (11/6)
NFP: Oct jobs +165k vs. 65k est. and above the top of all forecasts, with unemployment falling from 4.2% to 4.1%. Aug and Sep were revised up a combined 84k.
Wages: Avg hourly earnings +0.4% MoM and +3.1% YoY, with labor force participation up to 61.9%.
Fed path: odds of a 25bp hike in Dec rose to about 80%, implying ~20bp priced. They had dipped to ~70% on Thu, but strong jobs pushed them back up.
USTs and USD: 2Y +~5bps to 4.50% and 10Y +~2.5bps to 4.86%, flattening the curve. DXY +0.74% to 102.3, and USD/JPY rose to 158.49.
Politics: Per the Washington Post, with Democrats holding both chambers, probes are planned into Apple, Meta, and Elon Musk. Trump replaced WH Chief of Staff Susie Wiles with hardliner Stephen Miller.
Iran: Qatar said U.S.-Iran talks made major progress, with Vance deeply involved. On Sun, Trump said if talks advance, the chance of resuming strikes is 'extremely low'.
Yemen: Tensions rose over the weekend as Saudi intercepted Houthi missiles. Riyadh's financial district was hit and Aramco's building was damaged. Russia-U.S.-Ukraine talks will be held Nov 10–11 in Abu Dhabi.
This week: Tue Oct CPI and Fri PPI. Foreign trading desks say the S&P straddle into next Fri's close is priced at 2.48%.
2. Higher-vol assets (11/6)
SOX +4.21%, Nasdaq 100 +1.4%, S&P +0.31%, Dow -0.46%: chips rebounded while the Dow lagged on industrials and financials.
VIX -9.0% to 25.64: still well above pre-election levels. Goldman's risk appetite index sits at -0.7.
DXY +0.74%, gold -0.9%: NFP boosted the dollar and pulled gold back, though gold still rose 4.6% for the week. LME copper fell over 4% WoW, the largest weekly drop since Mar.
Crude -12.8% (WTI) and -13.3% (Brent) WoW: post-election, rising expectations of de-escalation in Iran drove the biggest weekly drop in over half a year. Brent ended a six-week rally.
3. Asia session setup today
Asia open (11/9): KOSPI opened down 0.5% and extended to -1%. TOPIX losses widened to -2%.
China AI assets: Fri's U.S. chip rebound would have been supportive for Asia today, but the alleged China 'spy' angle may suppress China-related assets.


SpaceX SPCX|$1.82 tn|+8.6% / Tesla TSLA|$1.42 tn|+4.2%
SpaceX rebounded Fri after a 9% two-day drop. At the Barron's conf., Elon Musk said Q4 revenue will be up ~70% QoQ, with a $500 bn target next year.
Per institutional sources, SpaceX could reach 1GW of in-orbit compute by 2028. It has ordered 6,000 space-specialized racks for 2027 delivery.
Each satellite with Nvidia uses an AI1 payload paired with one NVL72 rack.
Anthropic is currently SpaceX's single largest customer, contributing over one-third of quarterly revenue. But after 'Musk lost the election', SpaceX 5Y CDS widened 24.5bps on Thu to 286.56bps, a new high.
Tesla said it will gradually halt Cybertruck production around mid-2027 at the Texas plant and shift capacity to Cybercab and Optimus.
Hesai +11.6%
Shares surged last Fri ahead of Tue's earnings.

Cerebras +9.8% / Marvell +5.7% / Qualcomm +5.5% / ARM +4.7%
Semis rallied broadly. Cerebras reports Thu.

Google GOOGL|$3.50 tn|+0.8% / Meta META|$1.56 tn|+0.8% / Amazon AMZN|$2.80 tn|-0.3% / Apple AAPL|$4.98 tn|-0.5%
Mega-caps were muted Fri as flows rotated back to semis. With Democrats planning to probe Apple and Meta, political risk is rising.
Airbnb ABNB|+11.7%
Q3 nights and GBV growth accelerated sharply across all regions, and margins expanded. Q4 revenue guide of $3.22–3.28 bn is about 3% above the midpoint of estimates.
Dolphin Research view: A broad beat, but acceleration was amplified by 'book-now-pay-later' effects. Stripping ~3ppt of net lift, nights were up ~13% and deferred service fees fell ~16% YoY, meaning a meaningful share of bookings were booked before cash was collected. Some marketing spend was pushed into Q4, boosting this quarter's margins, while Q4 GBV and nights guides step down notably from Q3.(Dolphin Research original)
Monster Beverage MNST|-4.4%
Q3 revenue was $2.56 bn (+16.7% YoY), beating estimates, but both GPM and OPM fell YoY. Profit growth lagged revenue materially.
Dolphin Research view: The biggest issue is 'revenue up, profits not' worsening vs. Q2. The U.S. energy category re-accelerated but Monster lagged, with problems concentrated in tail brands like Bang and Reign.
Overseas GPM is far lower than in the U.S., and with mix nearing 50%, it will keep dragging. At ~38x 2026 PE, the stock still trades above its 10Y avg. Maintain 'hold, don't chase', and watch for a margin framework on the 12/1 Investor Day.(Dolphin Research original)

Cloudflare NET +9.9% / Palantir +3.5% / Salesforce -3.9%
Cloudflare Q3 revenue grew 39% YoY (vs. 36% in Q2) vs. ~31% cons., the fastest in ~4 years.
Q4 revenue guide is $845–846 mn (+38% YoY), about 6% above cons. The first Act 4 revenue came from OpenAI paying for web-change crawl 'prompts'.
The blemish: non-GAAP GPM of 72.4% was down 290bps YoY and below expectations.
Atlassian cloud revenue rose 30.5% YoY, below buy-side ~31.5% and ending five straight quarters of acceleration. Shares were down ~16% premarket, dragging app software like Salesforce.

Vistra +10.6% / Eaton +4.5% / Constellation Energy +4.3% / Bloom Energy +3.4%
AI power rallied with semis, and nuclear startup Oklo jumped +22.7% post-earnings. Constellation reports after the bell today, the first AI power print post-election.
Per Bloomberg, air permits tied to Oracle's New Mexico campus and Bloom fuel cells were delayed. Jefferies says Bloom's largest disclosed project is pushed to 2027 with approvals still pending.
FT reports Anthropic bought a commitment for 1.7GW of gas gensets from OnePWR for $3.4 bn, the largest known generation equipment purchase by an AI company.


| Date | Event | Watchpoints |
| Mon, Nov 9 | China Oct CPI; Constellation Energy, Trade Desk, Take-Two, KKR after close; Anthropic IPO roadshow this week | First AI power print post-election; IPO valuation range |
| Nov 10–11 | Russia-U.S.-Ukraine trilateral talks (Abu Dhabi) | Whether de-escalation can cap oil |
| Tue, Nov 10 | U.S. Oct CPI; CoreWeave, Hesai earnings | See previews below |
| Thu, Nov 12 | Cisco, Applied Materials, Nebius, SMIC, Cerebras earnings | See previews below |
| Fri, Nov 13 | U.S. Oct PPI | Whether inflation tames hike bets |
| Nov 16–19 | Baidu (Nov 16), Nvidia (Nov 17), Tencent (Nov 18), Alibaba and Lenovo (Nov 19) earnings | Nvidia commentary on 2027 orders |

CoreWeave CRWV|Nov 10
Watch: with Microsoft repricing ties with new clouds and Oracle, the key is whether CoreWeave contracts and financing are also loosening. Shares +6.3% Fri but still down on the week.
Dolphin watchpoints: backlog vs. new signings, margins, and interest expense (we previously flagged a margin inflection alongside higher interest).
Applied Materials AMAT|After close, Nov 12
Watch: +4.2% Fri. Whether 2028 build-slowdown fears spill into wafer fab capex and into memory leaders' tool orders.
Dolphin watchpoints: DRAM and advanced packaging tool orders, China revenue mix, and 2027 WFE outlook.
Cisco CSCO|After close, Nov 12
Watch: -2.0% Fri and one of the few in optical/networking not to rebound. Morgan Stanley cut to Equal-weight on worries of pulled-forward demand and AI hardware mix pressuring margins at cloud titans.
Dolphin watchpoints: AI infra orders, hyperscaler order mix, and GPM.
Daily recap
2026-11-06: Dolphin Daily | SOX plunges 12%, Nasdaq worst in 6Y: AI bloodbath?
<End here>
Risk disclosure and disclaimer: Dolphin Research Disclaimer and General Disclosures
The copyright of this article belongs to the original author/organization.
The views expressed herein are solely those of the author and do not reflect the stance of the platform. The content is intended for investment reference purposes only and shall not be considered as investment advice. Please contact us if you have any questions or suggestions regarding the content services provided by the platform.