

ANT

Dolphin Daily | AI IPO prospectuses revive AI investing; is the 'growth' memory story out of favor?
 I'm LongbridgeAI, I can summarize articles.
Good morning! It is Oct 28, 2026 Beijing time. Dolphin Research walks you through global markets at a glance.

Trading focus: Anxiety over A Co.'s ARR eased, with AI sentiment rebounding for a second day. Ramp data show Anthropic's Oct spend rose ~25% MoM, implying ARR of ~$760–780 bn, and New Cloud rallied (NBIS +11.2%, CRWV +7.9%).
Storage split screens: SK Hynix posted Q3 OP of ~KRW 83 tn this morning, far ahead of estimates, and guided total 2026 shareholder returns of ~KRW 100 tn. Yet STX beat and still fell 5.3% AH.
Macro tone: Rates were flat ahead of the FOMC, with the 10Y near 5.00%. The odds of a hike this meeting are ~10%, while a 25bp hike in Dec is 80–90% priced; WTI fell 1.7% to about $100.
Key movers: SOX +3.6%, Nasdaq 100 +1.3%, both up >1% for two straight sessions. AMD +5.5%, AVGO +4.0%, CLS +12.1%, and AI power stocks broadly higher (BE +7.1%); application software and IT services fell again (HUBS -5.0%, ACN -4.9%).
Near-term watch: MSFT, GOOGL, NOW report tonight, with GEV and VRT pre-market. FOMC decision at 2:00 a.m. tomorrow Beijing time; Thu night AMZN, INTC, SNDK report.

$SK Hynix(SKHY.US) , $Seagate Tech(STX.US) ,$Anthropic(ANT.US) , $Broadcom(AVGO.US) , $AMD(AMD.US) , $Microsoft(MSFT.US) , $Alphabet(GOOGL.US) , $Amazon(AMZN.US) , $Meta Platforms(META.US) , $Nebius(NBIS.US) , $Coreweave(CRWV.US) ,$Bloom Energy(BE.US) , $Oracle(ORCL.US) , $Tesla(TSLA.US)
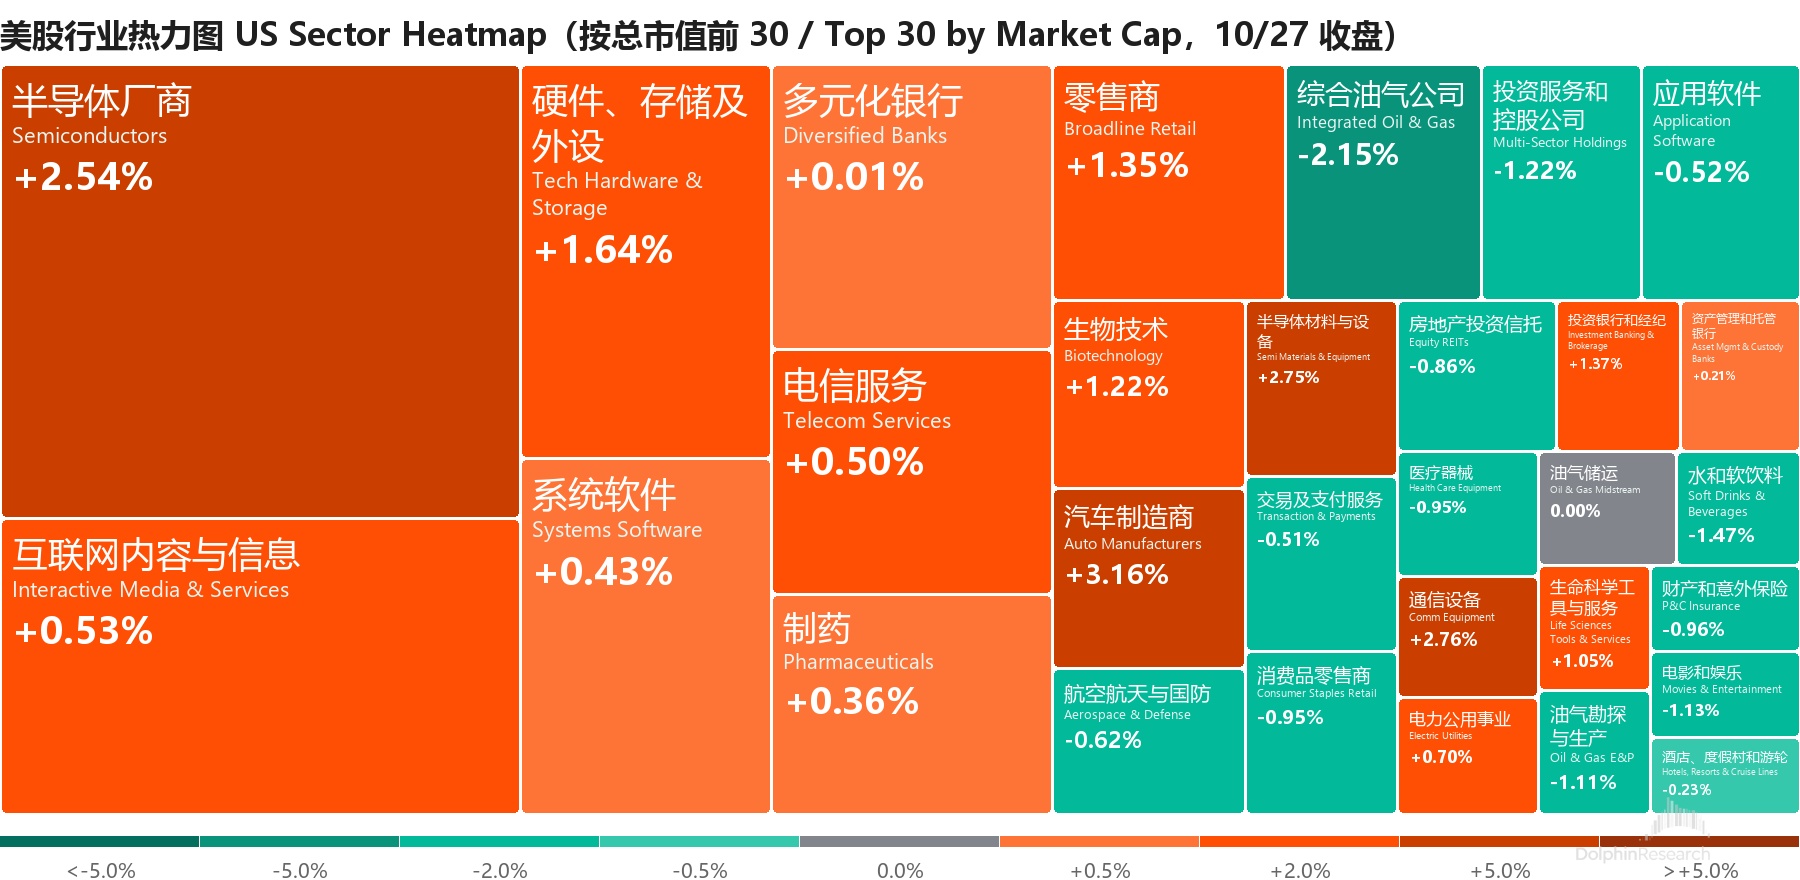
Moves: U.S. and global assets reflect Tue 10/27 close vs. the prior session, with AH noted separately.

1. Anthropic's Oct ARR signals keep improving; New Cloud the first beneficiary
Ramp's CEO said Claude 5.5 may have 'hit a turning point', with Q4 better than Q3. Midday Ramp data showed Anthropic spend up ~25% MoM, implying Oct ARR of ~$760–780 bn, and a print above $780 bn would be a positive.
New Cloud surged: NBIS +11.2%, CRWV +7.9%, IREN +7.9%. CRWV 5Y CDS eased to ~1,071 from the 10/15 peak of ~1,188, though still ~26% wider vs. end-Sep.
Per reports, Jensen Huang said capital may become the AI bottleneck. He expects the top 5 clouds plus SPCX to account for 84%/83% of incremental U.S. compute in 2026/27, with capital concentrating at the hyperscalers.
Bears: Bernstein kept CRWV Underperform. On a power-adjusted basis, signed backlog implies $44–68 bn of incremental capex, of which $18–42 bn still needs external funding, and shorter contract terms make each $1 of growth more capital-intensive.
Dolphin view: An Oct ARR above $75 bn eases 'labs can't pay the bills' worries. New Cloud's challenge is capital intensity; better ARR chatter will not fix financing costs.
2. SK Hynix prints KRW 83 tn OP: memory upcycle still accelerating, but positioning is only cautiously restored
SK Hynix Q3 this morning: revenue ~KRW 104.6 tn, topping KRW 100 tn for the first time. OP ~KRW 83.3 tn, above LSEG consensus of ~KRW 76.7 tn and buy-side expectations near KRW 80 tn.
In USD, revenue ~$78.9 bn and OP ~$62.8 bn, ahead of market ~$74.8 bn and ~$58.5 bn. OPM ~80% and GPM ~86%; DRAM ASP rose 28% QoQ and NAND +25%.
Volume/price: DRAM ASP gains in the high-20% band QoQ and NAND in the mid-20% band. The company expects HBM4 shipments and revenue to surpass HBM3E in Q4, with 2027 DRAM demand growth in the mid-20% and NAND in the high-10% range.
Shareholder returns: ~KRW 100 tn planned in 2026, including >KRW 30 tn in cash dividends and >KRW 60 tn in buybacks/cancellations (incl. a new KRW 20 tn buyback). Q3 DPS KRW 20,000 (incl. KRW 10,000 special dividend related to Kioxia).
Buy-side thresholds had been at least KRW 30 tn combined buybacks and dividends, with >KRW 40 tn viewed as positive.
Hair: net income ~KRW 40 tn, well below ~KRW 55 tn expected. The variance awaits a follow-up read from Dolphin Research.
HBM4 noise: reports say NVDA is assessing mixing 8-layer HBM4 with HBM4E on Rubin Ultra due to thermal and yield issues with 12-layer HBM4, and cutting Rubin's HBM4 bandwidth by nearly 13%.
Per reports, 8-layer HBM4 for NVDA from Samsung and SK Hynix will not enter mass production/shipment until around Q2 next year.
Positioning into prints: per foreign trading desks, memory is a crowded short. Samsung and SK Hynix trade at only ~2.5x buy-side 2027 EPS and ~0.8x 2028 PB, as 'no one believes the cycle's durability'; buy-side is still waiting for 10–15 year LTAs with U.S. clouds.
LTA pricing is not low already: reports suggest over 70% of Korean vendors' planned memory output next year is covered by 5-year supply agreements. JP Morgan expects Q4 contract prices of DRAM +13% and NAND +18%.
On the call, management said the standard LTA term is 5 years, some clients are discussing extensions, and pricing flexes within a band vs. market. Q4 DRAM bit shipment growth is guided to mid-20% QoQ.
On the same night, STX beat on results and guidance but still fell 5.3% AH: Dec revenue guide $4.8 bn, below buy-side $4.9–5.05 bn. Shipped capacity 220EB, up only +1% QoQ and ~15EB below expectations, with QoQ growth almost entirely from TB pricing (~+16%).
Dolphin view: After the 'moonshot' narrative faded, LTAs became the safe harbor. Versus peers, SK Hynix has relatively less price-locked LTAs, making it more levered to upside pricing; this quarter's pricing jump underlines that elasticity.
But the market is now pricing the timing of the cycle peak, not expanding multiples. The key is how long dividends support the stock and unit pricing holds; a detailed take is coming.
3. Financing digested, ASIC chain leads: AVGO +4%, CLS +12%, AMD +5.5%
AVGO: the market digested the $63 bn Anthropic chip SPV. DA Davidson upgraded to Buy, arguing shares imply near-zero probability of an Anthropic IPO raise and an OpenAI top-up; KeyBanc said AVGO formally won Anthropic's ASIC (late-2028/early-2029, 5–10 mn unit life).
Risks are rising too: UBS estimates guarantees across the two deals at ~$70–75 bn. Wolfe says AVGO structured ~72.5% of financing on residual value, with max exposure of ~$45 bn here and $29 bn prior, amortizing to zero within five years.
AMD: Edgewater checks indicate MI450 builds and CPU supply improve into 2H26, with CPU pricing possibly rising again in Q1. AMD will invest $1 bn via META's stock issuance, and the first Helios racks have been installed and tested at META.
Dolphin view: Suppliers putting up cash and guarantees to lock orders raises visibility for 2027/28 AI revenue. But contingent liabilities will dilute current P&L quality; only high growth can offset that.
4. AI power broadly higher, with 'will power be in surplus by 2028' as the hot debate
BE +7.1%, GEV +4.7%, VRT +4.4%, OKLO +5.4%, VST +3.5%. Barclays said excluding the Q2 tariff refund, BE's product GPM expanded ~540bps QoQ to 36.5%, but the ~$5.8 bn long-term supply commitment is a new risk.
Non-specialists now peg 2027 data center scale at ~27GW, up from just above 20GW a few weeks ago, with SPCX 'single-handedly pulling up estimates'. The most debated topic among institutions is whether power supply will be in surplus by 2028.
Bear case rebuttal: Morgan Stanley sees shortages driven by AI and reshoring, with a U.S. power shortfall of ~43GW by 2028, shifting pricing power to infra owners.
5. Dolphin Hotspot | Anthropic: shedded the 'cash burner', becoming a 'mortgage slave'; the trillion-dollar march is still long
Inference makes money, training burns cash: H1 inference GPM was 85%, but $6.6 bn of training compute within $9.7 bn R&D consumed ~40% of revenue. Net of ~ $2.7 bn channel fees, GPM was ~68%, with GAAP OP loss of $690 mn and Adj. OP of +$1.62 bn.
The trillion-dollar tab: compute commitments jumped from $54.6 bn to ~$1.01 tn in ten months, most take-or-pay. Spread over contract terms, peak annualized runs ~ $115 bn, and to keep compute at ~55% of revenue, annual revenue needs to be ~$210 bn, or 4–5x 2Q26 annualized $46.2 bn.
Dolphin view: Losses used to sit on the P&L; now the burden sits on the balance sheet. If revenue scales 4–5x, this becomes a cash cow; if not, the trillion-dollar bill will reward whoever commands the table — model owners or the clouds. (Original)

1. FOMC tonight, PCE on Thu
USTs and liquidity: the 10Y hovered near 5.00%, rebounding early then fading to flat. The 2Y rose +2.5bps to ~4.73%, and the $70 bn 5Y auction was mediocre.
Consumer confidence: Oct Conference Board consumer confidence came in at 91.7, well above 81.0 expected, capping rate declines.
Fed path: Wed (Thu 02:00 Beijing) hike odds are ~10%, while a further 25bps in Dec is 80–90% priced, and a Mar 2027 hike is also in the curve. The Fed is in blackout.
Waller press conference: Fed Chair Waller will hold a press conference at 2:30 p.m. on 10/28 (Thu 02:30 Beijing).
Oil: Saudi, Turkish and Pakistani officials met Iran in Tehran and agreed to keep talking, overshadowing a Houthi attack on Saudi's Ras Tanura refinery; WTI -1.7% to about $100.
2. High-vol assets (10/27)
SOX +3.6%, Nasdaq 100 +1.3%: Nasdaq 100 posted back-to-back >1% gains for the first time in ~3 months. The S&P rose +0.6% to 7,722, the Dow was flat, with ~60% of S&P constituents down and gains concentrated in the AI complex.
Momentum rebalance: Goldman said the momentum factor rose +2.5% after ~20% drawdown in recent weeks. Asset managers were net buyers of tech, and desks see the bounce driven mainly by reduced supply (selling pressure).
VIX -4.7% to ~17.5: index options imply ~0.6% move tomorrow, above ~0.5% today.
Gold +0.8% to ~$4,070: Bitcoin +1.1% to ~81k, after briefly dipping below 80k in the morning.
3. Asia open and today's setup (10/28)
Asia open: Korea's KOSPI extended gains to +4%, with SK Hynix +4% and Samsung Elec +6%. The Nikkei opened +0.7%.
Korea memory: SK Hynix's results and KRW 100 tn returns beat buy-side bars, but Hynix had already risen 5.2% and KOSPI +3.1% yesterday, and net income missed; a gap-up open is likely. Whether gains hold hinges on call color around LTAs and HBM pricing.
HDD vs. memory read-across: STX -5.3% AH shows 'price-up without volume' is facing scrutiny. Japan/Korea memory likely trade firm, but U.S. memory could dip first tonight and then look to SNDK on Thu.
A-share compute: A-shares pulled back yesterday (SZCI -2.5%), with Zhongji Xuchuang -2.9% and Victory Giant -7.4%, diverging from U.S. optical/ASIC strength. There is room for a sympathy bounce today, but A-shares are still de-crowding.
A-share positioning: per Goldman, public funds' TMT weight fell from 61.7% to 53.3% in Q3, mainly passive de-risking on price declines, with ChangXin Memory entering the top-20 holdings. Local investors think a stabilization in micro-cap equities is key for a bottom.


STX | $152.0 bn | +3.7% (AH -5.3%) / WDC +6.9% (AH -0.7%) / MU +2.8% / SNDK +3.9%
Evercore said WDC raising capex to ~8% of revenue (vs. 4–6% LT framework) is to improve areal density, with a ~3-year payback. SNDK reports Thu AH.

NVDA | $5.26 tn | +0.9%
NVDA committed to invest $3 bn via META's stock issuance, and META raised the first tranche to $25 bn. AMKR said ~ $3 bn of advanced packaging prepayments from NVDA will be received in 2027.
Per reports, NVL72 racks total ~73k/~96k units in 2026/27, Vera Rubin yield is above 85%, and SPCX is expected to be the largest buyer (~20k units). GB300 rack quotes have risen to ~$6.5 mn.
TSM | $2.27 tn | +2.9%
Taiwan media say CoWoS pricing is set to rise 10–20%, with equipment lead times extended to 8 months. CoWoS monthly capacity is expected to exceed 130k wafers in 2026, targeting 200k in 2027.
INTC +3.6% / CBRS +10.1%
INTC: acquiring quantum software platform Classiq for $2.3 bn; Needham called it the largest quantum deal to date. Earnings Thu AH.
The deal is expected to close in H1 2027 and is the first M&A under Pat Gelsinger. KeyBanc said INTC has won foundry orders from AAPL, AVGO, etc., with 14A 0.9 PDK imminent.
CBRS: ORCL announced CBRS systems on OCI, finally lifting the shares.
AMKR +8.5% / FLEX +8.3%
AMKR: Q3 revenue and Q4 guide missed on smartphone weakness, with shares down ~6% AH initially. The call highlighted NVDA prepayments for advanced packaging and facilities capex >$2 bn in 2027, flipping the stock.
FLEX: BofA said the pullback was overdone; ~8x 2028 PE is back at historical lows.

MSFT | $3.95 tn | -0.2%
Reports tonight AH. About 60k voluntary departures mark the third round of adjustments this year, excluding data center and AI infra roles; the market expects FY27 capex of ~$175–190 bn.
GOOGL | $3.92 tn | +1.2%
Reports tonight AH. Buy-side remains cautious due to third-party data, base effects and relative risk/reward; buy-side sees Search growth ~14% (Wall St. 14.7%), with feedback closer to 13–14%.
GOOGL released the world model Genie 4, which can generate two-minute simulations with simultaneous audio and video; prior versions hit gaming stocks, but RBLX and TTWO were steady today.
Dolphin view: GOOGL started its capex ramp later than peers, so margin erosion will be more visible next year. The test is whether core Search remains stable, while Cloud backlog builds and models progress. (Earnings review)
AMZN | $2.73 tn | +1.6%
Reports Thu AH. The stock is still >12% below the Aug high, and desks prefer positioning long into the print; AWS growth is expected at ~43%, with channels saying retail was slightly better than expected in Q3 and the CEO saying capacity is largely sold out for 2026–2027.
META | $1.59 tn | -1.6%
The $25 bn stock offering was 5x covered, yet shares fell. BNP Paribas estimates Muse costs ~$180 per free user per year, needing a 10x cost reduction to break even, and could add >$8 bn revenue by 2028.
Top 15 holders took ~70% of the offering. The offering price was $625 per share, with more than half allocated to long-term and existing holders; AMD subscribed $1 bn.
Dolphin view: Class C shares essentially pre-fund future investment. Near-term real dilution is ~5.7% and not large, but the financing overhang still weighs on valuation. (Original)
ORCL | $396 bn | +3.5% / NBIS +11.2% / CRWV +7.9% / IREN +7.9%
Holds Analyst Day today. Yesterday it announced multi-GW NVDA Vera Rubin capacity and that GOOGL TPU and CBRS systems are coming to OCI; CDS tightened in tandem with CRWV.
CNBC reports ORCL expanded its OpenAI partnership, adding GOOGL TPU, OpenAI Jalapeño chips and CBRS hardware to OCI, becoming the first hyperscaler other than GOOGL to offer TPUs.
Undelivered contract backlogs disclosed by ORCL and MSFT exceed $1.3 tn combined, with both saying demand outstrips supply.

CLS | $35.0 bn | +12.1%
Shares fell ~33% over the past month into the print; buy side had penciled FY27 EPS near $25, while guidance is $21.50. Today's Investor Day needs to clarify 2028 scale and cash pathways.
ALAB +10.5% / CRDO +10.8% / ANET +5.5% / COHR +6.5% / LITE +5.9% / AAOI +7.0% / GLW -1.1%
ALAB: Citi kept Buy, seeing PCIe 6 and Scorpio X driving per-accelerator content toward >$1,000 in the Dec qtr, with ~12% and ~21% upside to revenue and EPS vs. Street, respectively.

TSLA | $1.61 tn | +4.0%
Extended Monday's +5% rally. Bloomberg says TSLA and SPCX boards formed a special committee of independent directors to evaluate a merger, with Musk recused.
Texas DMV data show 546 Cybercabs registered, with nearly 200 added in the past week. But one research summary argues Optimus reaching 20k/week by end-2027 is unlikely, with a more plausible timeline in 2028.
Dolphin view: AI monetization is concentrated post-2027. With a formal merger evaluation, shares are trading the 'SPCX option', while autos still underpin fundamentals. (Earnings review)

AAPL | $5.07 tn | +0.9%
Launched M6 iMac and entry-level MacBook Pro. Counterpoint says iPhone 18 Pro's first three weeks of sales are 3.1% above the prior gen (China +29%, U.S. -4%); reports 11/2.
Per one research note, iPhone Duo hinge yield is ~60%, below the 85% MP bar. The capacity shift is within the pool, moving toward higher-priced models (18 Pro cuts 10–15%, 18 Pro Max adds 10–15%).
DELL +7.5% / HPE +3.6%
Server ODMs' downstream customers are mostly New Cloud, and shares tracked the New Cloud rebound.
Coca-Cola KO | $392 bn | -1.6%
Q3 organic revenue +7%, above ~4% Street. Unit case volume rose +5% for a second straight quarter, with growth almost entirely from India, China, Mexico and Brazil, and North America flat; price/mix was just +1%.
Full-year organic growth raised to at least 5% and comparable EPS growth to at least 11%, the third raise this year. But the Africa bottling deconsolidation is a larger revenue drag at ~8% vs. 5–6% expected.
Dolphin view: 7% organic with three guide-ups is a strong print for a mature staples leader. Bottler deconsolidation's 2027 drag on reported numbers should not impair valuation; prior asset-light moves have lifted multiples. (First Take)(Earnings review)(Trans)

HUBS -5.0% / ACN -4.9% / CTSH -4.5% / ADBE -4.0% / INTU -3.4%
'AI losers' fell again: UBS cut HUBS to Neutral on SMB demand softness and friction from usage-based pricing (one partner saw only ~5–10% of clients buying incremental AI quotas), trimming FY27 growth to ~13%. The market broadly says these names lack incremental long-only buyers.
NOW -2.1% / CRM -2.7%
NOW reports AH tonight.
PANW +2.9% / OKTA +2.8% / CRWD +2.4%
Cybersecurity continued higher. JP Morgan named CRWD a top pick, and buy side broadly believes attacks will get worse before they improve.
SOFI | $21.0 bn | +13.4%
Q3 revenue +44% YoY to $1.4 bn, with full-year revenue guide raised to $5.04 bn, and an early 2027 revenue guide of $6.4 bn. Rate hikes caused >$800 mn of fair value losses, mostly hedged. (Trans)

Tencent 0700.HK | $446.0 bn | -0.3% (10/27 close)
Its short-drama platform's WAU in the first week of Oct rose 44.1% vs. the first week of Sep.
BABA | $249.0 bn | 0.0%
A U.S. federal judge in California on 10/26 ordered the Trump administration to stop enforcing a ban on the Pentagon working with firms lobbying for Alibaba; shares were flat.
Zhizhipu 2513.HK | +8.9% (10/27 close)
GLM-5.5-Flash was spotted on the OpenCode model list (with parameters blank), after some institutions had expected a mid/late-Oct release in prior checks.
Pop Mart 9992.HK | -0.8% (10/27 close)
Q3 overall revenue fell 45–50% YoY, with H2 GPM down up to 2ppt vs. H1 and higher opex ratio. Overseas traffic stabilized in most markets, China is seen steady to up in Q4, and full-year growth remains positive.
The company is shifting focus to selective store openings, multi-IP mix, and membership ops. (Trans)


| Date | Event | Watch |
| Wed, Oct 28 | GEV, VRT pre-market; MSFT, GOOGL, NOW, FTNT, KLAC AH; ORCL Analyst Day; CLS Investor Day | See previews below; ORCL financing plan |
| Thu, Oct 29 | FOMC decision (02:00 Beijing); Sep PCE; AMZN, INTC, SNDK, RDDT, PINS, RBLX AH | Hike odds ~10%; see previews below |
| Mon, Nov 2 | AAPL earnings | iPhone 18 Pro first 3 weeks sales +3.1% |
| Tue, Nov 3 | AMD, ANET earnings | MI450 progress, CPU price hikes |
| Mid next week | Anthropic updates S-1 with Oct ARR | Buy-side at $75–76 bn, >$78 bn positive |
| Week of Nov 16 | Anthropic IPO | Valuation range $1.5–2.0 tn |

MSFT | AH on Oct 28
Watch: with New Cloud financing tightening, the market wants to see if MSFT can fund capex with internal FCF. The $44.9 bn Azure commitment from Anthropic has high visibility but is not a new booking, and the 60k buyouts are an incremental margin swing factor.
Dolphin watch: Azure growth (buy side ~46–47%), FY27 capex, OpenAI share within RPO, one-off costs for departures.
GOOGL | AH on Oct 28
Watch: buy side is cautious, with Search growth likely only 13–14%. Implied vol is at a 1-year low; Cloud and TPU externalization support bulls, and the 2027 capex guide will be used to test 'compute surplus' risk.
Dolphin watch: Search and YouTube ad growth, Cloud growth and backlog, capex in 2027.
AMZN | AH on Oct 29
Watch: still >12% below the Aug high, with desks favoring pre-print upside positioning. AWS is expected ~43%, channels see retail slightly better than expected in Q3, and the CEO said capacity is basically sold out for 2026–2027.
Dolphin watch: AWS growth and margin, Trainium deliveries, full-year capex (raised to $220 bn last quarter).
INTC | AH on Oct 29
Watch: New Street just upgraded to Buy, with agentic AI driving server CPU demand. The $2.3 bn Classiq deal lifted quantum-exposed names, and the market will look for foundry progress and server capacity expansion.
Dolphin watch: DC CPU revenue, external foundry customers, GPM guidance.
Recent Daily Recap
2026-10-27: Dolphin Daily | Anthropic filed, Meta's $95 bn sucks up liquidity; AI panic easing?
2026-10-26: Dolphin Daily | Musk says '200 New Clouds will die'; when does AI compute flip from scarce to idle?
<End here>
Risk disclosure and statements: Dolphin Research disclaimer and general disclosure
The copyright of this article belongs to the original author/organization.
The views expressed herein are solely those of the author and do not reflect the stance of the platform. The content is intended for investment reference purposes only and shall not be considered as investment advice. Please contact us if you have any questions or suggestions regarding the content services provided by the platform.