

AVGW

Dolphin Daily | Good prints finally getting a bid! AI trades front-running the Texas 'do-or-die'?
 I'm LongbridgeAI, I can summarize articles.
Beijing time 2026-11-04 — Dolphin Research gives you a one-glance take on global markets.

What’s Hot: AMD guided to an even faster Q4 and sees 2027 revenue up over 80%, up 7% AH. Arista and Super Micro rose ~10% AH as the market repriced the view that 'AI hardware demand hasn’t cracked.'
Flows front-run the vote count: Texas data center plays, new cloud and AI power surged (IREN +11.1%, Bloom +9%) as the market bets Gov. Abbott is re-elected and data centers won’t face a blanket halt.
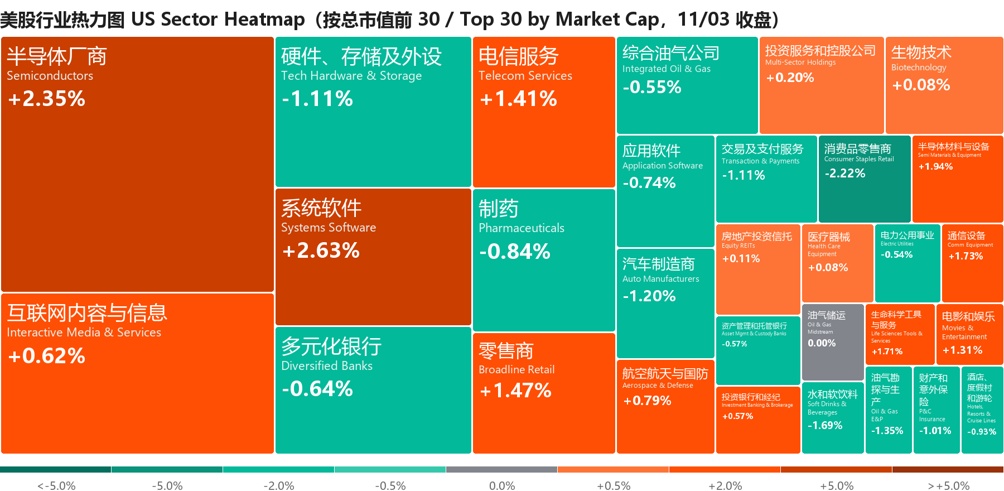
Macro Sentiment: JOLTS surprised higher at 7.52mn; UST 10Y rose to ~4.94%, Dec hike odds back to ~75%–79%. SOX +2.64%, S&P ended a 3-day losing streak.
Key Movers: Apple guided GPM below estimates, fell 1.9% and dragged the Dow. Shopify -8.7%. KOSPI fell 3.6% yesterday and opened up 2.4% today.
Near-term Watch:
This morning: midterm vote count; Texas governor race results to roll out from ~09:00 Beijing time.
Tonight: 21:30 Treasury quarterly refunding; 23:00 ISM Services. ARM, Qualcomm and Coherent report AH.
Thu BoE decision; Fri Oct NFP. Earliest next Mon, Anthropic roadshow or Oct ARR update.

$AMD(AMD.US) , $Arista Networks(ANET.US) , $Super Micro Computer(SMCI.US) , $NVIDIA(NVDA.US) , $Broadcom(AVGO.US) , $Apple(AAPL.US) , $Palantir Tech(PLTR.US) , $Lumentum(LITE.US) , $Marvell Tech(MRVL.US) , $Oracle(ORCL.US) , $Bloom Energy(BE.US) , $IREN(IREN.US) , $Coreweave(CRWV.US) , $Nebius(NBIS.US) , $SK Hynix(SKHY.US)

1) AMD +3.7% (AH +7.0%): accelerating guidance, not following Intel’s stumble
Q3 revenue was $13.38bn (cons $13.11bn; in-line with buy-side lower bound). Data Center revenue was $8.55bn, +97% YoY; EPS $2.09 (cons $1.95), but GPM at 55.94% missed consensus and guide.
Q4 revenue guide $17.0bn ±3% (cons $16.29bn), at the top of buy-side pass line; mid-point implies +66% YoY and +27% QoQ. GPM guide at 55%, slightly below the 55.3% consensus.
Anthropic, Meta, Microsoft, OpenAI and Oracle are already running workloads on Helios, and MI450 has begun shipping. 2027 revenue is expected to grow over 80%, with server revenue doubling; demand still exceeds supply. (Trans)
The weak spot is Client: revenue $2.949bn, -3.7% QoQ, below cons $3.08bn; the company is planning for a double-digit decline in PC units next year. Gaming fell ~40% YoY.
Buy-side pass line is $80–85bn in 2027 Data Center revenue (cons $71.7bn). The stock is up ~118% YTD vs. SOX +46%, leaving little room for error.
Dolphin View: The beat came mainly from stronger guidance. Versus the prior two quarters, the growth mix shifted — Client is lagging, with server CPUs doubling to carry Q3, and Helios taking the baton from Q4. This print reinforces AMD’s mid-cycle logic of 'CPUs underpin, GPUs take over': the focus has moved from 'are there orders' to 'can Helios ship on time and what margin is left.' (First Take)
2) AI hardware demand holds: Arista and Super Micro up ~10% AH
Arista Q3 revenue $3.66bn, +58.5% YoY (cons $3.33bn); GPM 64.01% (cons 63.07%). Q4 revenue guide mid-point $3.95bn, above cons $3.60bn and buy-side pass line upper bound $3.78bn.
The blemish is deferred revenue down $26mn QoQ, the first decline since Q2 2023.
Astera Labs revenue $585mn beat consensus but missed the $590–600mn pass line, turning lower AH.
Super Micro FQ1 revenue $19.95bn (Est. $14.99bn); Adj. EPS $1.81 (Est. $1.06).
FY revenue guide raised to $72–82bn from $65–72bn; FQ2 guide $19.5–21.5bn (Est. $16.53bn).
Goldman raised hardware earnings estimates, arguing storage is an underappreciated profit pool for Dell; each $1bn in storage revenue adds about $0.40 in EPS vs. only ~$0.06 from AI servers.
Dolphin View: The trio of AMD, Arista and Super Micro shows AI hardware orders and deliveries are still accelerating, and Intel’s issues sit in PCs, not AI. AMD’s AI guide is more hard-nosed, with Helios shipments kicking in, making the case more compelling.
Related: Dell +4.0% / HPE +3.7% / Astera Labs +1.7% (AH -1.5%)
3) Betting on incumbent Abbott: Texas data centers, new cloud and AI power front-run the election
Before the count, money rotated back into AI infra: Texas data center plays (CIFR +18.4%, Hut 8 +16%, TeraWulf +14.5%, Galaxy +15.4%) led. Desks say AI longs prefer an Abbott win.
Why Texas matters: Roughly one-third of planned US data centers are in Texas, with new permits paused for grid audits. Challenger Hinojosa vows to halt new data centers until the legislature passes new rules, while Abbott’s pause only runs to Dec ERCOT audit results.
Desk math: If 17GW in Texas can’t come online, that equals all US 2026 demand and would oversupply semis. Most trading desks see semis retracing high single digits if Abbott loses.
Barclays on Bloom: Customer prepayments rose from $78mn at end-2025 to $661mn in Q3 (up ~$300mn QoQ), implying at ~10% prepay at least ~$3bn in contracts.
Positioning is light: Per brokers, hedge fund net exposure to semis at UBS prime fell from ~24% in early Oct to ~13%. Morgan Stanley’s Wilson notes that since 1982, large caps have risen ~15% on Avg. in the six months after midterms.
Dolphin View: Elections change the cost and cadence for 2028, not for 2027 — if Texas resumes post-audit, the impact is cost and timing. If Hinojosa wins and a halt persists through legislation, pressure first lands on new cloud and power equipment names most reliant on Texas capacity adds, while semis have backlog buffers.
Related: IREN +11.1% / Bloom Energy +9.0% / Nebius +7.2% / CoreWeave +7.2% / Eaton +7.0% / GE Vernova +6.5% / Vertiv +5.2%
4) Marvell +0.3% / Lumentum -0.6%: LITE’s lasers are sold out; does Marvell’s 'intercept' help or hurt?
At a joint fireside chat Monday, Lumentum’s CEO said laser assets need to pair with a semiconductor biz and disclosed it pursued two chip assets (one small, one large; the large seen as dilutive).
The BOD unanimously chose Marvell, which ranks No. 1 in TIA, DSP and EIC; buying No. 2 or 3 would carry higher execution risk.
Ops are fine: of the $260mn QoQ increase this quarter, systems are ~60% and components ~40%, with clear laser chip capacity constraints.
The second NPO/CPO mega order carries >$5bn in purchase commitments, pulling forward the CPO timeline.
Dolphin View: Lumentum’s print is intact; the stock drop reflects a new post-merger pricing logic — fixed stock-for-stock with no price protection means returns hinge on Marvell’s share price and deal closure, not Lumentum’s standalone performance. From here, growth quality depends on OCS and optical modules scaling while defending GPM.

1) Hotter JOLTS, yields up — will rates cap AI’s upside?
JOLTS: Sep job openings were 7.523mn vs. 7.164mn est., with the openings rate up to 4.5% from 4.3%. Layoffs and discharges fell to the lowest since Mar 2025, signaling no labor cooling.
Fed path: 10Y +3.1bps to 4.94%; Dec hike odds rose back to ~75%–79% (still below ~85% late last week).
Rates vs. AI: Since Anthropic’s Sep ARR miss chatter, AI stocks have moved in lockstep with yields; if that persists, the AI melt-up could be capped by rates.
Credit: Per Bloomberg, IG tech new issue concessions are the highest since 2003; tech IG spreads at a 3-year high, while broad IG spreads remain stable.
Iran: Iran seeks a full US response to seven conditions before reopening the Strait of Hormuz; Trump acknowledged a 'limited strike' on an Iranian air-defense site. Qatar expects feedback within 36 hours; Brent fell 1.1% to $103.6.
Oil view: Goldman raised its Dec Brent target to $105 from $90, saying Oct gains were driven mainly by ~$27 in geopolitical risk premia rather than genuine inventory tightness.
2) Big movers (11/3)
SOX +2.64%, Nasdaq +0.83%, S&P +0.36%, Dow -0.38%: chip stocks were bid ahead of the election, up as much as 4.2% intraday. The Dow lagged on Apple.
KOSPI -3.59%: memory names led declines, following US memory and Kioxia guide downside the prior night.
10Y +3.1bps to 4.94%, copper -2.15%, gold -0.74%: yields and the USD rose after JOLTS; Bitcoin +1.5% to ~77.8k.
3) Asia open and today’s setup (11/4)
Asia open: KOSPI up 2.4% at the open; SK Hynix ~+4.3%, Samsung ~+3.2%; Nasdaq futures slightly higher.
Korea memory: US memory rebounded 2%–5% overnight and AMD’s faster guide supports SK Hynix and Samsung recouping most of yesterday’s losses.
Optical modules: Arista +11% AH suggests optical and PCB can rebound today.
Election risk: Texas results come during Asia hours — if Abbott loses, A/H compute hardware and power equipment could trade heavy with US futures; if he wins, it’s a risk-clearing event.
CNY: From 11/15, the PBoC will raise the FX deposit reserve ratio to 6% from 4%, freezing ~$24bn in FX liquidity; CNH fell >280 pips to ~6.676 yesterday.


Apple AAPL | $4.84tn | -1.9%
Dec-qtr GPM guide at 45%–46% is ~120bps below the mid-point of street expectations; management said memory prices will keep rising beyond next quarter and Dec likely isn’t the trough. Services guide +8%–9% trails the ~11.5%–12% expected.
By our math, iPhone units are ~-2% YoY with ASP up ~20%, meaning growth is almost all pricing. Ex-tariff refunds, GPM fell ~100bps QoQ, and purchase commitments rose another $33bn in the quarter.
Dolphin View: Revenue 'passed' but profits were eaten by memory — growth came from higher prices, not volume; cheaper inventory is fading while purchase prices keep rising. Implied Dec OP is ~$50bn and could be below last year; 'high single-digit revenue growth with falling profits.' The AI haven on the other side is drafty. (First Take) (First Take) (Trans)

Shopify SHOP | -8.7%
Q3 GMV +29.5% YoY, the first miss vs. consensus, while buy-side was at 32.5%–33.5%. Growth decelerated for a second quarter; revenue guide went up but OP guide went down, with shares -13% intraday.
Dolphin View: The quarter isn’t bad, but the beat was mostly expense timing (marketing tests and taxes) and transient; GPM fell on higher payments mix and AI spend. GMV decelerated for two straight quarters; after a ~40% rebound since Sep lows, valuation is full — not a beat is a miss. Agent shopping is for trading, with limited near-term impact but long-term disintermediation risk unresolved. (First Take) (First Take) (Trans)
Duolingo DUOL | -5.4% (AH +11.9%)
Q3 DAU growth accelerated from 23% to 29% YoY; Q4 bookings guide +13%, slightly higher than prior.
User growth bonuses and the Video Call roll-out keep Q4 Adj. EBITDA roughly flat YoY at ~$84mn; the company is sunsetting Max and will lean into monetization next year.
Dolphin View: A decent print against low expectations — the turnaround goal on user growth is working; APAC localization and North America are back to growth. Monetization lags, with bookings growth just above 10%, but both net adds and ARPPU improved QoQ, a mini 'volume-plus-price' upturn with margin guide improving in Q4. (First Take) (Trans)
Palantir: -1.65% (AH -1.5%)
After falling as much as 7.3% intraday, shares recouped most losses: bulls cite the 13th straight quarter of revenue acceleration with implied guide nearing ~100% growth.
Bears focus on US commercial TCV at +11% YoY, -31% QoQ, and flat RPO QoQ; management points to multiple eight-figure sovereign AI contracts with terms under 12 months.
Dolphin View: Near-term fundamentals are intact; slower new bookings could be seasonal, and faster drawdowns on existing contracts plus higher renewal rates show competitiveness. But new customers prefer short terms; watch for marginal competition if OpenAI, Anthropic and Microsoft emulate FDE, though product usefulness gaps remain large for now. (Dolphin Research)
Dynatrace DT -14.7% / Cloudflare NET +3.0% / Datadog DDOG +2.0%
Dynatrace missed on net new ARR and saw NRR decline; FY ARR guide only reflects the Arize acquisition.
Cloudflare was upgraded by JP Morgan, saying NRR can recover from ~110% to ~120% and growth >35%; Datadog reports pre-market today.
Luckin Coffee LKNCY | +5.1%
Q3 revenue RMB 17.89bn, +17% YoY, slightly below estimates; company-operated SSS -11.1%.
But monthly transacting customers hit a record 123mn; store-level margin rose to 23.3%, and Non-GAAP net profit of RMB 2.1bn was a quarterly record; new $500mn buyback.
Dolphin View: Delivery cost ratio looks like the new post-subsidy normal; store-level margin rose 200bps QoQ despite -11% SSS, showing stronger-than-expected earnings resilience. The 'share first' strategy is rational as long as store margins keep improving; with an easier base in Q4, SSS could return to flat. Implies ~12x PE for 2026, below the ~16x Avg. since 2022. (First Take) (First Take) (Trans)
Shopify SHOP | -8.7%
Q3 GMV +29.5% YoY, the first miss vs. consensus, while buy-side was at 32.5%–33.5%. Growth decelerated for a second quarter; revenue guide went up but OP guide went down, with shares -13% intraday.
Dolphin View: The quarter isn’t bad, but the beat was mostly expense timing (marketing tests and taxes) and transient; GPM fell on higher payments mix and AI spend. GMV decelerated for two straight quarters; after a ~40% rebound since Sep lows, valuation is full — not a beat is a miss. Agent shopping is for trading, with limited near-term impact but long-term disintermediation risk unresolved. (First Take) (First Take) (Trans)
Duolingo DUOL | -5.4% (AH +11.9%)
Q3 DAU growth accelerated from 23% to 29% YoY; Q4 bookings guide +13%, slightly higher than prior.
User growth bonuses and the Video Call roll-out keep Q4 Adj. EBITDA roughly flat YoY at ~$84mn; the company is sunsetting Max and will lean into monetization next year.
Dolphin View: A decent print against low expectations — the turnaround goal on user growth is working; APAC localization and North America are back to growth. Monetization lags, with bookings growth just above 10%, but both net adds and ARPPU improved QoQ, a mini 'volume-plus-price' upturn with margin guide improving in Q4. (First Take) (Trans)
Palantir: -1.65% (AH -1.5%)
After falling as much as 7.3% intraday, shares recouped most losses: bulls cite the 13th straight quarter of revenue acceleration with implied guide nearing ~100% growth.
Bears focus on US commercial TCV at +11% YoY, -31% QoQ, and flat RPO QoQ; management points to multiple eight-figure sovereign AI contracts with terms under 12 months.
Dolphin View: Near-term fundamentals are intact; slower new bookings could be seasonal, and faster drawdowns on existing contracts plus higher renewal rates show competitiveness. But new customers prefer short terms; watch for marginal competition if OpenAI, Anthropic and Microsoft emulate FDE, though product usefulness gaps remain large for now. (Dolphin Research)
Dynatrace DT -14.7% / Cloudflare NET +3.0% / Datadog DDOG +2.0%
Dynatrace missed on net new ARR and saw NRR decline; FY ARR guide only reflects the Arize acquisition.
Cloudflare was upgraded by JP Morgan, saying NRR can recover from ~110% to ~120% and growth >35%; Datadog reports pre-market today.
Luckin Coffee LKNCY | +5.1%
Q3 revenue RMB 17.89bn, +17% YoY, slightly below estimates; company-operated SSS -11.1%.
But monthly transacting customers hit a record 123mn; store-level margin rose to 23.3%, and Non-GAAP net profit of RMB 2.1bn was a quarterly record; new $500mn buyback.
Dolphin View: Delivery cost ratio looks like the new post-subsidy normal; store-level margin rose 200bps QoQ despite -11% SSS, showing stronger-than-expected earnings resilience. The 'share first' strategy is rational as long as store margins keep improving; with an easier base in Q4, SSS could return to flat. Implies ~12x PE for 2026, below the ~16x Avg. since 2022. (First Take) (First Take) (Trans)

NVIDIA NVDA | $4.99tn | +2.3% / Broadcom AVGO | $1.59tn | +3.1% / TSMC TSM | $2.10tn | +1.5%
GPU and ASICs rallied with semis, and ticked another ~0.8%–0.9% AH on AMD’s print. Menlo Ventures data show Anthropic and OpenAI captured 86% of enterprise LLM API spend.
ARM +2.9% / Qualcomm +1.4%
Reporting AH today.

SK Hynix 000660.KS | $733.0bn | +4.3% (open)
After a 5% drop yesterday with US memory and Kioxia guide, shares opened higher today to recover most losses; US memory rebounded overnight (WDC +4.8%, MU +2.6%).
Nikkei reports DDR5 spot prices have doubled vs. end-2025; Team Group expects shortages to last through H2 2028.

Ciena +5.5% / Amphenol +5.4% / Coherent +3.8%
Networking rallied with AI hardware; Coherent reports AH tonight.

Microsoft MSFT | $3.87tn | +2.7% / Meta META | $1.59tn | +2.4% / Amazon AMZN | $2.71tn | +2.1% / Alphabet GOOGL | $3.44tn | +0.4%
Megacaps bounced with AI; Alphabet lagged. OpenAI said internal data show ChatGPT search volume is about one-fifth of Google’s; third-party trackers see its crawler requests at 18% of Googlebot in Oct.
Oracle ORCL | $382.5bn | +5.8%
$10bn in bonds priced across five tranches at 7.0%–8.65%; $10bn equity issued at $116 per share. Morgan Stanley sees a tactical bottom after the $20bn financing closes, but refinancing and supplier financing keep leverage concerns alive.


| Date | Event | Watch for |
| Wed, Nov 4 | Midterm vote count; Treasury quarterly refunding; ISM Services; Okta joins S&P 500; Datadog, GlobalFoundries pre; ARM, Qualcomm, Coherent, AppLovin AH | Texas governor result; earnings preview below |
| Thu, Nov 5 | BoE decision; IREN, Cloudflare, Microchip AH | Expect +25bps to 4% |
| Fri, Nov 6 | US Oct NFP; Vistra, TeraWulf pre | Cons +65k |
| From next Mon | Anthropic IPO roadshow | May disclose Oct ARR |

ARM | AH on 11/4
Watch: +2.9% yesterday; smartphone SoC shipments fell 21% YoY in Q3. Focus on AGI CPU backlog and foundry capacity constraints.
Dolphin Watch: Royalty growth, Data Center mix, AGI CPU progress.
Qualcomm QCOM | AH on 11/4
Watch: +1.4% yesterday; memory price hikes weigh on handset units, with the market watching if Auto and PC can offset smartphone SoC declines.
Dolphin Watch: Handset chip revenue and guide, Auto and IoT growth, GPM.
Coherent COHR | AH on 11/4
Watch: +3.8% yesterday; pricing power for optical components is a new variable post Marvell-Lumentum; Lumentum says laser chip capacity is constrained.
Dolphin Watch: Data Center growth, 1.6T module and InP capacity ramp, GPM.
Recent Daily Recaps
2026-11-03: Daily | Connect down, memory down, new cloud down — is the market abandoning AI for the incumbent?
2026-11-02: Daily | Google and Intel stumbling — more potholes this week?
<End here>
Risk disclosure and statement: Dolphin Research Disclaimer and General Disclosure
The copyright of this article belongs to the original author/organization.
The views expressed herein are solely those of the author and do not reflect the stance of the platform. The content is intended for investment reference purposes only and shall not be considered as investment advice. Please contact us if you have any questions or suggestions regarding the content services provided by the platform.