

CRDU

Dolphin Daily | Elon Musk warns '200 new clouds will die'; when will AI compute flip from shortage to idle?
 I'm LongbridgeAI, I can summarize articles.
Good morning! It is Beijing time 2026-10-26. Dolphin Research gives you a one-glance take on global markets.

Trading focus: Over the weekend, Elon Musk said the bond market has effectively shut for companies with revenue only from AI data centers. He expects 200+ new clouds to ‘die and consolidate’. The NBIS CEO also said the debt market for new clouds closed starting last week.
On Fri, SPCX discussed plugging into 80k base stations, aiming to become the fourth largest US operator. T -8.0%, TMUS -7.7%, tower CCI +9.1%. Cybersecurity stocks rallied 4%–8% on Evercore channel checks and a PHP exploit.
Macro mood: Rising oil overshadowed AI trades. The Dow -1.2%, S&P -0.5%, Nasdaq 100 flat. WTI +3.8% to $103, Brent up 6% on the week.
US Oct PMI output prices hit a four-year high. The 10Y UST +4bps to ~4.99%.
Key movers: BE missed tape action despite beats on results and guide, -11.2%. CRDO -9.5%.
SK Hynix ADR +4.0%, MU +2.5%, TSM +1.5%. AAPL hit an intraday ATH, briefly topped NVDA by mkt cap, then closed -0.1%.
Near-term watch: At Asia open, look to Korea memory and HK AI model names. MSFT and GOOGL report Wed night, FOMC early Thu, AMZN and INTC Thu night.
Sep PCE on Thu. Mega-cap 2027 capex guides will directly answer whether compute will sit idle.

$SpaceX(SPCX.US) , $Coreweave(CRWV.US) , $Nebius(NBIS.US) , $Microsoft(MSFT.US) , $Alphabet - C(GOOG.US) , $Amazon(AMZN.US) , $NVIDIA(NVDA.US) , $Bloom Energy(BE.US) , $Western Digital(WDC.US) , $SK Hynix(SKHY.US) , $CrowdStrike(CRWD.US) , $Palo Alto Networks(PANW.US) , $Oracle(ORCL.US) , $Credo Tech(CRDO.US) , $MINIMAX-W(00100.HK)
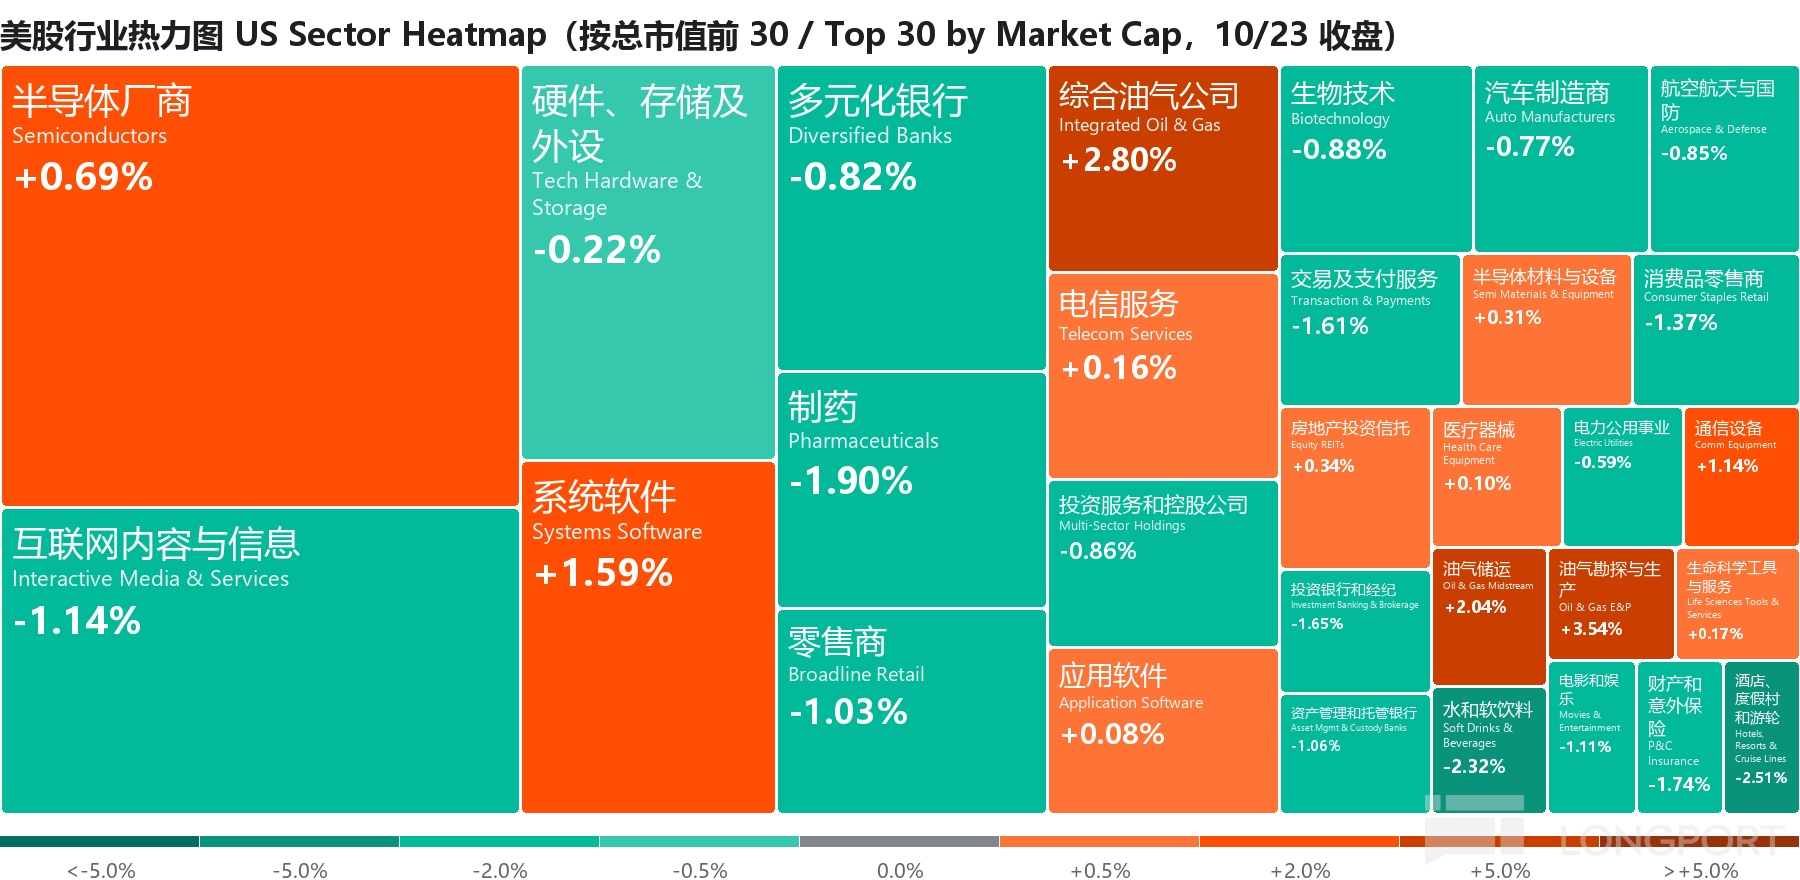
Performance window: US stocks and global assets are vs. the prior trading day at the 10/23 Fri close.

1. ‘New clouds will die in droves’: after financing shuts, is compute scarce or idle
On Sun, Musk replied to Chamath that in recent weeks the bond market has ‘almost completely’ closed to companies without revenue beyond AI data centers. SPCX secured $40bn of GPU debt on the back of IG ratings plus Starlink and launch revenue.
He expects 200+ new clouds to ‘die and consolidate’. The NBIS CEO said ‘the debt market for new clouds closed last week’.
Chamath at Social Capital went further: hyperscalers will prioritize in-house compute, routing third-party demand back to their own models. By 2027 there will be ‘a lot of partially idle compute’, more than currently expected.
The credit side is already pricing it: global IG credit spreads widened to 129bps, the widest since May 2025. Some CRWV bonds trade near 80 cents on the dollar with yields ~15%, while chip-collateralized loans still hover near par.
Per Semafor, the safer tranche in SPCX’s $40bn chip financing yields ~7.75%, over 100bps above its outstanding bonds. Lower-rated pieces yield ~8.3%.
The counterview: AWS’s CEO says large blocks of compute are sold out for 2026 and ‘basically sold out’ for 2027. Some emerging labs say H100/B200/B300 rentals have risen 2–3x, and X users cite H200 rentals up 160% YTD.
Demand-side data supports this too: per a16z, OpenRouter’s weekly tokens rose from ~6 trillion to 165 trillion, ~27x. H200 and B200 rents are 143% and 111% above standard depreciation curves, respectively.
SemiAnalysis estimates ex-China incremental DC IT capacity will reach 51.2GW in 2027, more than doubling vs. 2026. Over 24.3GW is in late-stage construction, and the next bottlenecks are chips and HBM.
But cracks are showing in deliveries: reports say AMZN’s NVDA GB300 racks are stuck in cross-docks due to powerless sites, with ~$5bn received in Aug alone. NVDA has pledged and invested over $170bn and is helping customers finance.
Why labs’ ARR matters: estimates suggest OpenAI and Anthropic account for about half of total AI ARR. They are the customers for the highest-risk new-cloud capacity, representing ~38% of 2027 AI capex.
The financing chain: labs sign long-term compute contracts (Anthropic ~$45–52bn, ~80% non-cancellable). Hyperscalers use take-or-pay leases with new clouds to keep debt off balance sheet, borrowing at roughly SOFR+300 when backed by AWS.
Yet for capacity leased to labs, loan rates have hit 13%–15%: Volta’s cluster for Anthropic carries a 12% coupon, issued at 95 cents, implying ~15%.
The per-GW per-year math: build cost is ~$5bn (chips $3.3bn with six-year depreciation), and rent is ~$1.2bn. If you borrow $4bn, ~7% cheap debt leaves ~$0.8bn profit, while ~14% expensive debt loses ~$2bn.
Dolphin take: SPCX moves from ‘rocket man’ to ‘landlord’. The new trillion-dollar pie requires leverage. With financing tightening, compute players with cash-flow parents will absorb weakly backed new clouds, and during supply-demand mismatch, low funding costs plus fast compute delivery are the edge.(Earnings take)
2. SPCX eyes the ‘4th operator’: telcos hit, towers benefit
Bloomberg says SPCX is negotiating with at least one towerco to plug into ~80k US sites, prepping to launch a wireless operator biz. On Fri, T -8.0%, TMUS -7.7%, VZ -1.2%, CCI +9.1%, AMT +4.1%.
BNP Paribas calls this a clear positive for towers and a negative for incumbents. In Europe, spectrum and tower constraints make MVNO deals more likely, with far less fundamental risk than in the US.
SPCX’s ground game has three steps: ~$17bn to buy EchoStar spectrum, an ~$8bn purchase of Grain’s 800MHz in Oct, and tower talks naming CCI.
The Big Three formed a satellite JV, and DOJ plus FTC have launched antitrust reviews.
Dolphin take: Direct-to-cell plus terrestrial fill-in turns Starlink from ‘coverage filler’ to ‘user grabber’. But spectrum, regulation, and capex are not yet locked, so the hit to operators shows up in multiples first.
3. Broad cyber rally: AI expands attack surface, budgets shift to security
CRWD +8.2%, PANW +7.2%, ZS +7.3%, NET +7.3%, OKTA +5.8%, FTNT +4.1% led Fri’s gainers.
The catalyst was Evercore channel checks pointing to stronger security budgets, with spend flowing to data and AI security, identity, and cloud. Deutsche Bank also sees rising AI token usage lifting security demand.
Backdrop: an AI-assisted PHP RCE exploit this week. About 39.7mn exposed services globally and 12.8mn in the US, with only ~1.34mn patched, temporarily taking some government services offline.
BofA CIO survey shows software budgets +5.3% in 2027 and cyber +6.9%. Yet only 17.2% of CIOs report measurable enterprise AI returns.
The offense is AI-augmented too: per The Information, hackers used Claude and Grok to build autonomous agent networks, hitting 400+ financial institutions.
Dolphin take: AI amplifies both the attack surface and defense budgets. Security is one of the few software areas where ‘the more AI you use, the more you need’.
4. Model price war: Anthropic’s GPM becomes OpenAI’s opening
Per The Information, OpenAI gave Replit 30%+ discounts on a contract worth over $100mn per year.
Replit shifted most AI spend from Anthropic to OpenAI. Anthropic had halted discounting earlier.
Within Rippling’s internal coding load, Anthropic’s share fell from 57% in May to 18%, while OpenAI rose from 16% to 52%. Some models from both dropped as much as 80% in price over a few months.
China models add pressure: Kimi K3.1 Pro launched, topping GPT-6 Astra in coding-agent tests at roughly one-fifth the cost, with weights opening before Nov 4.
Bloomberg reports DeepSeek and MiniMax were cleared to deploy models overseas.
Dolphin take: Compute rentals are rising while models engage in price wars, squeezing model GPM expectations. That may not be great for model valuations but is constructive for CSP earnings, as SPCX’s compute upside shows.

1. Oil trumps AI: inflation worries back in focus
PMI: US Oct composite PMI flash at 57.6, slightly below Sep but near five-year highs. Manufacturing 56.0, a 53-month high, services 57.9, with the steepest rise in selling prices since Aug 2022.
USTs and liquidity: 10Y +4bps to ~4.99%, still below 5%, down ~8bps on the week. 2Y +4bps to ~4.68%.
Oil and geopolitics: Trump floated a limited strike on Iran, and Iran said two VLCCs hit mines in the Hormuz Strait. WTI +3.8% to $103.27, Brent +3.1% to $116.72 and +6% on the week.
Fed path: FOMC on Wed (early Thu Beijing). Consensus expects no change, with focus on inflation components and rate-hike language.
This week’s data: Tue new home sales, Thu Sep PCE. A firmer PCE plus oil will cap room for long-end yields to retrace.
2. More volatile assets (10/23)
Dow -1.23%, S&P -0.52%: Higher oil weighed on defensives and consumer. Nasdaq 100 flat, SOX +0.4%.
WTI +3.8% to $103: Mideast risk plus pre-weekend short covering. The US DOE authorized emergency exchanges of up to 400k bbls from the SPR.
Gold -1.3% to ~$3,991: Lost $4,000, down ~4% on the week. HSBC cited margin calls from equity declines forcing gold sales.
VIX +2.2% to 19.5: Cautious but not disorderly.
3. Asia open and today’s setup (10/26)
Asia open: Nikkei opened -0.4% then turned +0.2%. KOSPI opened -0.9%, now -0.1%, KOSDAQ opened -1.3%. Nikkei CME futures +0.2%, Nasdaq and S&P futures +0.1% to +0.2%.
In Japan/Korea single names, SK Hynix opened +0.2%, now +1.6%, Samsung opened -0.9%. SoftBank opened -2.8% then turned +1.9%. Kioxia opened -1.8%, Tokyo Electron -1.6%, Advantest -0.4%.
Memory chain setup: SK Hynix ADR +4.0%, MU +2.5%, plus Korean media says Hynix may fund a special dividend from selling its Kioxia stake. Expect a firmer open for Korea memory.
New-cloud and compute-chain risk: Musk’s weekend ‘many new clouds will die’ comment may weigh on HK and A-share compute rentals and IDC sentiment.
Frontier models and price war: Kimi K3.1 Pro launch and DeepSeek/MiniMax cleared for overseas may keep HK model names in focus, but price cuts cap monetization hopes.


CRWV -2.5% / IREN -2.4% / NBIS -0.3%
CRWV trades at ~2.2x 2027 revenue and 3.8x EBITDA, toward the low end of AI infra peers.
Dolphin take: New-cloud businesses are essentially financing-driven. Once the window shuts, the valuation anchor shifts from ‘growth’ to ‘can you borrow’.(Original note)
MSFT|$3.89tn|+0.7%
BofA expects FQ1 Azure cc +44.8% and commercial RPO of $678bn, with FY27 capex at ~$221bn (+52%). 76.7% of CIOs are using or plan to use Copilot. Earnings on 10/28.
Dolphin take: MSFT’s star is rising again. As financing tightens, cash-flow-rich hyperscalers that can self-fund capex become safe havens within AI.(Earnings take)
AMZN|$2.68tn|-1.0%
The AWS CEO says 2026 capacity is largely sold out, 2027 ‘basically sold out’, and most of 2028 is booked, with AI ARR above $25bn.
Contract backlog rose $132bn QoQ to $496bn, excluding Anthropic’s $100bn+ deal. Rolling FCF turned to -$7.6bn.
Some surveys indicate early cloud renewals into Q3-end, especially at AWS. Earnings on 10/29.
META -1.0% / ORCL +0.5%
META fell over 9% on the week: its 14C shifted language from ‘may finance’ to ‘expects to finance’, and Q3 FCF turned negative to -$2.1bn. ORCL edged higher.

SPCX|$2.00tn|+1.9%
SPCX filings show Anthropic pays $1.25bn per month for compute, with either side able to terminate on 90 days’ notice.

CRWD +8.2% / PANW +7.2% / OKTA +5.8% / FTNT +4.1%
Mizuho raised CRWD’s PT from $250 to $275.
DDOG +4.6% / SNOW +3.7%
DDOG: Wells’ large-customer checks show most expect 5%+ spend growth in 2026, with 92% saying AI is lifting observability spend.
The Information said DDOG bid nearly $4bn for Upwind, while Israel’s CTech denied an offer exists.

BE|$57.1bn|-11.2%
Q3 revenue $1.24bn (+138% YoY), ~15% above consensus. FY revenue guide hiked for the third time this year to $4.4–4.6bn, with the midpoint ~11% higher than prior.
Negatives: FY GPM guide held at ~34%, implying flat Q4 GPM. OP cash flow was -$27mn and FCF -$181mn, with backlog undisclosed.
Policy risk: per SemiAnalysis, Texas TCEQ’s freeze has expanded to air permits, affecting 8.7GW across six self-generation DC campuses. On-site power that bypasses grid queues faces limits, creating a new timing variable for BE demand.
Dolphin take: Such strong results still sold off with the tape, reflecting extreme fear toward low-GPM, high-multiple AI upstream equipment. In a risk-on turn, these AI energy names likely lead the rebound.(Earnings take)(First Take)

WDC|$128.6bn|-3.0%
Sep-qtr revenue $4.38bn and EPS $4.64 vs. $4.14bn and $4.10 consensus. Dec-qtr guide: revenue $5.1bn and GPM 60%–61% vs. Street 57.4%.
Negatives: management said capex will be ‘slightly above’ the 4%–6% range for the next two years and later indicated 7%–8%. EB shipments +22%, the second straight quarter below the 25% target, and cost per TB fell only ~4.5%.
Bears fear WDC supply +35%, STX +30%, and Toshiba doubling capacity, ending shortages by 2028. Shares are down 50%+ from the Jun peak.
Across 23 brokers, the Avg. PT is ~$670 vs. the current ~$344, nearly a 2x gap. The debate centers on whether 2027 pricing can hold.
Dolphin take: The price-up thesis is playing out, but once expansion commentary loosens, the market discounts ‘when does the shortage end’. Memory valuations have shifted from current prints to 2027 supply-demand.
SK Hynix SKHY (US ADR)|+4.0%
Korean media say Hynix may fund a ~$12bn special dividend from selling its Kioxia stake. Its unit Solidigm paused IPO evaluation, which the company said is unrelated to growth prospects. Results due this week, with focus on HBM pricing and capital returns.
MU +2.5% / SNDK -1.8% / STX -1.8%
MU’s Taoyuan union ended a 24-hour warning strike, but 1,633 of 1,637 voters rejected the revised pay plan. Talks resume on 10/27.

NVDA|$5.09tn|-0.6%
Intraday, AAPL briefly surpassed NVDA by mkt cap. NVDA, INTC, and AMD have prepaid over TWD 100bn to lock advanced IC substrate capacity in Taiwan, per local media.
TSM|$2.17tn|+1.5%
Semis ticked higher, with SOX +0.4%.
AVGO -0.5% / AMD +1.7% / INTC +1.7% / MRVL +2.3%
Chip names edged up. On X, chatter that Jim Cramer called a ‘data center collapse’ and dumped AVGO reads as a sentiment tell.

CRDO|-9.5%
MaxLinear said it will enter the AEC market where CRDO holds 93%–99% share. Third-party checks also flag potential delays in hyperscaler deployments of high-bandwidth cables, sending the stock down ~19% over two days.
TTMI|+8.4%
Rebounded after a ~28% drop the prior day on DC guide misses and project delays.

AAPL|$5.07tn|-0.1%
Intraday ATH with mkt cap briefly topping NVDA for No.1 globally, but it faded to close lower. Taiwan media cited strong iPhone Duo demand, with suppliers asked to lift orders by 30%.
The other side: multiple market reports of foldable iPhone screen cracks. An OLED-touch MacBook Pro launches Wed, with earnings on 11/2.

MiniMax 0100.HK +16.7% / Zhipu 2513.HK +8.3% (10/23 HK close)
Bloomberg says MiniMax and DeepSeek were approved to deploy models overseas after Beijing’s new AI export registration process.


| Date | Event | Focus |
| Tue 10/27 | GLW (pre), STX (post) Q3; US Sep new home sales; MU Taoyuan union talks resume | Fiber demand, HDD supply-expansion tone |
| Wed 10/28 | MSFT, GOOGL, NOW Q3 (post); GEV, VRT, APH (pre); AAPL product launch | See earnings previews below |
| Thu 10/29 | FOMC decision (02:00 Beijing); Sep PCE; AMZN, INTC, SNDK Q3 (post) | Rate-hike language; see previews below |
| This week | SK Hynix Q3; SPCX $40bn chip financing pricing | HBM pricing, special dividend; cost of capital |
| This week | Anthropic S-1; ORCL Analyst Day financing plan; OpenAI ~$30bn financing expected around 10/30 | Formal reads on AI Lab ARR and funding costs |
| 11/2 | AAPL earnings | GPM impact from memory price hikes |

MSFT|post 10/28
Watch: With new-cloud financing shut, the market wants MSFT to show OCF can cover capex and that third-party compute is routed back to Azure. The degree of FY27 capex uplift is the debate.
Dolphin focus: Azure growth (BofA est. FQ1 cc +44.8%), commercial RPO and OpenAI exposure, FY27 capex framing.
GOOGL|post 10/28
Watch: Third-party signals of ad slowing vs. cloud and TPU externalization growth. The 2027 capex guide will be used to test ‘compute oversupply’ fears.
Dolphin focus: Search and YouTube ad growth, Cloud growth and backlog, 2027 capex.
AMZN|post 10/29
Watch: The CEO just said 2026–2027 compute is basically sold out, and markets want to see that flow through to AWS acceleration. Deutsche Bank sees Q3 AWS +41% and 2027 capex at ~$330bn.
Dolphin focus: AWS growth and margin, Trainium deliveries, full-year capex (raised to $220bn last quarter).(Earnings call Trans)
Recent Daily Recaps
2026-10-23: Daily Recap | Risk Off! AI infra cleared out
2026-10-22: Daily Recap | 13GW rescue, Meta burn-first-earn-later: bottom or bull trap for AI trades
<End here>
Risk disclosure and statement: Dolphin Research disclaimer and general disclosures


The copyright of this article belongs to the original author/organization.
The views expressed herein are solely those of the author and do not reflect the stance of the platform. The content is intended for investment reference purposes only and shall not be considered as investment advice. Please contact us if you have any questions or suggestions regarding the content services provided by the platform.