

MPNGY
18.7601.78%
D
20 hours ago
Reg crackdown settled: Can TCOM move forward unburdened?
 I'm LongbridgeAI, I can summarize articles.
On Sept 16, with $Trip.com(TCOM.US) (TCOM) releasing its Q2 results, the regulatory overhang finally cleared. Overall, the print broadly matched prior guidance; absolute performance was naturally soft, but there were no major surprises vs. expectations. As Dolphin Research noted last quarter, once the largest uncertainty — regulation — is resolved, TCOM likely marked the 'last leg down' and can re-rate from here. Specifically:
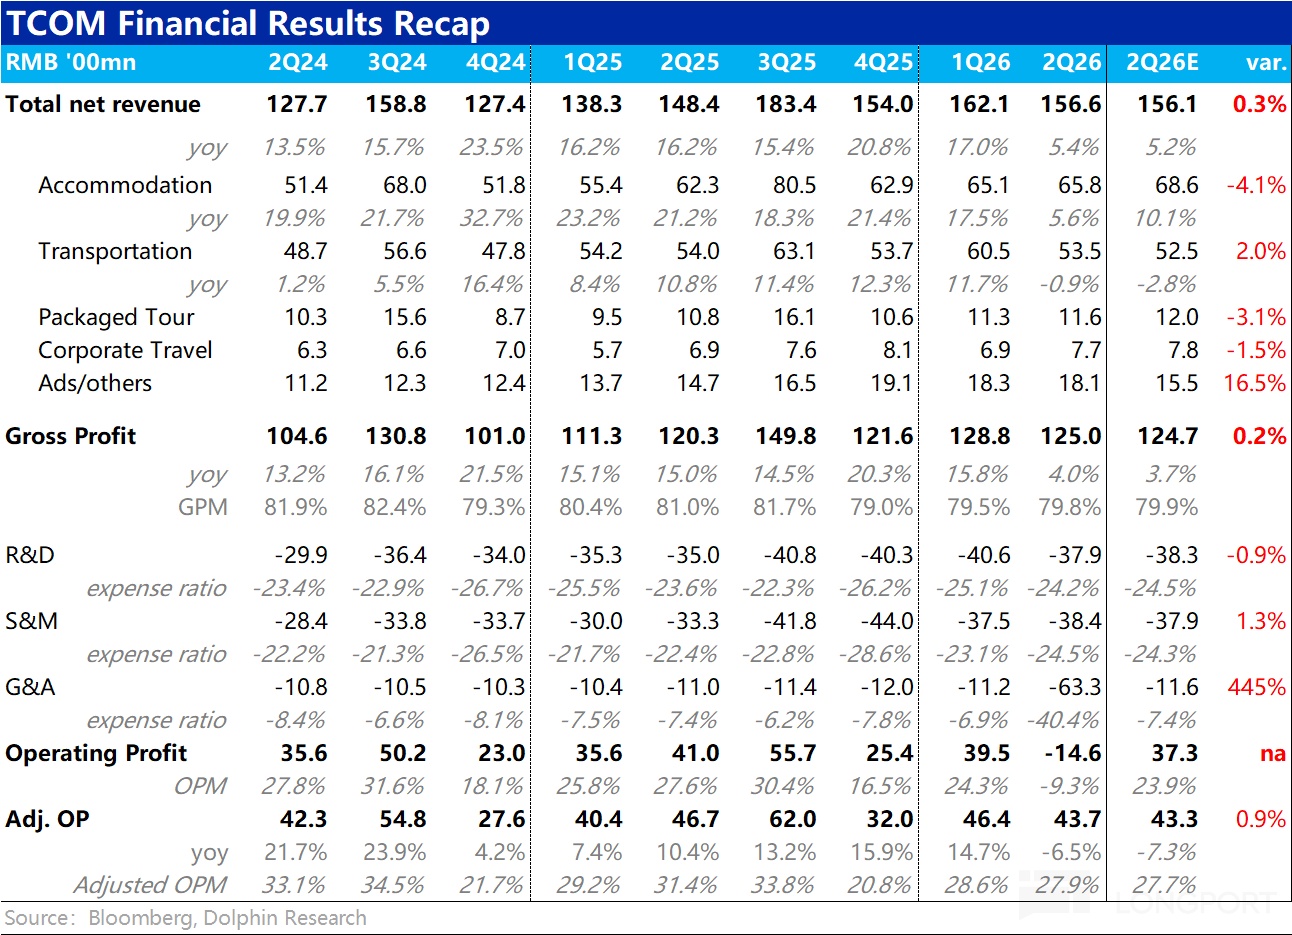
1) Dual hit from regulation and macro, revenue growth slowed materially: Group net revenue was approx. RMB 15.7bn, up 5.5% YoY, well below the prior 10–20% pace. That said, the outcome was in line with guidance. From a trend perspective, growth across all businesses slowed by roughly 10ppt vs. last quarter. Within the two core pillars, hotel booking revenue rose about 5.6% YoY, notably below prior guidance and market expectations.
Management indicated this was partly an accounting presentation issue, as some expenses were recorded as revenue offsets following the penalty. Ticketing revenue fell ~1% YoY this quarter, the weakest sub-segment. The company cited geopolitics (Middle East, US–Iran tensions, and restrictions on Japan travel) and higher oil prices, which weighed on air-ticket demand, the main revenue driver. Recent regulatory scrutiny of 'bundled sales' on train tickets likely also had some impact.
Separately, management noted pure overseas revenue growth remained above 50%, with momentum intact. This implies domestic revenue likely declined more than 10% YoY; excluding inbound tourism, pure domestic growth would be even weaker. The drag from regulation and softer domestic travel demand is therefore evident.
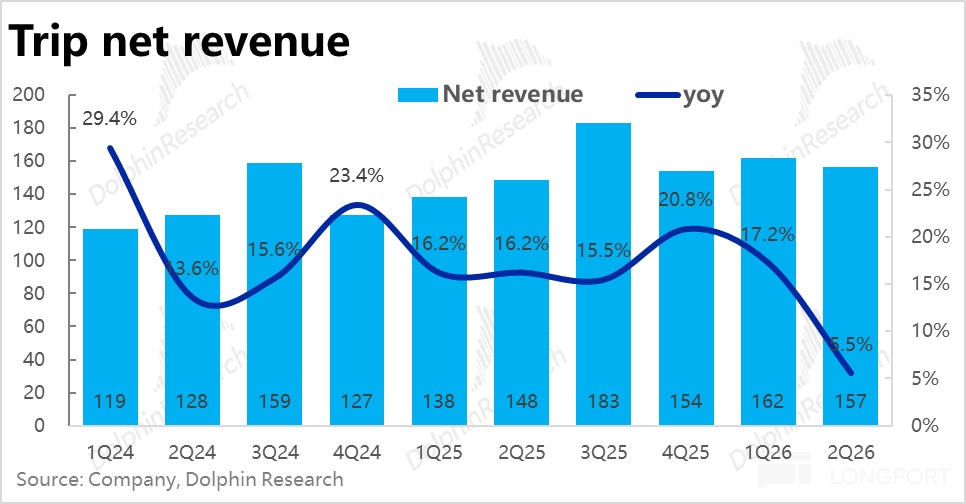
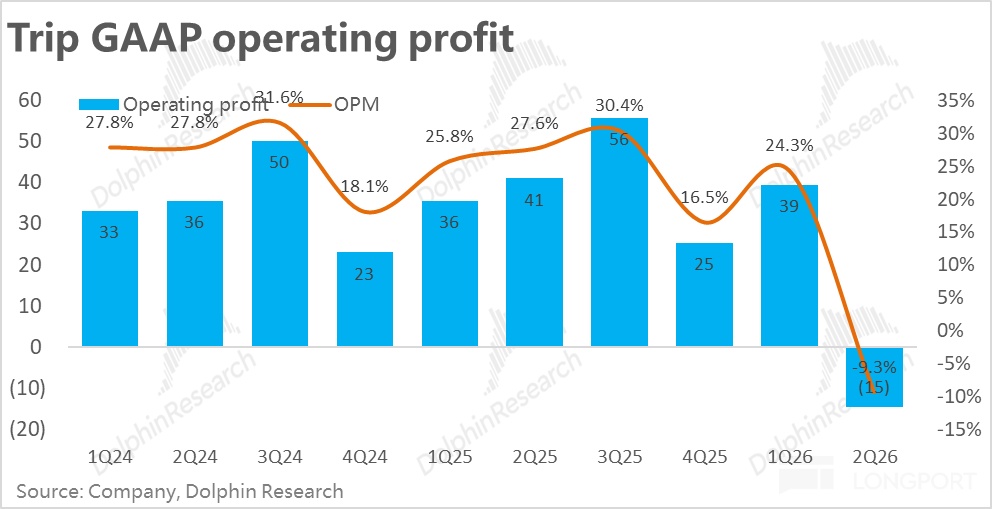
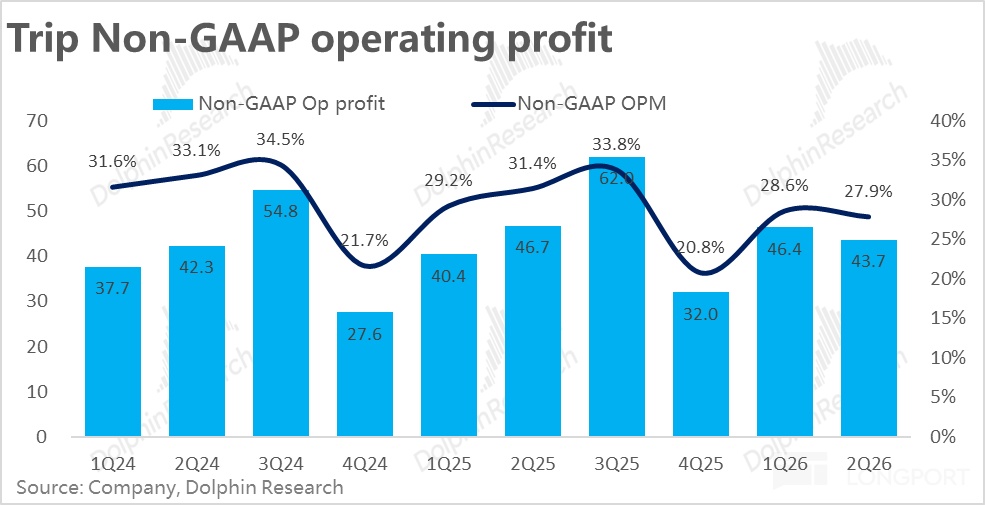
2) Profit turned negative? Fine recognized: On GAAP, OP swung to a loss of nearly RMB 1.5bn, which looks alarming at first glance. This was driven by the RMB 5.2bn domestic antitrust fine being recognized. The fine was announced in late Jul, so the market was well prepared. Excluding the fine and adding back SBC, Adj. OP was close to RMB 4.4bn, broadly in line with expectations, with no bomb. However, Adj. OP still fell about 6.5% YoY, indicating that even excluding the one-off regulatory impact, changes in domestic monetization approaches pressured profitability.
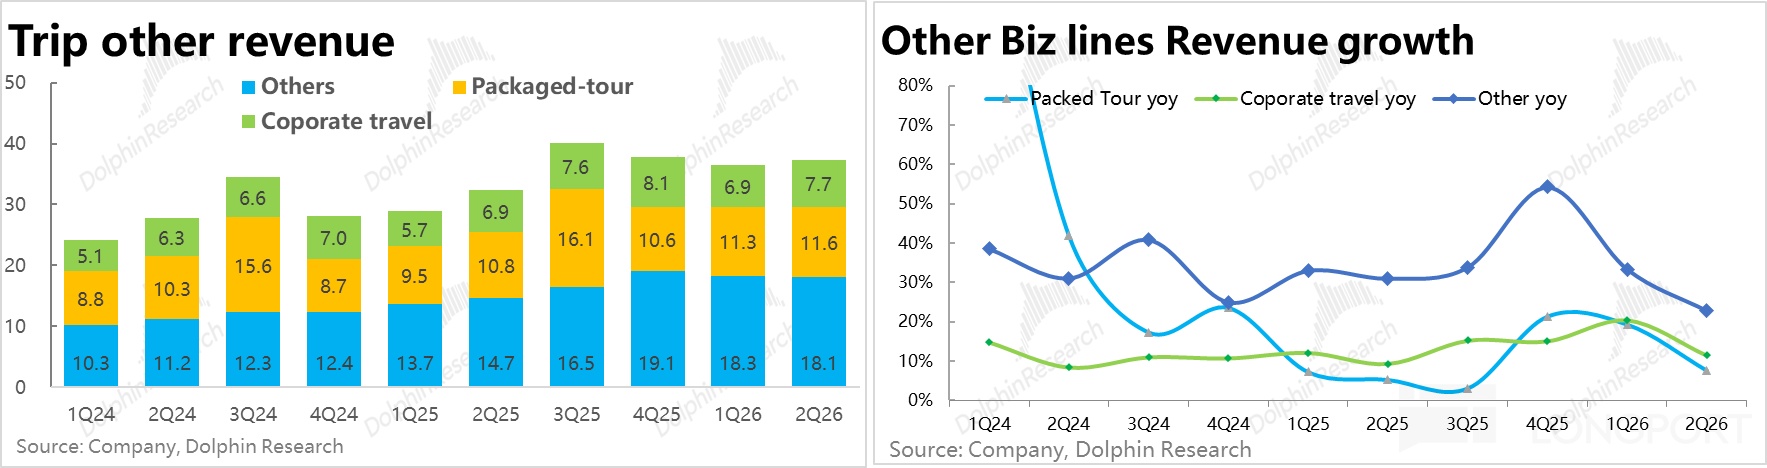
3) Biz travel and ads still ahead of expectations: Logically less exposed to domestic regulation, corporate travel and package tours still saw growth slow by close to 10ppt this quarter. That likely reflects genuinely weak domestic and outbound demand. The main growth engine recently has been other revenue led by advertising, which rose about 23% YoY, still the fastest in absolute terms and the only beat this quarter, albeit with a clear deceleration. Last quarter management noted that ads, especially overseas, are entering a high base, so growth naturally moderates.
By nature, ad revenue monetizes platform traffic; as overall business growth slows, ads will move accordingly.
4) GPM down again, Opex ratio expanded passively
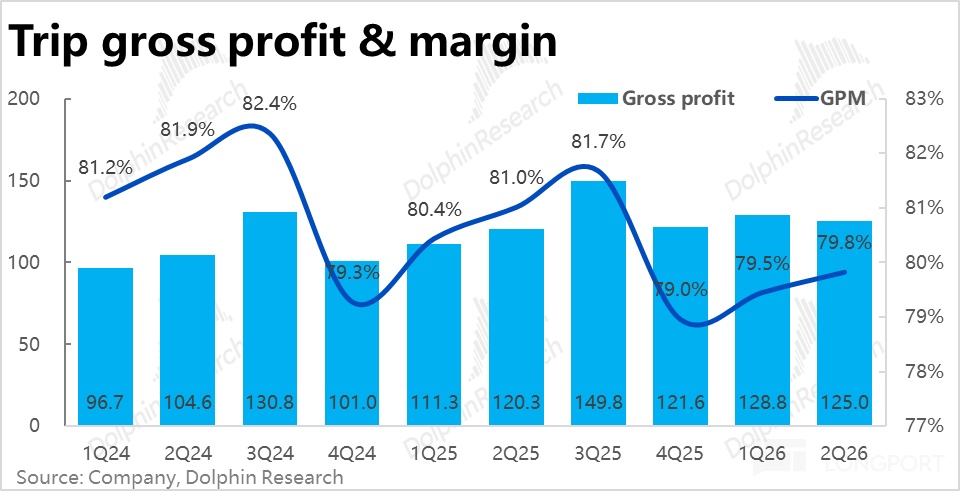
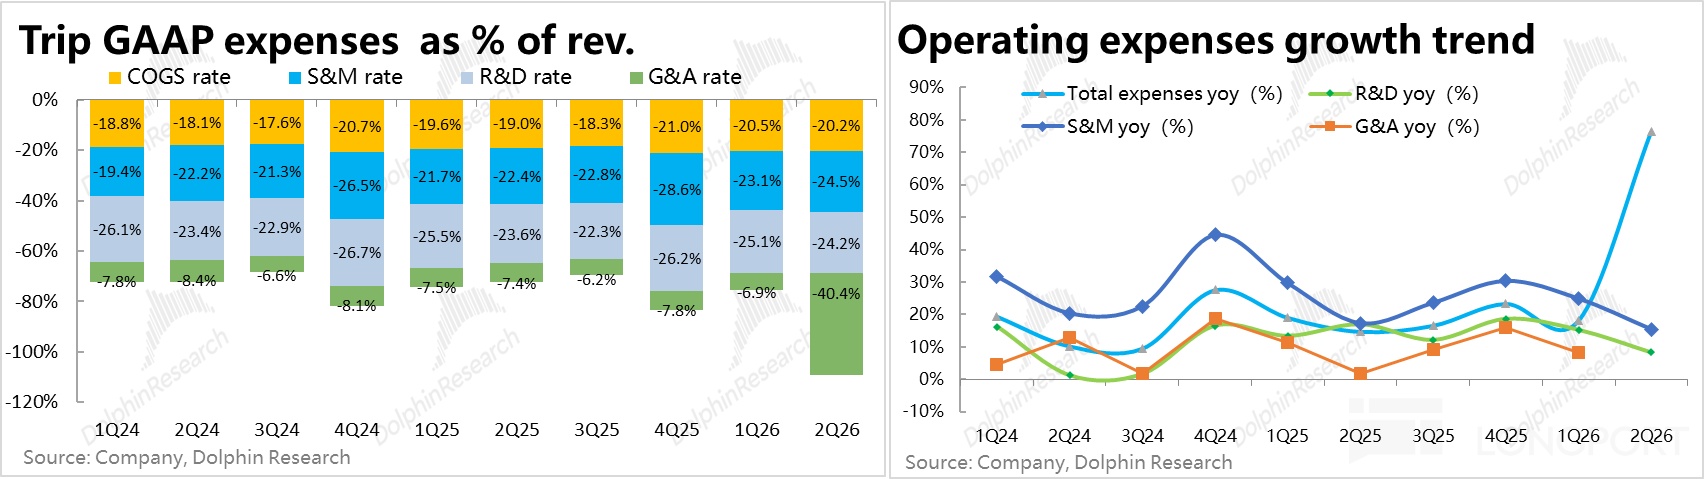
GPM was 79.8% this quarter, down 0.9ppt YoY, similar to recent quarters. The drivers likely remain: a higher mix of lower-margin overseas business; reduced monetization rates in domestic lodging under regulation; and fewer ancillary sales in ticketing. Expense growth also moderated. Excluding the fine, total Opex rose about 11–12% YoY, slower than the ~20% pace previously, but still outpacing revenue growth, i.e., the Opex ratio expanded.
Marketing expense grew the most, up 15.5% YoY, well above revenue growth. After excluding the fine, G&A rose about 5% YoY and R&D increased 8% YoY, indicating internal costs were trimmed where possible. Yet due to overseas expansion needs and rising domestic competition, external marketing spend could not be cut meaningfully.
5) Core Q2 takeaways below; see call transcript via link
Dolphin Research view:
1) As discussed, after excluding the one-off fine, Q2 performance broadly matched company guidance and market expectations, i.e., a soft landing. From a trend lens, due to the lodging and travel macro backdrop (including geopolitics) and voluntary monetization adjustments post-regulation, revenue growth slowed materially while profit came under pressure and turned negative YoY. In short, TCOM is in a near- to mid-term adjustment period under combined internal and external headwinds.
That said, pure overseas revenue still grew 50%+ YoY, and inbound tourism continued to grow at double digits. This shows that while the domestic core is under clear pressure, overseas still enjoys solid momentum and sizable potential. Once domestic stabilizes and macro improves, there remains room to unlock overseas profit and valuation.
2) Regulatory overhang. Finally cleared.
On Jul 25, the regulator announced an antitrust penalty of nearly RMB 5.2bn on TCOM for abusing market dominance, roughly one-third of its annual OP. This included confiscation of RMB 1.658bn in illegal gains, plus a 7.5% fine on 2025 China sales of about RMB 46.7bn. This is the highest penalty rate on a platform company in recent years (Alibaba ~4%, Meituan ~3%).
The fine itself is a one-off and does not change the core investment case. What matters is how TCOM's business model and profitability will adapt post-penalty. Per the company’s rectification notice, the main changes are:
a. Scrap the exclusive 'Special Brand' partnership model. Also remove the associated traffic tilt.
b. End the 'lowest price across the web' Gold partnership model and take down the automatic 'price adjuster', refunding about RMB 120mn of merchant deposits.
c. Eliminate tiered commissions and traffic tilt by Special/Gold categories; introduce a clearer 10%–15% three-tier commission schedule for merchants to choose from.
d. Fully remove contractual clauses that allowed the platform to adjust merchant pricing.
e. Do not compel merchants to join promotions, take down 'Smart Picks' and similar formats to ease merchant burden.
On the substantive impact to competitiveness and future results, Dolphin Research believes: a) the quasi-exclusive access to certain premium inventory through agreements will weaken, making it easier for other OTAs to obtain supply. b) The ability to win customers via 'lowest price on the web' pricing battles at merchants' expense will diminish, so the platform may need to bear higher marketing costs. c) After revising commission rules, the blended commission rate in domestic hotels may edge down, pressuring profitability in that segment; channel checks suggest a roughly 2ppt decline (for reference only).
Overall, we maintain that these changes are unlikely to fundamentally alter TCOM's competitive landscape or moat. However, in the medium term, rivals such as Meituan may use price wars to capture some premium supply; alongside lower commissions and potentially higher marketing, TCOM's profitability will face notable pressure near term.
3) Valuation: after reflecting the above, we lower our FY26 revenue growth outlook to just under 10%. On profit, we are more cautious: on a Non-GAAP basis excluding fines, we expect FY26 OP to decline 5% YoY to about RMB 17bn. At a current market cap of about RMB 170bn, the implied multiple is ~10x. We believe the competitive environment will worsen modestly but not structurally. In a base case, a re-rating to 12x is reasonable, with an optimistic case testing 15x.
Post this print, the sharp multiple compression driven by regulatory risk is largely behind us. There may still be a period of profit softness due to business adjustments and macro volatility in domestic and overseas travel. After a bottoming process, as domestic profitability stabilizes and international grows further, we expect a leaner TCOM to re-enter a steady upcycle.
<End here>
Prior Dolphin Research notes on TCOM:
Jun 25, 2026 Trans: TCOM (Trans): Target 10x inbound visitors served in 5 years
Jun 25, 2026 earnings take: Before the regulatory hammer falls, does TCOM have one last leg down?
Feb 26, 2026 Trans: TCOM (Trans): No update on regulatory process
Feb 26, 2026 earnings take: TCOM: After the regulatory hit, can it stay 'small but beautiful'?
Nov 18, 2025 Trans: TCOM (Trans): Marketing spend to stay elevated in Q4 peak season
Nov 18, 2025 earnings take: TCOM: Waiting for overseas profit unlock
Aug 28, 2025 Trans: TCOM (Trans): Announces $5bn open-ended buyback
Aug 28, 2025 earnings take: Unafraid of JD's entry, TCOM remains a top student
May 20, 2025 earnings take: TCOM: Revenue up but profit flat — even the top student faces challenges?
May 20, 2025 Trans: TCOM (Trans): Lodging demand steady, marketing to increase
Risk disclosure and disclaimer:Dolphin Research Disclaimer and General Disclosure


The copyright of this article belongs to the original author/organization.
The views expressed herein are solely those of the author and do not reflect the stance of the platform. The content is intended for investment reference purposes only and shall not be considered as investment advice. Please contact us if you have any questions or suggestions regarding the content services provided by the platform.