

ORCU

Dolphin Daily | Musk goes all-in on AI compute CapEx; are AI bets bleeding again?
 I'm LongbridgeAI, I can summarize articles.
Good morning. It is Oct 21, 2026 Beijing time. Dolphin Research brings you a one-glance take on global markets.

Trading highlights: SPCX Q3 AI revenue at $7.56bn (+830% YoY), becoming the largest revenue stream for the first time, with shares up nearly 7% after-hours. SMCI preannounced revenue far above estimates, up 11% after-hours.
Anthropic’s draft S-1 surfaced: H1 revenue $16.3bn, with over $518.0bn in compute commitments over the next decade. DeepSeek open-sourced the DeepInfer inference framework, adding support for Ascend 950.
Macro sentiment: Reports of a U.S.-Iran compromise pushed WTI down as much as 3% intraday, closing -1.8%. Pending home sales for Sep fell 7.3% to a record low, 10Y UST -3bps to 5.11%, and the Oct hike probability fell to about 13%.
Core bellwethers: Markets fell early but recovered, with Nasdaq-100 -0.1% and Russell 2000 +1.7%. Semi cap led declines (LRCX -3.2%), and META -1.6% was under pressure ahead of earnings.
Asia rebounded this morning: Musk plans to add 10GW of new capacity by end-27, a timely boost to AI capex.
KOSPI opened +2.0% and extended to 3%. SK Hynix opened +2.0% and extended above +6%, Nikkei opened +1.3% then extended to 2%.
TAIEX gained about 1.3% at the open on valuation. FTSE China A50 futures also rose at the open.
Near-term watch: Jensen Huang’s Berlin GTC keynote at 17:00. META, TSLA, and LRCX report after-hours tonight (Beijing morning of 10/22).
WDC reports 10/22, MU’s Taoyuan plant strike, Oct PMI flash on 10/23, and FOMC on 10/27–28.

$SpaceX(SPCX.US) 、$NVIDIA(NVDA.US) 、$Meta Platforms(META.US) 、$Tesla(TSLA.US) 、$Taiwan Semiconductor(TSM.US) 、$Alphabet(GOOGL.US) 、$Micron Tech(MU.US) 、$SK Hynix(SKHY.US) 、$AMD(AMD.US) 、$Oracle(ORCL.US) 、$Coreweave(CRWV.US) 、$Apple(AAPL.US) 、$Z.AI(02513.HK) 、$MINIMAX-W(00100.HK)
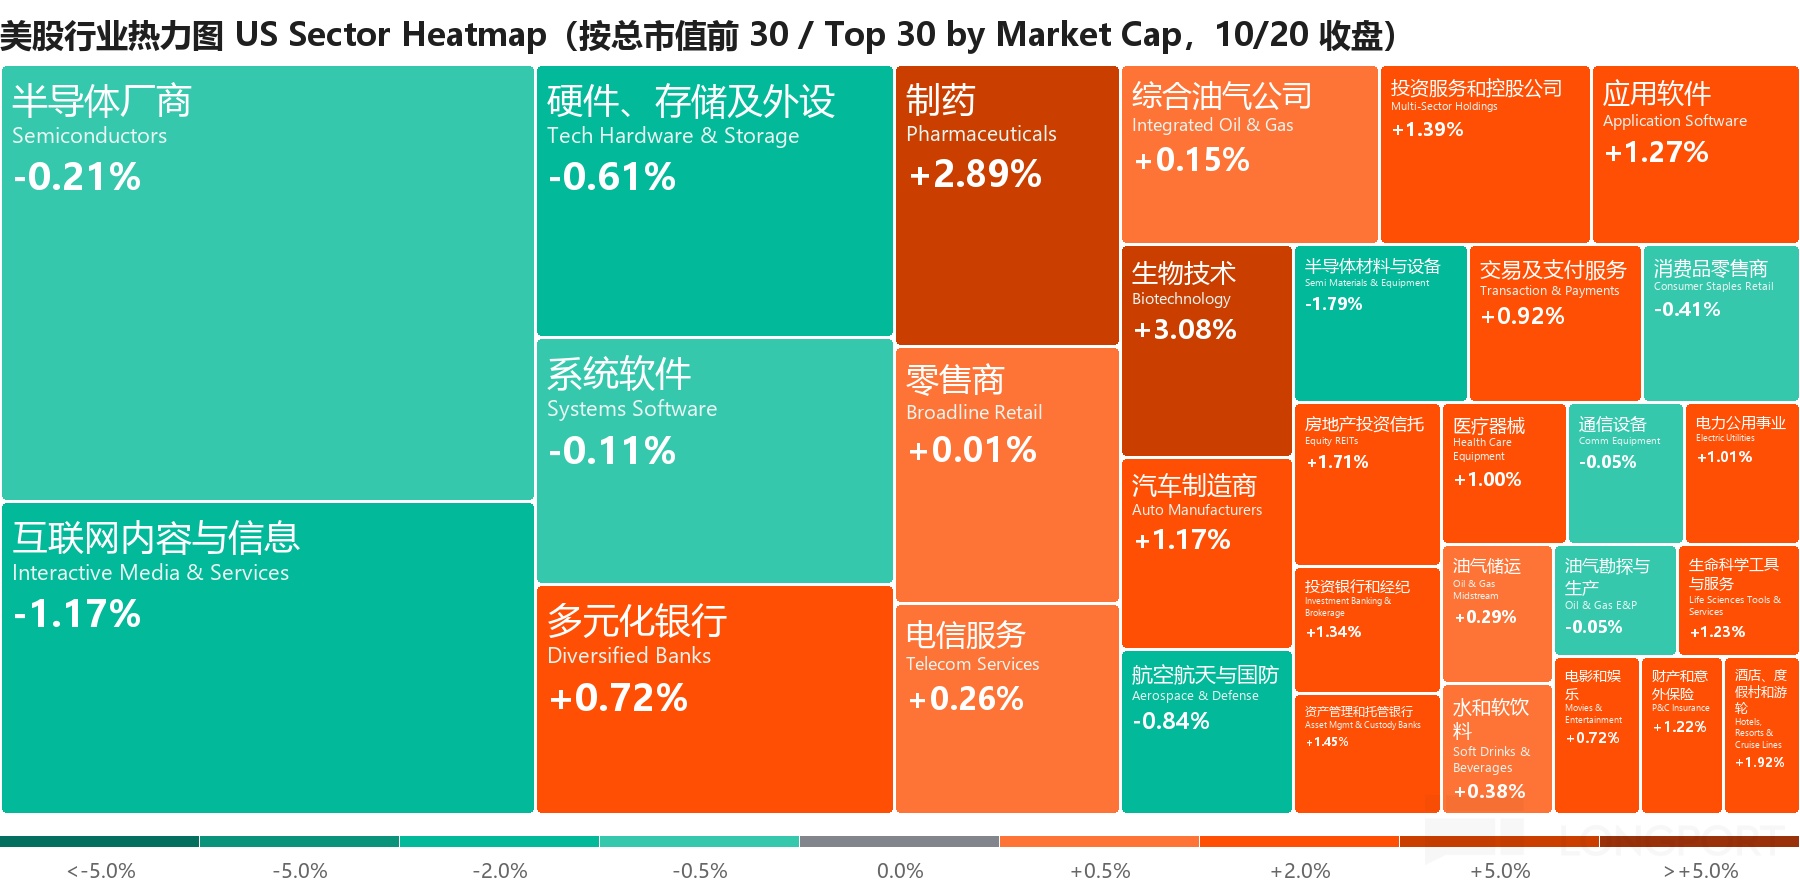
Moves: For U.S. stocks and global assets, performance reflects the 10/20 Tue close vs the prior session. For Asia, it reflects today’s 10/21 open vs yesterday’s close, and futures for markets yet to open.

1. SPCX Q3: AI revenue +830%, surpassing rockets and Starlink for the first time
Q3 revenue $14.58bn (+161%), net income $4.4bn (street $1.88bn), and Adj. EBITDA $8.81bn (+306%).
SI (superintelligence) revenue was $7.56bn, up $5.0bn QoQ, with Adj. EBITDA of $5.0bn. Cursor, consolidated on Aug 14, contributed $608mn.
Compute: 1.7GW by end-Q3, near 2.2GW by end-Oct, and 2.5–3GW by year-end. For 2027, add 10GW with year-end at no less than 13GW, and Musk sees a rapidly rising probability of exceeding 20GW.
Unit pricing is slightly above the top end of the $30–50 per W range. New deployments have a payback under one year, and Musk said six months next year is possible.
The trade-off is capex: $19.6bn in Q3 (+185%) with Q4 guidance at $35–40bn. Q1 2027 revenue is guided at $33–37bn.
M&A: TSLA and SPCX each formed special committees of independent directors. Musk said a merger is a good idea, but terms are not agreed, and TSLA needs at least 50% approval of all shares.
2. Anthropic draft S-1: $16.3bn revenue, over $518bn compute commitments
Per WSJ citing the draft, H1 revenue was $16.3bn (vs $1.1bn a year ago), with about 20% from two customers. This concentration matters for risk.
H1 net loss was $80.7bn, with about $72.0bn from accounting for valuation changes in convertible notes and other financing instruments. Q3 revenue rose 45% QoQ to $16.8bn.
Compute commitments exceed $518.0bn over the next decade, including up to $86.0bn for leasing NVDA chips. The target is a Nov listing at a $1.5–2.0tn valuation.
Reuters also reported OpenAI is accelerating a ~$30bn private raise at a valuation possibly above $1.4tn, seeking to lock in investors before Anthropic lists.
Institutional modeling debate: After excluding major customers and distillation, net new ARR in Aug–Sep was only about $5.5bn, and the year-end ARR target of $100–110bn is seen as unrealistic.
The market now questions not capex vs returns but whether lab revenue can support the signed commitments. Beats from hyperscalers may offer less reassurance.
3. DeepSeek open-sourced DeepInfer: 155 trillion tokens per day on Ascend 950
DeepSeek open-sourced its in-house inference framework DeepInfer, supporting NVDA SM100 and Huawei Ascend 950. V4.1 Flash delivered 155 trillion tokens/day per cluster with a 96% input cache hit rate.
V4.1-Flash-1017 topped Code Arena’s open-source ranking, with single-task cost down about 60% vs the prior version. Minimax released M3.1 Flash, cutting prices to half the prior generation.
Policy is tightening on both sides: The U.S. DHS asked federal civilian agencies to remove DeepSeek products. China plans to add cutting-edge model tech, including >2T parameters, to export controls. See Dolphin Research’s earlier take on policy and competition.
Reuters said ByteDance, Alibaba, and 0700.HK ordered over 3mn RTX PRO 5500 cards (list price implies over $35.0bn), the most advanced chips within policy limits. NVDA indicated it may only supply 5–10%, highlighting the compute gap.
4. SMCI preannounced a big revenue beat, +11% after-hours
SMCI guided FQ1 revenue to $18.5–19.5bn, well above the ~$15.0bn street, with GPM of 12–12.5%. This indicates stronger demand and mix.
On the same day, TrendForce raised capex forecasts for the nine major cloud players to $957.0bn in 2026 (+106%) and over $1.5tn in 2027 (+60%).
5. GOOGL open-sourced TorchTPU: native PyTorch on TPU
After AMZN launched TorchNeuron last week (PyTorch on Trainium without code changes), GOOGL open-sourced TorchTPU. ASIC players are now lowering CUDA switching costs via software.
CEO Sundar Pichai said on a podcast that everyone is short of compute, with demand booked out to 2027. The cloud biz is sacrificing short-term revenue to fund frontier R&D.
6. Another round of AI financing jitters later reversed
Korea’s new cloud Elice fell 32% below IPO price on debut, with KOSPI -3.7% the prior day. SoftBank CDS hit a 4-year high, and CRWV hit a 52-week intraday low.
At 9:15 ET, reports that the U.S. and Iran back a Qatar/Pakistan compromise, plus soft pending home sales, flipped markets. About 85% of S&P 500 constituents rose.
Credit spreads still widened: Goldman charts show new cloud (NBIS, CRWV, IREN, etc.) OAS rising alongside hyperscaler CDS. HSBC said CRWV’s Avg. ROIC of 8.9% for 2026–30 is below its cost of debt.
Barclays: Anthropic/Nscale pricing implies forward compute economics well below the scarcity pricing of CRWV/SPCX, as the market shifts from capacity at any cost to acceptable returns.


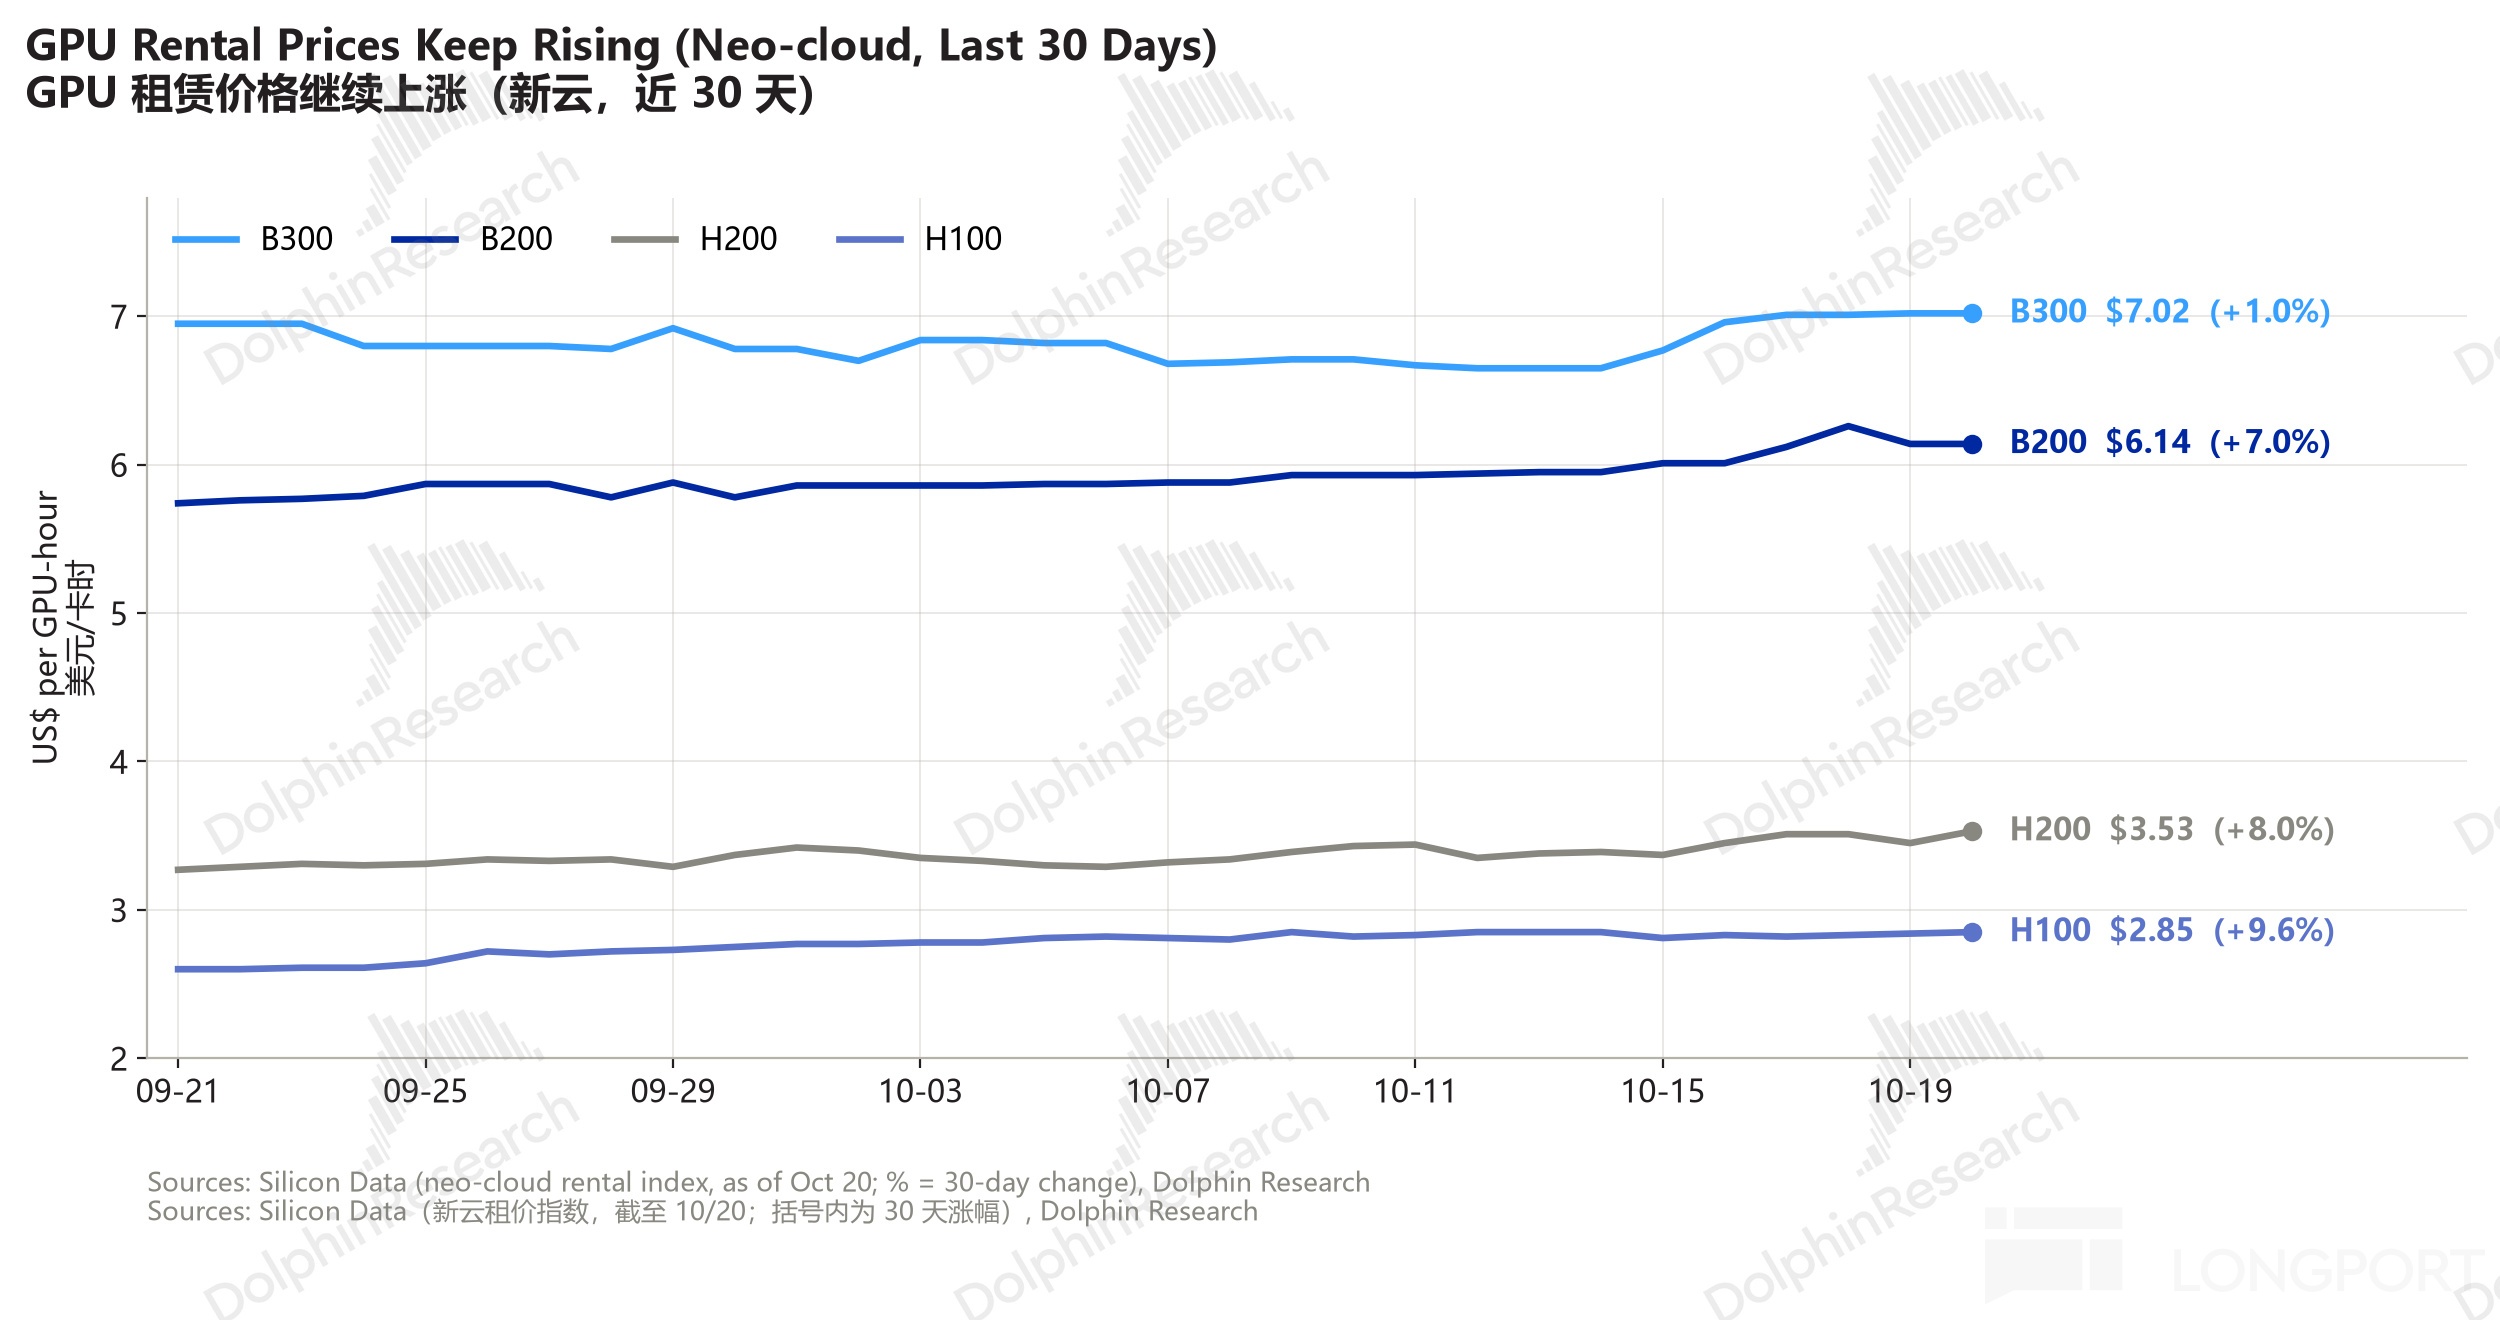
Silicon Data new cloud GPU rental index (10/20): H100 at $2.85 per GPU-hour (+9.6% over 30 days), H200 at $3.53 (+8.0%), B200 at $6.14 (+7.0%), and B300 at $7.02 (+1.0%).
B300 fell back to $6.65 on 10/14 then rebounded about 6% in a week. Hyperscaler H100 quotes are $7.14, about 2.5x new cloud, and roughly flat over 30 days.
SemiAnalysis earlier estimated H100 1-year contract prices rose from the Oct 2025 low of $1.70 to $2.35 by Mar 2026. Institutions said new cloud GPU rents were raised twice in Q3, totaling about 37.5%.
SPCX said on its call that rents for older cards like H100 now exceed their new-card period, and short-term renewals priced per watt are higher.

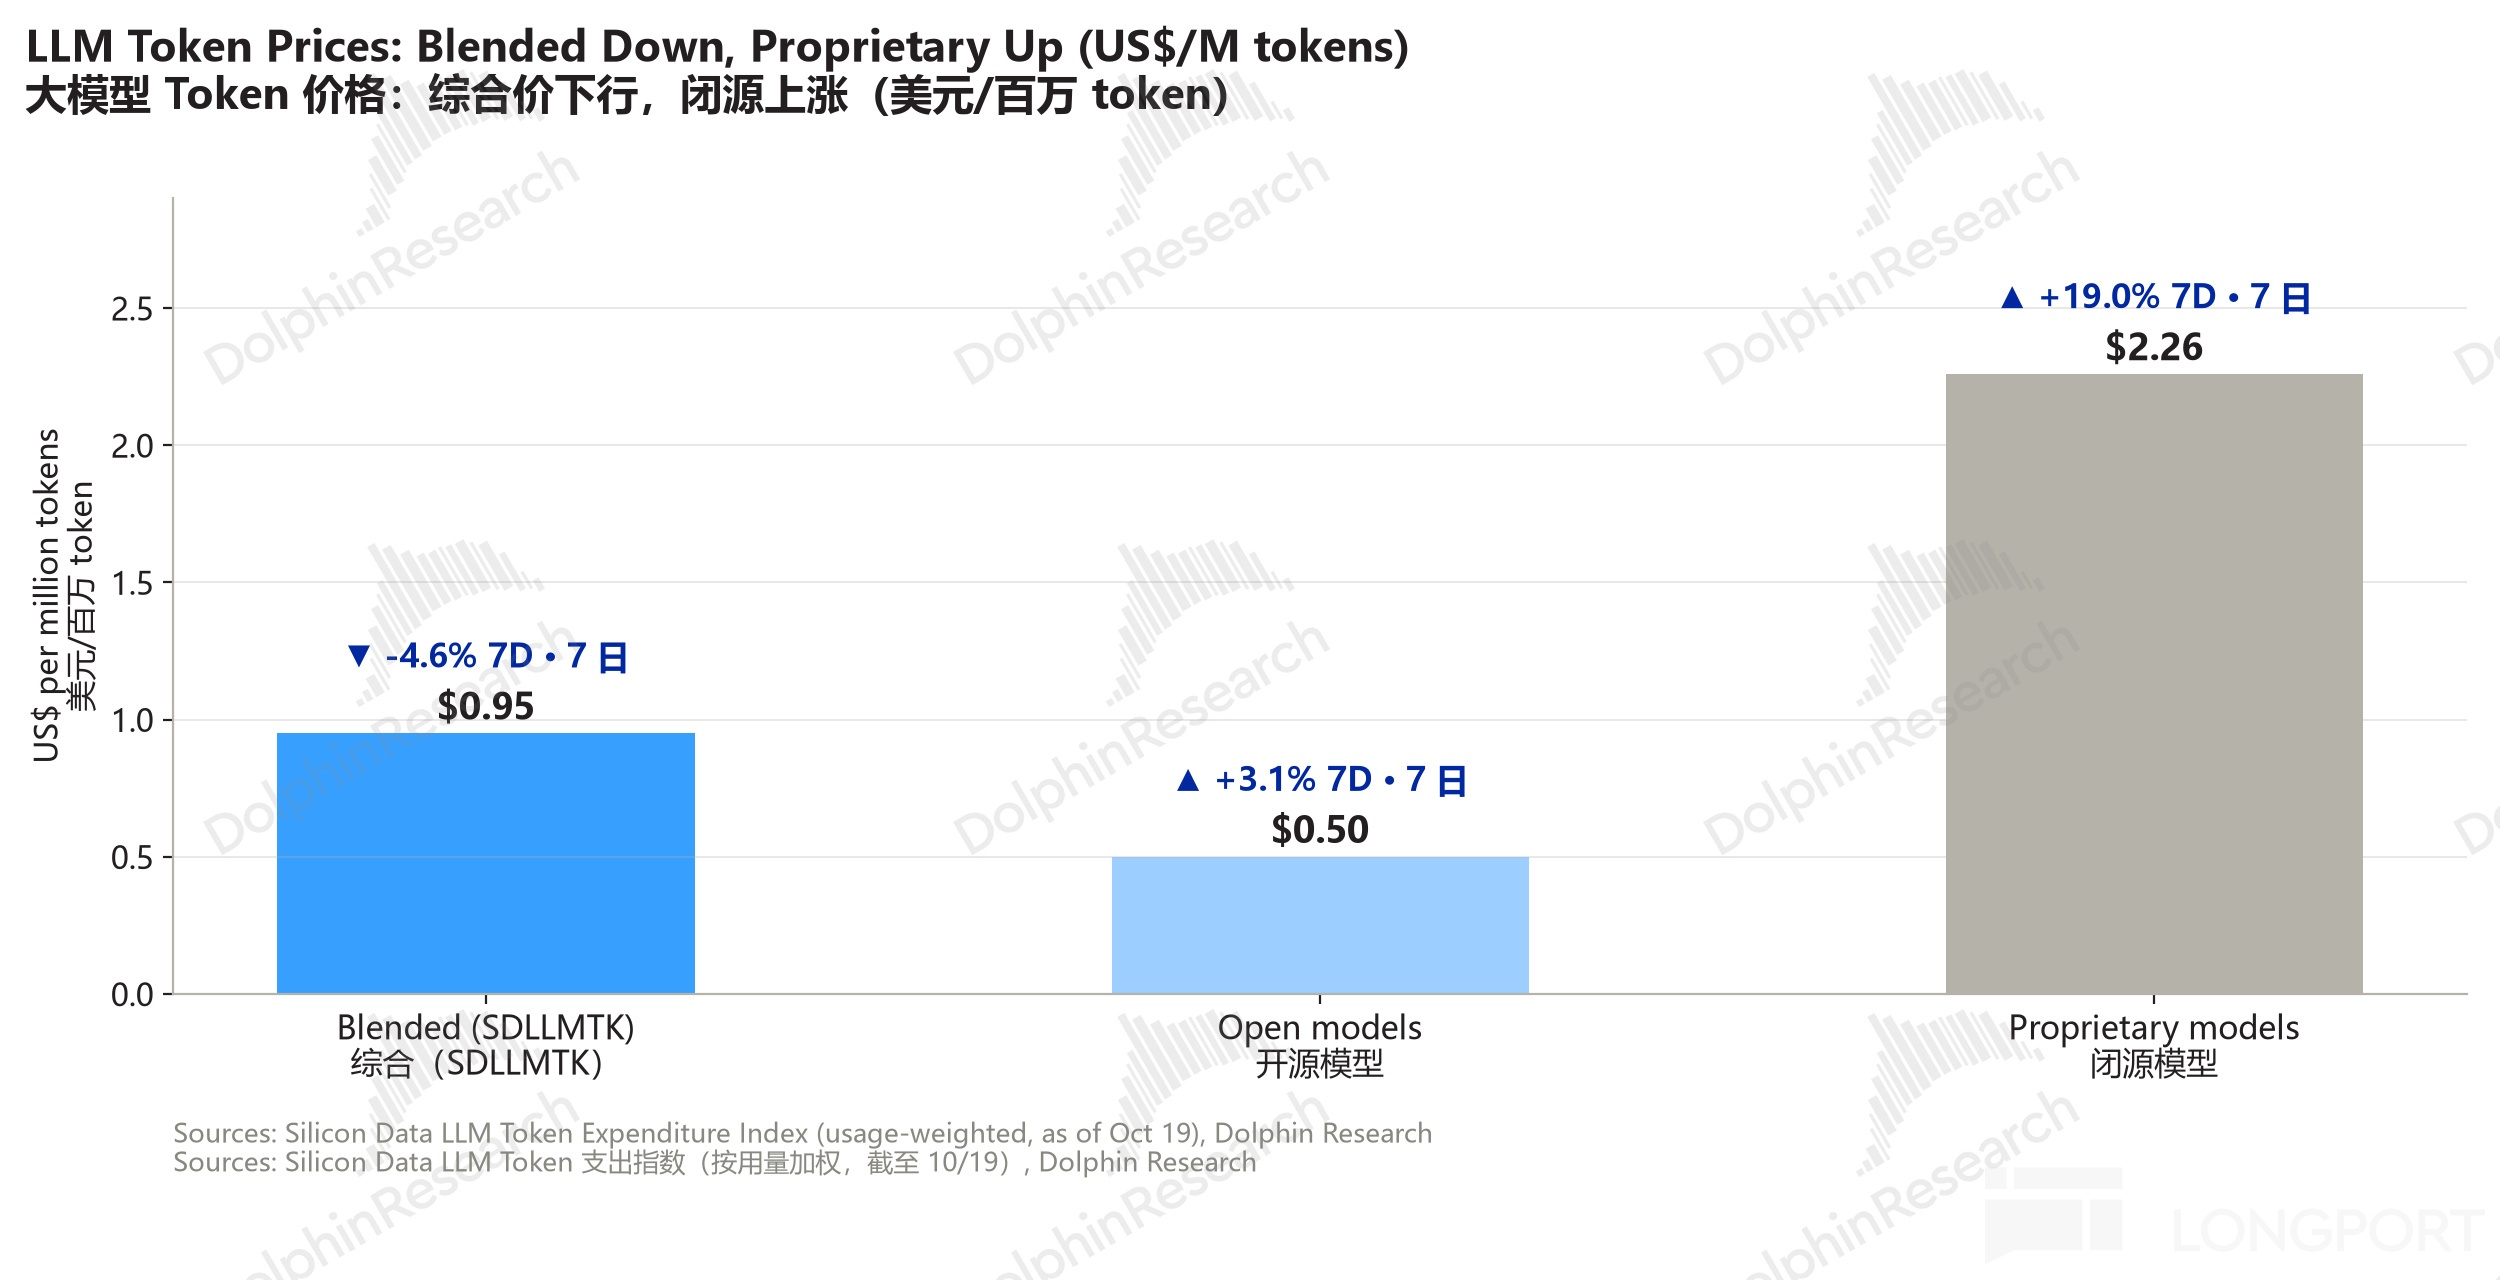
Silicon Data LLM token spend index (10/19, usage-weighted): blended $0.95 per mn tokens, down 4.6% over 7 days.
Open-source models at $0.50 (+3.1%), closed-source at $2.26 (+19.0%).
The blended decline mainly reflects mix shifts to cheaper models and cache reads, not broad price cuts. Institutions estimate enterprise API cache reads at about 85%, and the closed-source increase likely ties to frontier model pricing.
Price cuts are still happening within the frontier tier: OpenAI said GPT-6 Luna outperforms last month’s 5.6 Sol with costs 34x lower. DeepSeek and Minimax also cut prices on Flash models.

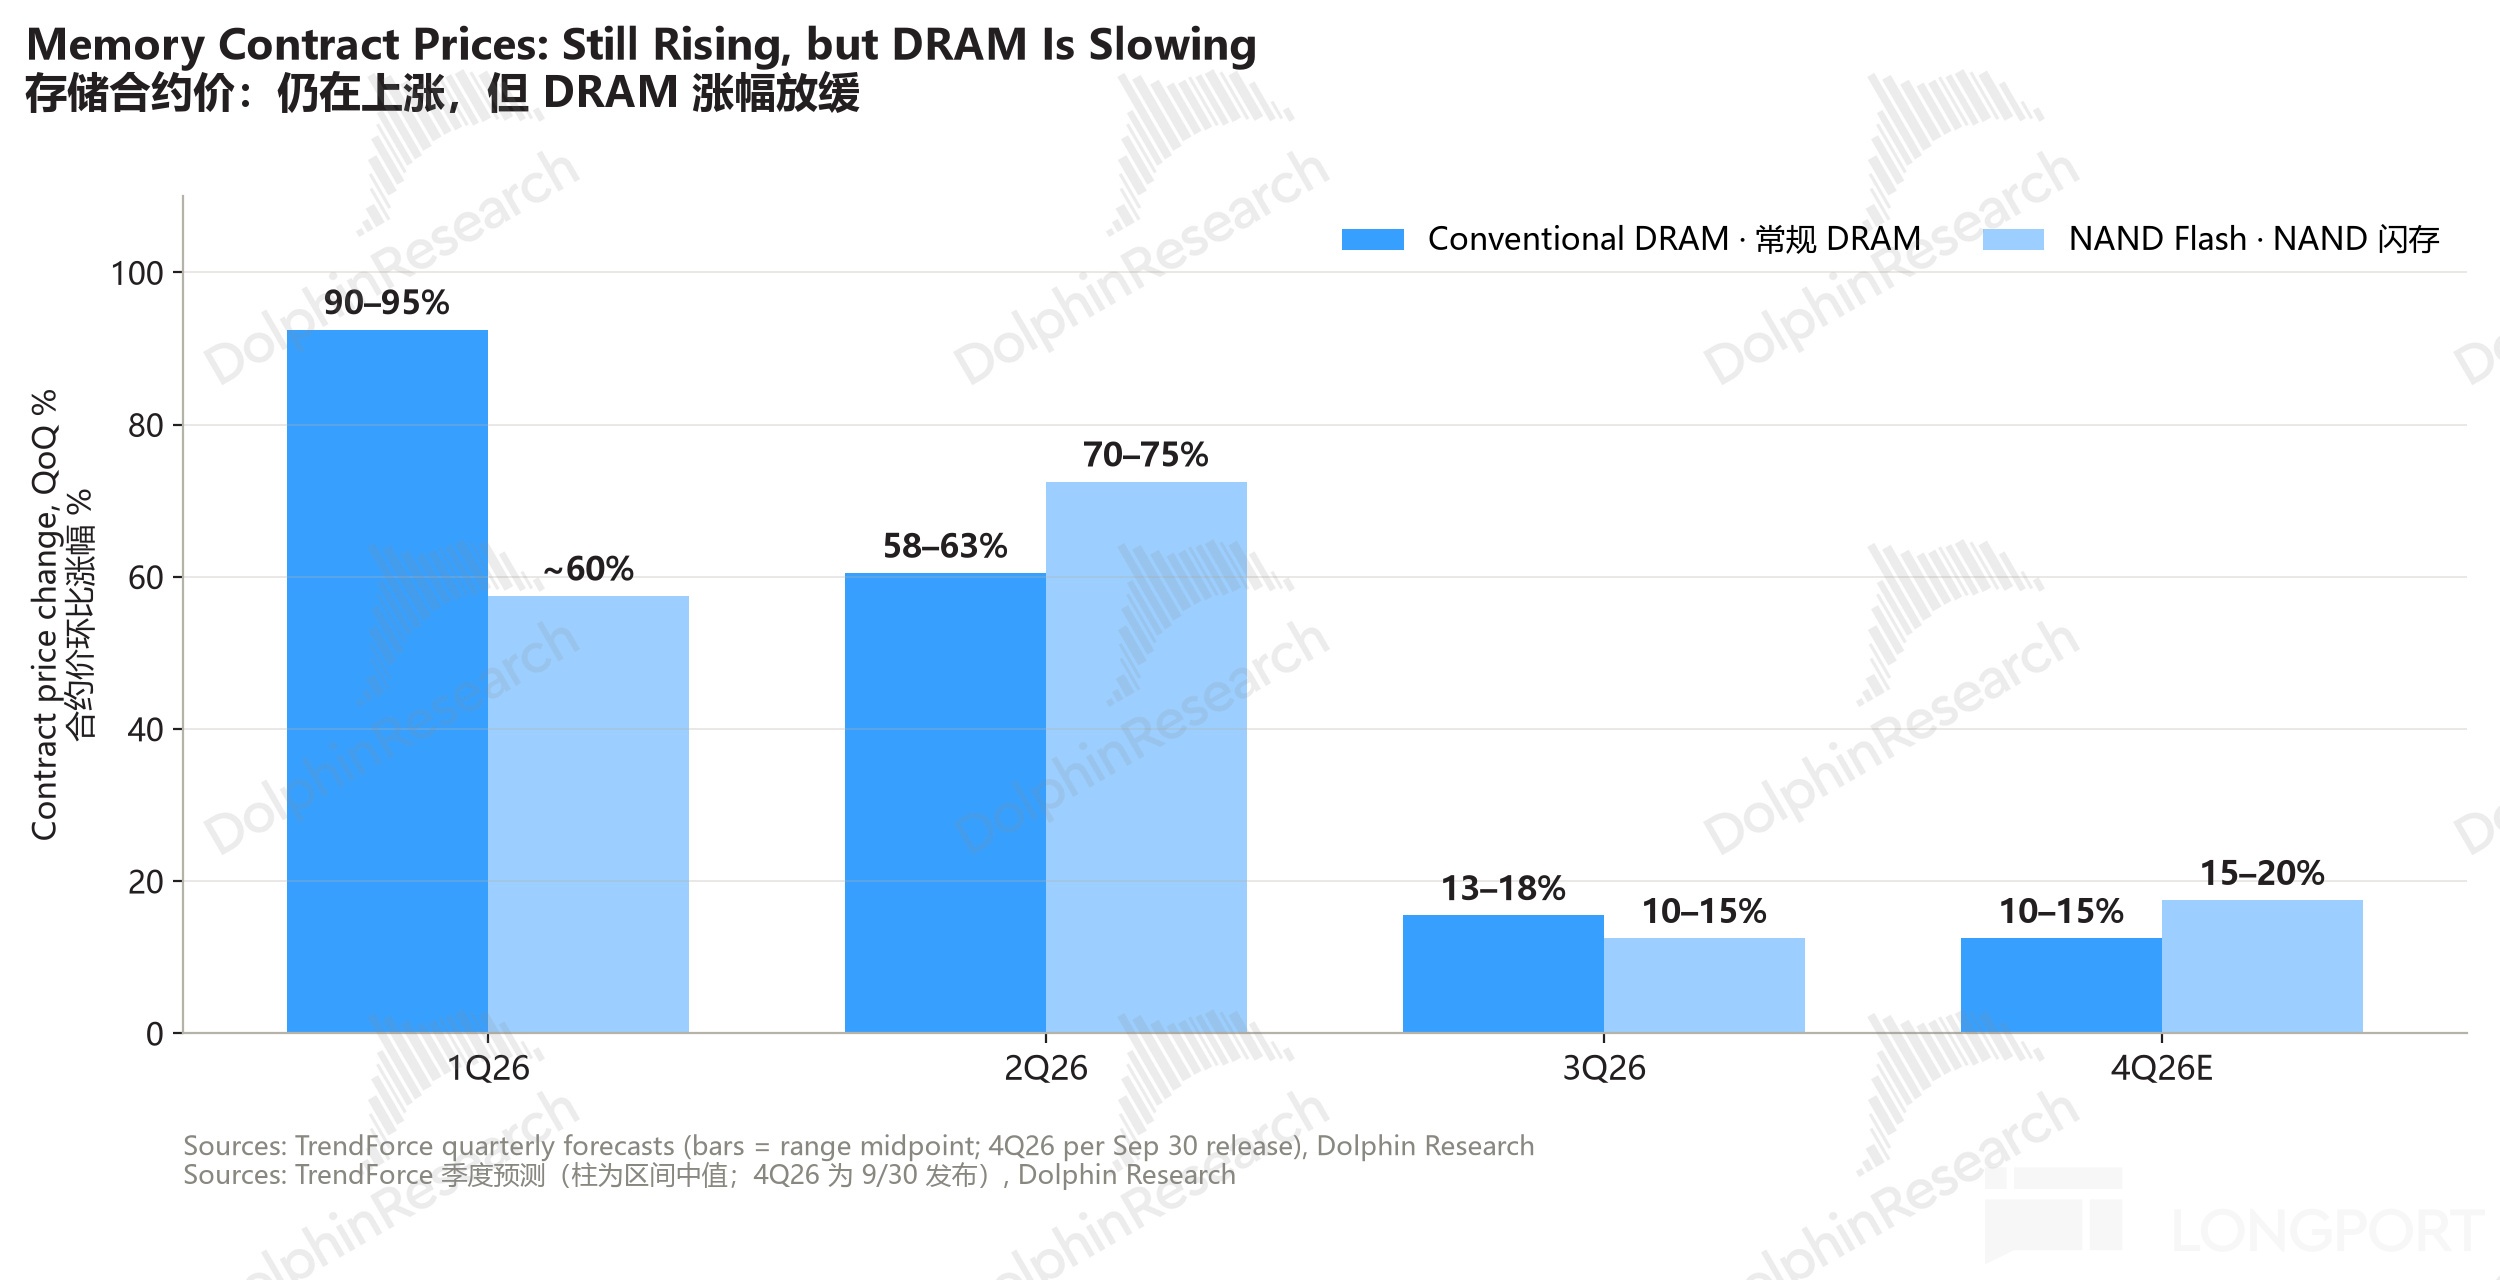
TrendForce: 4Q26 standard DRAM contract prices up 10–15% QoQ, NAND up 15–20%. The DRAM slope slowed from 90–95% in Q1, while NAND re-accelerated on enterprise SSD demand.
HBM is tighter: TrendForce expects HBM blended ASP to rise 121% YoY in 2027. HDD lead times are 50 weeks vs a balanced 16 weeks, and fiber faces a 180mn fiber-km shortfall in 2026.
Spot has flattened: 10/20 DDR5 16Gb spot Avg. $60.7 (+0.1% DoD), DDR4 16Gb $83.4 (-0.1%), and 512Gb TLC wafers were flat WoW. This suggests stabilization near-term.
Dolphin view: Compute rents, HBM, and fiber prices are still rising while blended token prices fall. The spread is shifting from model labs to compute and components, with new cloud monetizing scarcity premiums. The 1–2 year durability hinges on supply.

No major data last night, but pending home sales for Sep badly missed. Initial claims arrive Thu and Oct PMI flash Fri, with the Fed in blackout ahead of FOMC.
1. Macro → equities
USTs and liquidity: 10Y -2.7bps to 5.11%, 2Y +1bp to 4.78%, and the 2s10s narrowed to 33bps. The 10Y has pulled back from the 5.36% high on Oct 8, the highest since 2024.
The Sep pending home sales index fell 7.3% (consensus -0.5%) to 66, the lowest since data began in 2001. Housing starts are also at the lowest since 2020, with mortgage rates the key drag.
Citi: without a pullback in oil and breakeven inflation, the 10Y may not have topped. S&P Global said AI-related capex by six hyperscalers will exceed $7tn in 2025–30, with undisclosed contingent guarantees.
This week: Thu (20:30) initial claims. Fri (21:45) S&P PMI flash for Oct in mfg/services, and Michigan consumer sentiment. Watch the input price sub-index closely.
If PMI input prices keep rising, it could lift rate hike odds. If they ease, it should help the long end and high-multiple tech.
Fed path: Oct 28 hike probability fell to about 13% (from ~17%), Dec hike pricing near 76%, and at least one more hike this year at about 82%. This still implies a hawkish tilt.
BoJ may hold on Oct 30 and hike as early as Dec (Reuters). The France-Germany spread topped 150bps, and Besant said haven flows are moving into USTs.
Oil: WTI spiked above $110 intraday, then fell over 3% on U.S.-Iran compromise chatter, closing -1.8% at $101.8. Israel moved to the highest combat readiness at the same time.
2. Big movers (10/20)
Russell 2000 +1.7%: Rates eased and breadth improved, with small caps leading. This is consistent with a relief rally.
VIX -6.1% to 17.3: AI financing jitters faded after the open. Volatility normalized into the close.
WTI Nov contract -1.8% to $101.8: U.S.-Iran compromise reports drove a sharp intraday drop. Energy equities tracked the move.
10Y UST -2.7bps to 5.11%: Record-low pending home sales drew haven flows. The long end benefited modestly.
Bitcoin +1.6% to about $83k: Intraday high at $83,335. Crypto risk appetite remained firm.
3. Asia open playbook (10/21)
At the open: KOSPI +2.0% and Nikkei +1.3%, later extending to about +3.2% and +1.8%. TAIEX opened 09:00, Hang Seng and A shares at 09:30, with Nasdaq futures +1% after-hours.
Korea led: SK Hynix +2.0% at the open and Samsung Elec +2.1%, later extending to about +6% and +5%. This recovered the prior day’s -4% after Elice’s IPO break.
JP Morgan: 3x long semiconductor ETF (SOXL) saw a record $7.2bn weekly inflow last week, and Korea ETFs took in $1.3bn. However, DRAM-themed ETFs saw an eighth straight week of outflows.
Opportunities: NVDA, MU, and AMD were up over 2% after-hours, with SPCX and SMCI beating and guiding above. Korea memory, Taiwan server names, and AI hardware chains have room for a reflexive bounce.
DeepInfer added support for Ascend 950, and Xiechuang Data signed a RMB 37.49bn long-term domestic-card compute rental (PPU by Alibaba’s T-Head). China’s domestic compute ecosystem has a thematic tailwind.
Risks: Prior day’s Hang Seng -1.3% and HSTECH -1.5%, with 0992.HK -10%. China’s LLMs face pressure from Flash price wars and export controls.
Transmission: UST yields and the USD pulled back in tandem (DXY -0.3% to 101.7). Offshore RMB at 6.676, aiding valuation recovery in Hong Kong.


NVDA | $5.23tn | -0.3%
China orders are in focus per trading highlights. TD Cowen channel checks suggest NVDA is providing credit support to ORCL, either via guarantees or renting capacity and re-leasing it.
Opinions diverge: some see this as NVDA backstopping the industry, while others worry about credit and margin drag, and NVDA CDS widened to a new high. The Information said that after investors hesitated on Australia’s new cloud Firmus IPO, NVDA stepped in with support, with NVDA up over 2.2% after-hours.
At 17:00, Jensen Huang’s Berlin GTC keynote. NVDA has an MoU with the German Gov. and is partnering with Siemens on AI factories.
Dolphin view: From shovel-seller to AI central bank, NVDA’s contingent liabilities may rise with guarantees, but gross margins are robust and the model capital-light. With Blackwell and Rubin shipping, EPS supports the stock. However, CUDA’s moat is being chipped at by AMZN and GOOGL on the software side, a long-term risk.
TSM | $2.20tn | +1.2%
Institutions see 2027 N2 monthly capacity at at least ~200k wafers (vs prior 160–170k), with capex at about $82–83bn in 2027 and about $92bn in 2028. This implies sustained expansion across nodes.
Dolphin view: TSMC sticks to tangible plans over hype. In this cycle, it is uniquely expanding both legacy and new capacity, and most trials are in-house. Capex should trend up, but the cited $85bn in 2027 and ~$100bn in 2028 sit within market expectations.
AVGO | $1.60tn | -0.1%
No company-specific updates. Anthropic’s draft S-1 (see highlights) is the swing factor for Anthropic-related orders.
Dolphin view: Of AVGO’s 20GW outlook for FY2028, 10GW relates to Anthropic. With two customers at 20% concentration per S-1, this order carries concentration risk.
ARM | -3.1%
Investor notes questioned the claimed ‘1.99x rack throughput’ for its AGI CPU, estimating single-die performance advantage at only about 1.2x. This puts the narrative under scrutiny.

LRCX -3.2% / AMAT -2.0% / KLAC -1.8%
LRCX weakened ahead of earnings, giving back most of Monday’s +3.1%. Through last Fri, LRCX and KLAC fell 10 straight sessions (-24% and -20%).
Morgan Stanley came away more positive on AMAT’s DRAM share, but sees bigger-than-expected logic share loss from 3nm→2nm. UBS said WFE vendors are prepping for 30%+ annual growth and a ~$500bn/year market.
Institutions note forward P/E has compressed 30–60% from highs, while earnings forecasts have been raised 10–20%. LRCX reports tonight; see the preview below.

MU | $1.01tn | -1.0%
MU’s Taoyuan plant union announced a strike on 10/22 in support of Taichung plant bonus talks. The two sites account for over 60% of total output, mainly DRAM and HBM.
See price trackers above. MU was up over 2.2% after-hours.
Dolphin view: CXMT’s 4F² product is more likely to ramp in late 2028, with limited visible impact on supply-demand. But medium-term supply risks skew up, making memory a trading range now, with repair opportunities near the lower bound.
SK Hynix 000660.KS +2.0% / Samsung Elec 005930.KS +2.1% (open)
They fell 4.2% and 3.0% the prior day, pressured by Elice’s IPO break and foreign selling. They opened higher with U.S. semi gains and extended to about +6% and +5%.
JP Morgan noted that ex the two giants, KOSPI forward P/E is only 8.4x, at the 11th percentile historically, but buy-side remains soft with Samsung’s buyback done and Hynix near completion.
Dolphin view: Hynix trails Samsung by one node in 4F², but holds an HBM customer edge, keeping the near-term structure intact. Today’s rebound looks more like foreign position adds.
WDC +3.4% / STX +2.2%
HDD lead times are 50 weeks, with hyperscalers locking supply through 2028 per TrendForce. WDC reports 10/22; see the preview below.

LITE -1.4% / COHR -0.1% / CIEN -0.7%
Optical names fell 6–7% intraday, then recovered. Bernstein dropped its preference for LITE to Neutral, citing debate on 2028 CPO bandwidth and indium phosphide bottlenecks.
LITE’s CEO said demand is outpacing capacity additions, with no end in sight, and that indium phosphide laser shortages will be worse than memory. This underscores persistent bottlenecks.
Accelink 300308.SZ / 03308.HK fell 1.74% yesterday, pre-market +3% today
TrendForce sees a 180mn fiber-km shortfall in 2026 with spot prices at 2.8–5x 2025 levels, and shortages lasting into 2028. This supports optical supply-chain names.

AAPL | $4.95tn | -1.0%
Loop cut to Hold: Sep/Dec-quarter iPhone units down about 10% (~13mn units), increasingly a demand issue that may not be offset in 2027. Memory price inflation is a GPM risk.
Memory costs are also pressuring Android: DIGITIMES said Samsung cut its 2027 Galaxy A OLED shipment target by 17% to about 100mn units. Cost headwinds are broadening.
Pre-earnings (11/2): concerns about memory costs eroding GPM, with bulls pointing to Duo, but Duo shipments have slipped to late Jan. Visibility is limited near-term.
Dolphin view: Surging memory prices force price hikes, and foldables need to carry the load. If iPhone weakness is demand-driven, the 35x P/E has a thin cushion.
Lenovo 0992.HK | yesterday -10%, pre-market +6% today
It fell nearly 10% the prior day, mirroring Dell in U.S. markets, as Dell’s customers are in the crosshairs of the new cloud narrative. Positioning is skittish.

GOOGL | $4.16tn | -1.1%
Pichai said Gemini 4 Argon processed 3x the tokens of the prior generation in 72 hours but is compute constrained. TorchTPU was in focus (see highlights).
Waymo plans to use a $5bn loan this month to expand the fleet from about 4k vehicles to 8k by year-end, and 20k by end-2027. This implies heavy capex needs.
Pre-earnings (10/28): buy-side sees cloud growth at 105–115%, with concerns that SPCX contracts could drag GCP margins. Third-party search data is only in line, and a London-area power incident affected several European banks the prior night.
Dolphin view: Search erosion is a long-running issue, but the stance of sacrificing cloud profits to protect frontier investment suggests model spending stays high.
MSFT | $3.95tn | -0.3%
BMO lowered FY27 Azure growth to 43.8% under the new basis but still sees upside, with Q1 at 44.5% and Q2 accelerating to 45.5%. Customers are shifting from flexible to committed consumption contracts.
Dolphin view: MSFT is back in favor, with committed contracts raising revenue visibility. It is a relative safe harbor amid financing anxiety.
AMZN | $2.83tn | +0.1%
Wells Fargo named AMZN top pick among large-cap internet for Q3, citing upside to AWS revenue and margins. The company plans to invest over €16bn in Germany by 2027.
META | $1.77tn | -1.6%
Under pressure into earnings (intraday as low as -3.5%). Bloomberg said RBC in Canada may ban the Muse agent from reading client data, and policy chief Joel Kaplan will depart.
Earnings are after-hours tonight; see the preview below. Financing and capex will be focal points for investors.
ORCL +1.2% / CRWV +1.7% / IREN -4.0%
ORCL reversed from -1.7% intraday: Cowen said it resumed DC procurement in 3Q26 and secured NVDA credit support. JP Morgan said it still needs about $20bn of funding in FY27.
CRWV bounced from a -6.4% intraday 52-week low to close up, then rose another ~4% after-hours. See HSBC and Barclays’ bearish theses in highlights.
Dolphin view: This earnings season, SpaceX was first to backstop cloud investment, guiding AI-related ARR to $0.5–1.0tn next year and compute to 13GW by end-27. This is a shot in the arm for new cloud and AI capex, but financing costs remain a major hurdle.

Tencent 0700.HK | $470.9bn | yesterday -1.77%, pre-market +0.15% today
It fell 1.8% the prior day with HSTECH. Together with ByteDance and Alibaba, it ordered over 3mn RTX PRO 5500 cards, but NVDA can only deliver a small fraction.
Dolphin view: Q3 OP is expected to be flat to negative YoY, and compute investment of over RMB 200bn per year in 2024–25 will keep eroding profits and cash flow.
BABA | $270.2bn | +0.0%
Xiechuang Data signed a RMB 37.49bn, 5-year compute rental using Alibaba’s T-Head PPU. It is the first hundreds-of-billions RMB order for domestic accelerators.

NOW | +2.9%
JP Morgan estimates Q3 cRPO at about $13.6bn (+19.5%), with AI annual contract value above $1bn in Q2. Bernstein said AI-native SKUs contribute 60–70bps growth in Q4.
MDB | +5.0%
Likely lifted by software M&A sentiment after CRM’s 58% premium acquisition of BRZE. Risk appetite improved across application software.

Zhiyuan 2513.HK / MiniMax 0100.HK | yesterday -6.4%, pre-market +2.5% today
They fell 6.4% and 5.8% yesterday: DeepSeek V4.1 Flash and 0100.HK’s M3.1 Flash kicked off a Flash price war, compounded by tightening China-U.S. policy. This pressure remains near-term.
Dolphin view: Policy hits are concentrated on the ‘third-party cloud hosting + revenue share’ offshore route. Anthropic valuation bias is lower, and with competition and regulation, China model premiums may be forced tighter.

GEV -2.0% / ETN -2.4%
Barclays said if scarcity-driven compute pricing and margins normalize, it is mildly negative for power equipment names like ETN, HUBB, NVT, and GEV, but positive for hyperscalers and model labs. This reflects a redistribution of economics.
BE reports on 10/22. Investors will watch guidance on orders and margins.

SPCX | $1.95tn | -0.1%
Flat into the close, then up nearly 7% after the Q3 print; see highlights for details. Momentum reflects confidence in SI economics.
Q4 capex guidance is $35–40bn, with backlog at $63bn and about $42bn expected to be recognized within a year. By end-Q2 2027, 440k Vera Rubin training cluster boards will be online.
Dolphin view: SI revenue rose $5.0bn QoQ with sub-1-year payback, proving scarcity premiums still expanding. This supports the near-term bull case.
But this is bare-metal compute rental with 90-day termination clauses, and premiums will compress as supply-demand balances in 2027–28.
TSLA | $1.48tn | +1.5%
Strength into earnings. Reuters said EU approval for FSD is progressing, and SPCX investors are pressuring Musk to pursue the merger.
Earnings are after-hours tonight; see preview below. FSD metrics and Optimus remain key swing factors.
HSAI +8.3% / XPEV +7.6%

NFLX | $286.0bn | -1.7% (after-hours -5.8%)
Q3 revenue +12% (+11% FX-neutral), continuing to decelerate. OP was $6.8bn with OPM at 53%, but the YoY improvement came from a low base and spending mismatch.
Q4 revenue guidance at $13.4bn, growth flat vs Q3, and OP at $3.5bn, 6% below consensus. Even adding back less than $200mn of severance, it still misses.
Full-year ad revenue guided down to about $2.7bn (from $3.0bn), and FCF cut by $0.5bn to $12.0bn. Buybacks of $10.8bn in the first three quarters already exceeded the $9.5bn FCF in the same period.
New CCO Peter Rice (ex-Fox/Disney) took over, likely to boost reality, gaming, and live content to offset efficiency gains from layoffs. See call notes for details.
Dolphin view: The beat quality is low, and Q4 guidance is the key. This report is not enough to lift near-term confidence.
At about $270bn after-hours, NFLX trades at ~19x forward P/E, back to pandemic-era levels. Downside is limited, but added content spend will eat layoff-driven efficiencies, with unclear 1–2 year growth paths, making it too early for a high-conviction bet.

SMCI | +11% after-hours
Guided FQ1 revenue to $18.5–19.5bn, far above the ~$15.0bn street. See trading highlights for context.
TSEM | -6.8%
SemiAnalysis issued a bearish report on its silicon photonics foundry position, citing competition from STM, GFS, and UMC. The stock fell as much as 10.7% intraday.
BRZE +51.2% / MNDY +7.6% / HUBS +6.9% / FIG +6.1%
CRM agreed to acquire BRZE for $47.50/share in cash (EV about $5.7bn, 58% premium), lifting application software broadly. M&A sentiment supported the group.
SE | -8.9%
The CEO memo said it will open its own cloud to enterprise clients and consider spinning off Monee. The market worries about heavier capex.


| Date | Event | Focus |
| Wed, Oct 21 | Jensen Huang Berlin GTC keynote (17:00) | Physical AI, European sovereign AI |
| Wed, Oct 21 | META, TSLA, LRCX, TXN, IBM Q3 (after U.S. close) | See earnings previews below |
| Thu, Oct 22 | WDC, NOK, BE Q3; U.S. initial claims; MU Taoyuan strike | HDD pricing; Taiwan capacity risks |
| Fri, Oct 23 | U.S. Oct S&P PMI flash (21:45), Michigan sentiment | Input prices |
| Mon, Oct 26 | Anthropic may publicly file S-1 (per IFR) | Final revenue, cash flow, compute commitments |
| Tue, Oct 27 | STX Q3 | HDD capacity additions |
| Wed, Oct 28 | MSFT, GOOGL, NOW Q3; ORCL Analyst Day; AAPL event | Azure, cloud and search, ORCL financing |
| Thu, Oct 29 | FOMC (02:00 Beijing); AMZN, INTC, SNDK Q3 | Oct hike odds ~13% |
| Fri, Oct 30 | BoJ rate decision | Signals for a Dec hike |

META | after-hours Oct 21
Watch: Buy-side expects 2027 opex at $210–220bn (sell-side $203bn) and capex at $225–250bn (sell-side $198bn). Funding plans are the swing factor for valuation.
Wells Fargo already cut 2027 EPS to $31–32. Guidance framing and capital allocation will be critical to sentiment.
The biggest asymmetry is financing: equity raises require a sweetener on the call, while no financing could trigger large short covering by underweight long-onlys. Management tone matters.
Dolphin focus: 2027 capex and financing route, Muse DAU and retention, ad impressions and pricing, and utilization of Prometheus clusters (about 1mn GPUs). Our work suggests Muse subscriptions add about 5% revenue, with bigger value in protecting the ad moat.
TSLA | after-hours Oct 21
Watch: Q3 deliveries of 486.5k are priced in. Focus is on special committee progress on a SPCX merger, EU FSD approvals, and Optimus production cadence.
Dolphin focus: Auto GPM ex-credits, paid FSD users, Robotaxi unsupervised miles, and Optimus line progress. These will shape the 2027–28 narrative.
LRCX | after-hours Oct 21
Watch: Semi-cap has sold off into prints with de-rated multiples. Institutions think TXN’s mature-node pricing may guide the sector more than LRCX’s print.
Dolphin focus: Memory customer mix, 2027 WFE outlook, and etch/deposition uplift from 4F² and other new architectures. Execution on HBM tooling matters.
WDC | after-hours Oct 22
Watch: Nearline HDD LTAs are locked through 2027/28. Bears worry about capacity additions by late 2028.
Dolphin focus: Price per TB, LTA coverage horizon, and 2027 capacity plans. Supply discipline remains key.
Recent daily recaps
2026-10-20: Dolphin Daily | AWS says compute is sold out, CoreWeave rushes to sell stock: who pays for the AI dinner?
<End here>
Risk disclosure and statements: Dolphin Research disclaimer and general disclosures

Taiwan Semiconductor
USTSM

Corgi SK hynix 2x Daily ETF
USSK

Oracle
USORCL

NVIDIA
USNVDA

Meta Platforms
USMETA

TSMC US SDR 300to1
SGUTSD

ORACLE CORP DEPOSITARY SH REP 1/2000TH PFD SER D
USORCL-D

Apple
USAAPL

Z.AI
HK02513

Z.AI HK SDR 100to1
SGHZAD

00100
HK00100

TSLA
USTSLA

GOOGL
USGOOGL

GOOG
USGOOG

GOOGN
USGOOGN

MU
USMU

SKHY
USSKHY

UNXD
SGUNXD

SPCX
USSPCX

UXSD
SGUXSD
The copyright of this article belongs to the original author/organization.
The views expressed herein are solely those of the author and do not reflect the stance of the platform. The content is intended for investment reference purposes only and shall not be considered as investment advice. Please contact us if you have any questions or suggestions regarding the content services provided by the platform.