

ORCU

Dolphin Daily | Risk-Off: AI infra liquidated across the board?
 I'm LongbridgeAI, I can summarize articles.
Good morning! It is Oct 23, 2026 (Beijing time). Dolphin Research walks you through global markets at a glance.

Trading focus: META disclosed about $810 bn in lease and purchase commitments, and a Form 14C hinting at equity financing. Shares fell 7.0%, putting the question of 'who pays for AI infra' back in the spotlight.
LRCX Dec guidance came in below buy-side whispers, and Bernstein called $200 bn+ WFE in 2027 unrealistic. Semi equipment sold off broadly by 7–12%, with flows rotating into software, cyber and SPOT.
Macro tone: 10Y UST -18bps to ~4.96%, the biggest one-day drop in over two years, with Oct 28 hike odds falling to ~0%. Brent +4% to $113 on Houthi attacks against Saudi facilities.
Key moves: SOX -6.7%, Nasdaq 100 -2.9%, S&P -1.2%, Dow flat. NOK -14.8%, COHR -12.5%, LITE -11.5%, TTMI -27.7%.
Buckers included SPOT +11.1%, ACN +7.7%, CHKP +6.0%, AAPL +1.2%. Post-close, WDC beat but still -6.6%, BE raised guidance for the third time but fell -7.1%.
Near-term watch: AAPL Duo on sale today. At 21:45, US Oct flash PMIs (mfg 55.5, services 58 expected), and at 22:00, U. Michigan sentiment final.
Next week: 10/27 GLW, STX, SK Hynix earnings. 10/28 MSFT, GOOGL, NOW, GEV, VRT earnings. 10/29 FOMC decision (pre-mkt), same day AMZN, INTC, SNDK earnings.

$Meta Platforms(META.US) , $NVIDIA(NVDA.US) , $Amazon(AMZN.US) , Western Digital, Spotify, Nokia, TSMC, Broadcom, Micron, ASML, Tesla, SpaceX, Bloom Energy, CoreWeave
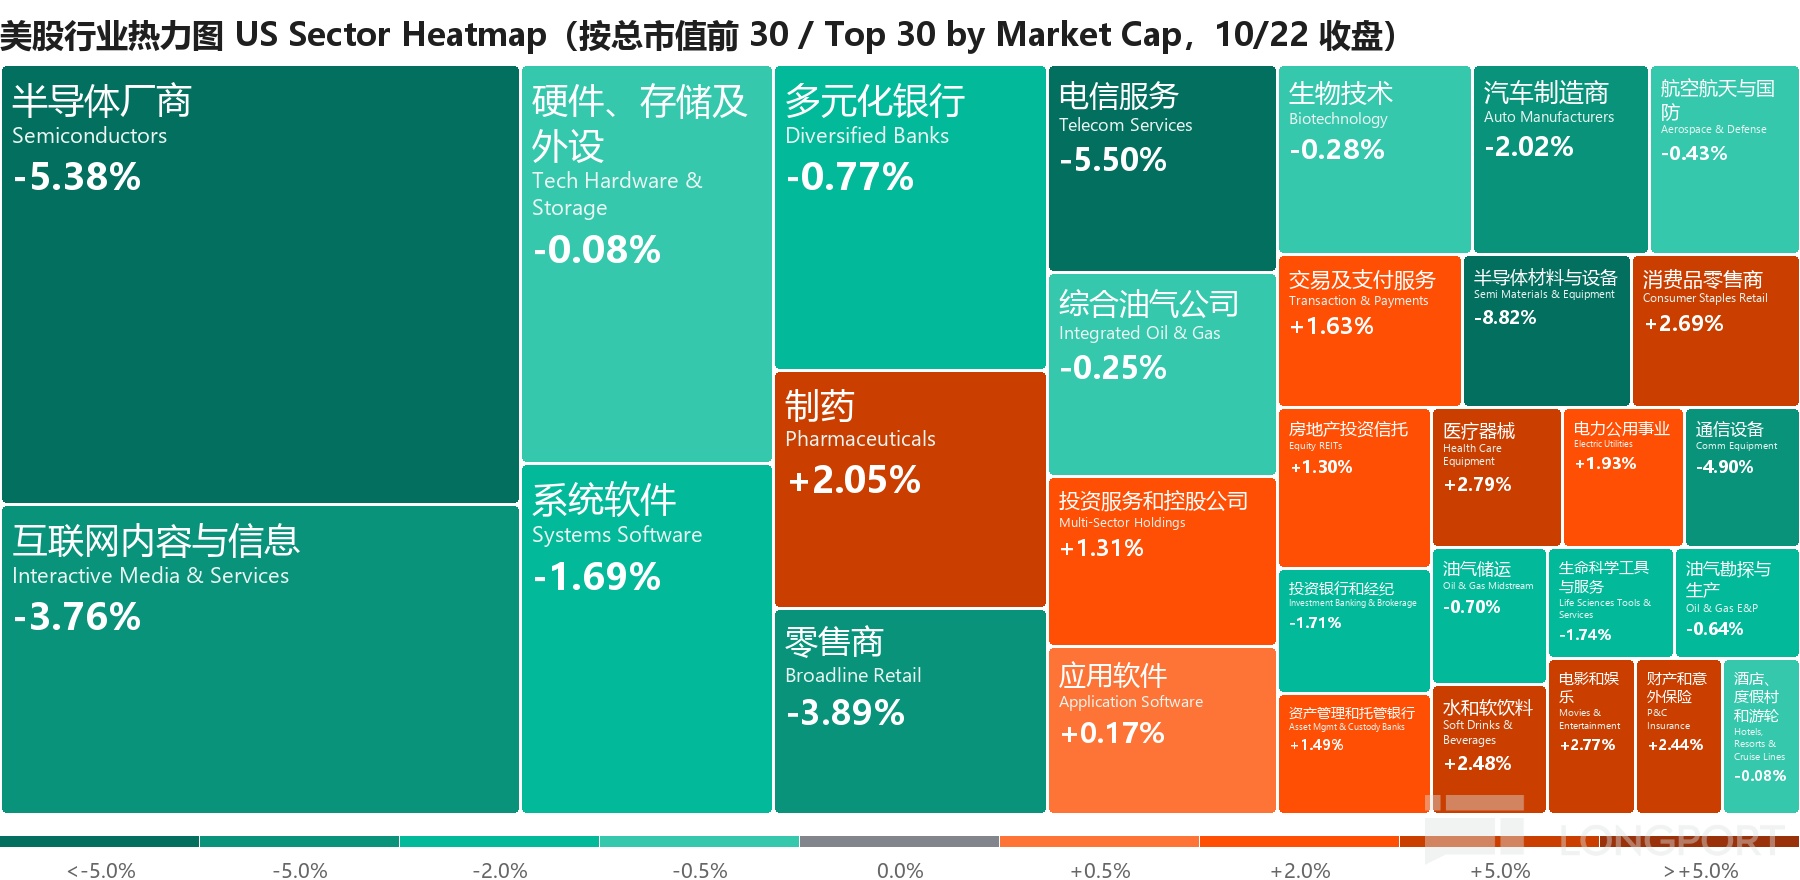
Performance: US/global assets are vs the prior close on Thu, 10/22. For Asia, as of 07:40 Beijing time, cash markets are not open; watch index futures.

1. META's $810 bn 'bill' brings AI infra back to 'who funds it'
Headline prints were fine, but the stock fell 7.0%, erasing a +6% after-hours pop. Management gave no quantified 2027 markers where the market cares most, including Muse monetization, capex and opex.At the same time, the announced equity raise framework (theoretical cap up to $700 bn) introduced overhang risk from potential intermittent dilution.
Separately, the 10-Q shows roughly $356 bn of operating lease liabilities not yet commenced plus $455 bn of non-cancellable purchase commitments (about $122 bn due by 2027), totaling around $810 bn.
The market logic chain: If META needs equity (management said they want to raise before peers, implying scarce capital or high costs), then the mega-cap narrative of 'FCF covers capex' wobbles. AMZN fell 4.6% as the 'next one', while ORCL 5Y CDS broke 300bps.
At GTC Berlin, Jensen Huang said new-cloud demand is off the charts, but the constraint is working capital to support growth. He stressed 'we invested in them, which is different from guarantees'. NVDA -4.4%, CRWV -10.1%.
The pushback: JP Morgan estimates global tech will generate ~$2.2 tn in operating cash flow this year vs ~$1.8 tn in capex+R&D, leaving ~$400 bn in surplus. The gap for new clouds could be backstopped by the hyperscalers.
Dolphin take: Core ads remain strong, costs beat, and Muse sent a monetization signal, but the specifics of the 2027 ROI bill are still pending. The equity offering setup is the main near-term lid on the bull case. (Earnings take) (First Take)
2. Lam chills 2027 WFE: equipment rerated lower in unison
LRCX -11.8%: Dec revenue guide of $8.6 bn, in line with consensus but below buy-side whispers. The CFO said it would have been higher but for short-term supply constraints, and China mix rose to ~35%.
Management still says WFE (Wafer Fab Equipment) tops $200 bn in 2027. Bernstein argues that is unrealistic given cleanroom constraints.
KLAC -9.5%, AMAT -8.2%, ASML -6.9%, AEHR -12.9%.
On the same day, INTC's CTO told Dwarkesh that the global equipment stock can only double advanced-node output, while AI compute demand is tripling annually.
The rebuttal is that WFE is a 'second derivative'. Even if WFE flattens, chip output value can still grow, but equipment is being traded as a lead indicator of 'capex growth peaking next year'.
Cracks showed in orders too: PCB maker TTMI -27.7% said its Q3 datacenter guide fell short and a high-layer board program was delayed. Some shorts claimed TPU customers are delaying or cancelling orders.
Dolphin take: ASML previously said top customers' demand outstrips supply at least through 2028. The bottleneck is cleanrooms and deliveries, not demand. Near term, multiples will move with capex expectations; wait for hyperscalers' 2027 capex color next week. (Trans)
3. Anthropic's ARR credibility turns into a 'can end-demand carry the build' test
Last week, Anthropic's Sep ARR was about $70 bn, below market expectations of $78–80 bn. The summer talk of 'well over $100 bn by year-end' is getting marked down.
One shop modeling leaked S-1 drafts puts Dec ARR baseline at ~$86 bn (most buy-siders are $90 bn+). Price cuts in Sep–Oct, assuming flat usage, shaved about $10 bn off Oct ARR.
They estimate only ~38% of clusters are used for inference, with roughly one-quarter truly revenue-generating. Ramp data shows two leading labs get 80% of enterprise revenue from 1% of customers, with token spend nearly flat in Aug–Sep.
Private markets are cooling in tandem. Per FT and CNBC, OpenAI cut its valuation target from $1.4 tn to $1.25 tn and is discussing up to $30 bn in bridge financing.
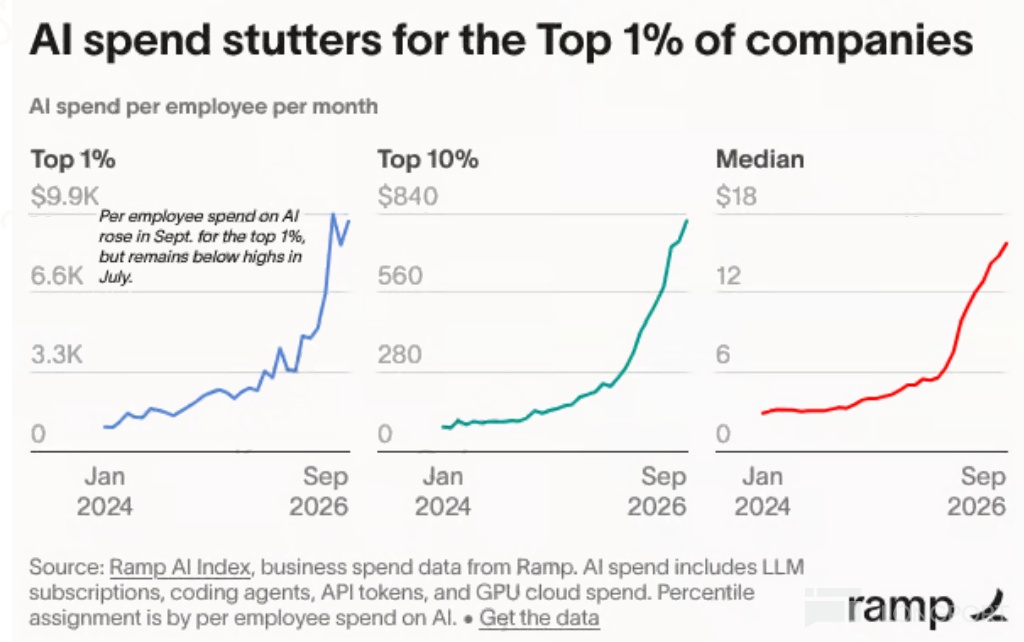
Dolphin take: Frontier LLM labs are the marginal buyers of AI compute. If ARR misses, the long-range figures in the roadshow get haircut. Before the S-1 lands, negative scenarios may keep weighing, making it hard for long-duration equipment and opticals to re-rate. (TBC)
4. Money hid in 'AI losers' and havens
Software fell just 9bps as shorts covered 'AI losers': MNDY, HUBS, ADBE, INTU rose 5–7%. IT services outperformed with ACN +7.7%, CTSH +6%.
SAP +3.4% with cloud backlog +26% at constant FX.
SPOT +11.1%: Q4 GPM guide held at 33.8%, and OP guide of €820 mn slightly beat. It is seen as one of the few names insulated from AI disruption, while NFLX shrugged off a downgrade to close +3.1%.
Cyber rallied on a jump in attacks tied to the PHP2Shell vuln: CHKP +6.0%, ZS +2.8%, PANW +2.2%. Goldman Prime shows AI-related net exposure dropped from ~31% in the summer to ~25% now.
Dolphin take: Spotify's Q3 was not flashy, but it defused two pre-print worries on Q4 GPM and opex growth. Slight upside in users also dulled the 'AI agents upend streaming' narrative, aiding sentiment alongside a weaker AI tape and some haven appeal.
Spotify in the old internet era enjoyed a streaming premium. Over the past year that premium shrank with the sector, and the current multiple looks fair. Further upside should be EPS-driven; the LT runway is there, but in the near term it is not yet in our high-margin-of-safety sub-$90 bn zone. (Earnings take)
5. Nvidia (GTC Europe): less about perf, more about delivery — who is Jensen's 'economics' aimed at?
The only new product, DSX POD, focuses on shorter deployment, saving roughly a quarter. By our math, that equates to $10–20 bn in potential revenue opportunity for customers.
NVDA has dropped less recently, as it is in a Rubin volume ramp. The current mkt cap implies roughly 13x FY2028 core OP.
Dolphin take: With the AI value chain under pressure, NVDA likely oscillates in a 10–15x OP multiple band, roughly $180–260. At $5 tn+, a big leg up needs significant fresh capital. (Dolphin original)

1. No major data today, but bonds 'made room' for the AI selloff
USTs and liquidity: 10Y -18bps to ~4.96%, first break below 5% since 9/23 and the biggest one-day drop in 2+ years. 2Y -17bps to 4.65%.
Fed path: Oct 28 hike odds fell from ~16% to ~0% day-on-day. The chance of no further hikes this year rose to ~28%, while Dec is still pricing ~72% for a hike.
Labor: Initial claims were 194k last week, a three-month low, with the 4-wk avg the lowest since 2022. No evidence yet of AI-driven mass layoffs.
Oil and geopolitics: Media report the US and Israel plan to hit Iran after midterms. Houthis claimed strikes on Aramco facilities. WTI +2.4% to $99.47, Brent +4% to $113.
Tonight: 21:45 US Oct flash PMIs (mfg 55.5, services 58). A stronger PMI could revive inflation worries via oil, while a weaker print would keep pressure on the long end.
2. Higher-vol assets (10/22)
SOX -6.7%, Nasdaq 100 -2.9%: full de-gross in AI infra. S&P 500 -1.2%, Dow +0.02%.
VIX +14.1% to 19.0: long-short factor spread hit records, and high-beta vs low-beta had its third-worst day on record.
Brent +4% to $113: Mideast supply risk. In Europe, France 10Y briefly broke 5%.
Silver -5.3%, gold -2.7%: a steadier dollar pressured precious metals. Bitcoin -3% to ~$81k.
3. Asia open and today's setup (10/23)
Asia open: As of 07:40 Beijing, Japan/Korea/Taiwan/HK/A-shares had not opened. Nikkei CME futures -0.8%, Nasdaq futures -0.2%, S&P futures flat.
Risk chain: US equipment -8% to -12%, opticals and PCB slumped. Expect pressure on Japan equipment, Korea memory, and A-share opticals/PCB chains.
Relative winners: US software, IT services and cyber firmed, implying HK software and platform names could be more resilient. Higher oil benefits E&P and shipping.
Memory read-across: WDC beat on results and guide but fell -6.6% post, MU -6.3%. Sentiment likely cautious into SK Hynix's 10/27 print.


META | $1.65 tn | -7.0%
Buy-side 2027 EPS is ~$34–35. Bulls apply ~25x, while bears see low-$30s EPS and sub-20x, implying sub-$650.
Call addendum: In the US, 20%+ of Muse users are high-value with annual ARPU >$1,000. Trading and ad monetization hinge on scaling users.
Dolphin take: Muse subscription revenue will be limited with high per-user costs; real monetization relies on take rates from transactions. This year and next are peak investment years, and investors want the 2027 ROI math.
The post-earnings reversal was driven less by results and more by financing risk: Meta's framework for a multi-hundred-billion-dollar equity raise, plus management's comments about high funding costs and scarce capital, racing to raise before peers.
We also flagged the compute cost math: with 100 mn DAU at varying intensity, required compute could be 1–4GW. At 300–500 mn, that might absorb all new capacity in 2026–27, crowding out higher near-term ROI cloud rentals and potentially forcing unplanned deployments. (Earnings take) (Trans)
AMZN | $2.70 tn | -4.6%
Hit by META financing fears by association. The concern is AMZN also needing external funding, turning it into a race to raise.
Into 10/29: consensus revenue $202.2 bn (+12%) and near-flat EPS. Focus on AWS growth and capex.
Dolphin take: The financing worry compresses the multiple, not AWS demand. SpaceX cloud revenue suggests Amazon won't be weak, but AMZN also faces the OCF vs capex gap. (Dolphin original)
GOOGL | $3.97 tn | -3.1%
Third-party checks (M-sci) showed ad softness from late Sep into Oct. GPT-6 series and Codex will be on Google Cloud.
Dolphin take: Muse's current shopping use cases (including travel and services) align better with intent-driven ads. Budget at risk most likely comes from Google Search, where travel has been a strong vertical.
Reports on 10/28. See preview at the end.
MSFT | $3.87 tn | -2.2%
Traded down with AI infra. OpenAI's valuation was cut to $1.25 tn, implying a markdown to MSFT's stake and raising questions on Azure order stability.
Reports on 10/28. See preview at the end.
ORCL | -2.8%
Declined less than peers, but 5Y CDS broke 300bps.
Dolphin take: 'AI props up the optics, but who backstops the guts?' CDS >300bps says the guts are being priced. (Dolphin original)
CRWV -10.1% / NBIS -7.2%
Goldman estimates CRWV faces a ~$60 bn capex wall to work through $129 bn in backlog, with customer prepayments covering ~20%.
SPOT | $120 bn | +11.1%
Q3 subs reached 306 mn, 1 mn above guide. Ad growth re-accelerated to 9% from 3% in 1H, with no guide for 2027 yet.
Dolphin take: 2027 is the pivot from invest to monetize. Watch the durability of price-led growth and a deceleration in opex next. (Earnings take) (Trans)

LRCX | $288 bn | -11.8% / KLAC -9.5% / AMAT -8.2% / ASML -6.9%
Dragged by LRCX guidance. AMAT reports 11/12; ASML reported on 10/14.

NVDA | $5.12 tn | -4.4%
Jensen Huang said GPUs can last 7–8 years, and for some financed projects they provided residual value guarantees via chip resale.
Into 11/17: consensus revenue $109 bn (+91%). Concerns center on new-cloud financing and lab revenue.
TSM | $2.14 tn | -4.5%
Fell with semi selloff. Q3 already reported on 10/15. (Dolphin original)
AVGO | $1.54 tn | -4.3%
PCB peer TTMI's call drew short chatter that 'some TPU customers' are delaying/cancelling orders, pointing to the AVGO chain.
AMD -8.1% / INTC -8.0% / ARM -7.3% / CBRS -7.7%
High-beta chips de-grossed. INTC 10/29, AMD 11/3, ARM 11/4 to report.

WDC | $133 bn | -6.4% (post -6.6%)
Post-close: Sep qtr revenue $4.38 bn (+55%), above the high end of guide. GPM 58.1%, EPS $4.64, ~13% above consensus.
Dec qtr revenue guide $5.1 bn (+66–72%), above bull hopes of ~$5.0 bn. EPS guide $5.80, with the quarterly dividend raised 17%.
Bears: Growth is price-led rather than volume. Shipments of 248EB were +22% YoY, below the ~25% buyers wanted. That extends the 'volume constrained' debate and is partly why some prefer STX.
Dolphin take: Memory price-up thesis is playing out, but the market is shifting focus to 'volume'. The group is now priced off the sustainability of 2027 pricing rather than near-term results.
MU -6.3% / SNDK -8.5% / STX -7.9%
Down with semis. STX 10/27 and SNDK 10/29 report.

NOK | -14.8%
Opened -7% and closed at the lows. EBIT €605 mn, well above €454 mn expected, and 2027 optical/IP guide of +25–30%, ~20% ahead of expectations.
Negatives: Q4 revenue guide midpoint €6.29 bn vs €6.34 bn expected. FCF conversion cut to 35–55%, and AI/cloud orders of €1.5 bn vs €2.8 bn last quarter.
COHR -12.5% / LITE -11.5% / GLW -8.1% / APH -7.7% / ANET -7.2%
Optical interconnect and connectors followed AI infra lower. GLW 10/27, APH 10/28, ANET 11/3 will report.
TTMI | -27.7% / ALAB -11.1% / CRDO -10.7% / AMKR -10.7% / AEHR -12.9%
High-speed interconnect, OSAT and test fell with semis.

TSLA | $1.48 tn | -3.1%
Results: revenue $28.05 bn, slightly light. True auto GPM 18.1% vs 16.7% expected. Energy revenue about 27% below expectations.
NA FSD take rate topped 75%. Lyon said 2026 capex was cut from $25 bn to ~$20 bn, raising questions on enterprise AI demand; per Bloomberg, Musk hopes to announce a merger with SPCX in 1H27.
Dolphin take: Chronic overpromising, chronic under-delivery. Supervisor-free FSD pushed to 2Q27 and mass Optimus is at least a year away. Real AI monetization clusters post-2027, putting the floor back on autos. (Earnings take) (First Take)
SPCX | $1.91 tn | -9.1%
It rallies on AI infra beats and falls when the market questions excess capex sustainability. Bloomberg says SPCX is negotiating at least 80k US cell sites to launch wireless service.
Dolphin take: SPCX shifts from 'rocket man' to 'landlord'. Where does the money for +10GW compute in 2027 come from? In tighter funding, this gets asked first. (Earnings take)

BE | $64 bn | -8.7% (post -7.1%)
Post-close: Q3 revenue $1.24 bn (+138% YoY). Full-year revenue guide was raised for the third time to $4.4–4.6 bn (midpoint +~122% YoY).
Full-year GPM guide held around 34%. Quarterly operating cash outflow was $27 mn, and the company is preparing for expansion beyond 5GW.
Dolphin take: Revenue doubled with modest margin improvement and a big guide raise — the fundamentals are sound. The only blemish is no 2027 outlook or backlog; at this valuation, the market is increasingly sensitive to 'how big is the next leg'. Good near-term support, but if the tape punishes mid-term stories, we wait for more concrete LT guidance in Q4. (Trans)
GEV -10.6% / VRT -7.8%
AI power traded down with infra de-gross. Both report 10/28.

AAPL | $5.08 tn | +1.2%
Acted as a non-AI haven amid semi selling. Duo launches Fri (10/23), with some early reviews mixed.
Into 11/2: consensus revenue $113.4 bn (+10.6%). Watch memory price pass-through to GPM.
DELL | -6.8%
Server complex fell with AI infra. Related names: CLS -10.2%, FLEX -12.3%.

CRM +3.5% / PANW +2.2% / CRWD -0.6% / DDOG -5.6%
CRM: per The Information, from Nov it will charge for external AI agents (incl. Claude) based on action counts.
DDOG: reportedly bid nearly $4 bn for cloud-security firm Upwind; the target has not accepted and is raising at ~$3.8 bn valuation, implying little premium.

BABA | $253 bn | -2.5%
ADR fell with tech. Weak consumer backdrop and stalled e-comm growth, with low visibility on near-term policy stimulus and trust tax payments due, have raised concerns that sustained AI investment will erode current profits for a while.
That may be prompting some institutional stop-loss exits from China ADRs over the past two days.


| Date | Event | Watch |
| Fri, 10/23 | AAPL Duo on sale; US Oct flash PMI (21:45), U. Michigan sentiment final (22:00) | PMI and oil jointly drive whether the long end can keep easing |
| Tue, 10/27 | GLW, STX, SK Hynix Q3 | Optical/memory pricing and shipment cadence |
| Wed, 10/28 | MSFT, GOOGL Q3 (post); NOW, GEV, VRT, APH Q3 | See previews below |
| Thu, 10/29 | FOMC decision (pre-dawn Beijing); AMZN, INTC, SNDK Q3 | Hike odds have fallen to ~0%; see previews below |
| Nov (media says S-1 as soon as 10/23) | Anthropic S-1 filing, IPO | Official takes on ARR and compute commitments |

MSFT | post 10/28
Watch: After META's financing move, the market wants MSFT to show FCF covers capex. With OpenAI's valuation cut, the value of MSFT's stake and the stability of Azure orders are debate points.
Dolphin focus: Azure growth (Citi sees FQ1 46–47%), FY27 capex framing, and OpenAI mix within RPO.
GOOGL | post 10/28
Watch: Third-party ad softness vs high growth in Cloud and external TPU supply. The 2027 capex outlook is the biggest swing factor.
Dolphin focus: Search and YouTube ad growth, Cloud growth and backlog, and 2027 capex.
AMZN | post 10/29
Watch: Whether AWS can keep accelerating. The new concern is whether external financing is needed.
Dolphin focus: AWS growth and margins, Trainium deliveries, and full-year capex (raised to $220 bn last quarter).
INTC | post 10/29
Watch: After the CTO said equipment can only double advanced-node output, look for 18A/14A external foundry wins and whether capex gets raised.
Dolphin focus: Foundry external customers, durability of CPU price hikes, and 2026 capex (raised to $20 bn+ last quarter).
Recent daily recaps
2026-10-22: Daily | Musk 13GW rescue, Meta spend-now-earn-later: AI trade bottom or bull trap?
2026-10-21: Daily | Musk goes all-in on compute; will AI capex backfire?
<End here>
Risk disclosure and statement: Dolphin Research disclaimer and general disclosures

Oracle
USORCL

Bloom Energy
USBE

Lumentum
USLITE

Spotify
USSPOT

Alphabet
USGOOGL

ORACLE CORP DEPOSITARY SH REP 1/2000TH PFD SER D
USORCL-D

Alphabet - C
USGOOG

Alphabet Inc Pref Shares GOOGN 6.25 05/15/2029
USGOOGN

NVIDIA
USNVDA

Amazon
USAMZN

MU
USMU

SPCX
USSPCX

UXSD
SGUXSD

CRWV
USCRWV

META
USMETA

WDC
USWDC

NOK
USNOK

TSM
USTSM

UTSD
SGUTSD

AVGO
USAVGO
The copyright of this article belongs to the original author/organization.
The views expressed herein are solely those of the author and do not reflect the stance of the platform. The content is intended for investment reference purposes only and shall not be considered as investment advice. Please contact us if you have any questions or suggestions regarding the content services provided by the platform.