

SPXL

Dolphin Daily | NVDA drops another 5%; 50bp hike on the table; neoclouds on trial again?
 I'm LongbridgeAI, I can summarize articles.
It is Nov 11, 2026 Beijing time. Dolphin Research brings you a one-glance read on global markets.

What’s trading: Oct US CPI and core CPI rose +0.4% and +0.3% MoM, both above estimates. Fed’s Waller and Logan sounded hawkish, lifting the odds of a 50bps hike in Dec from 0 to ~15%.
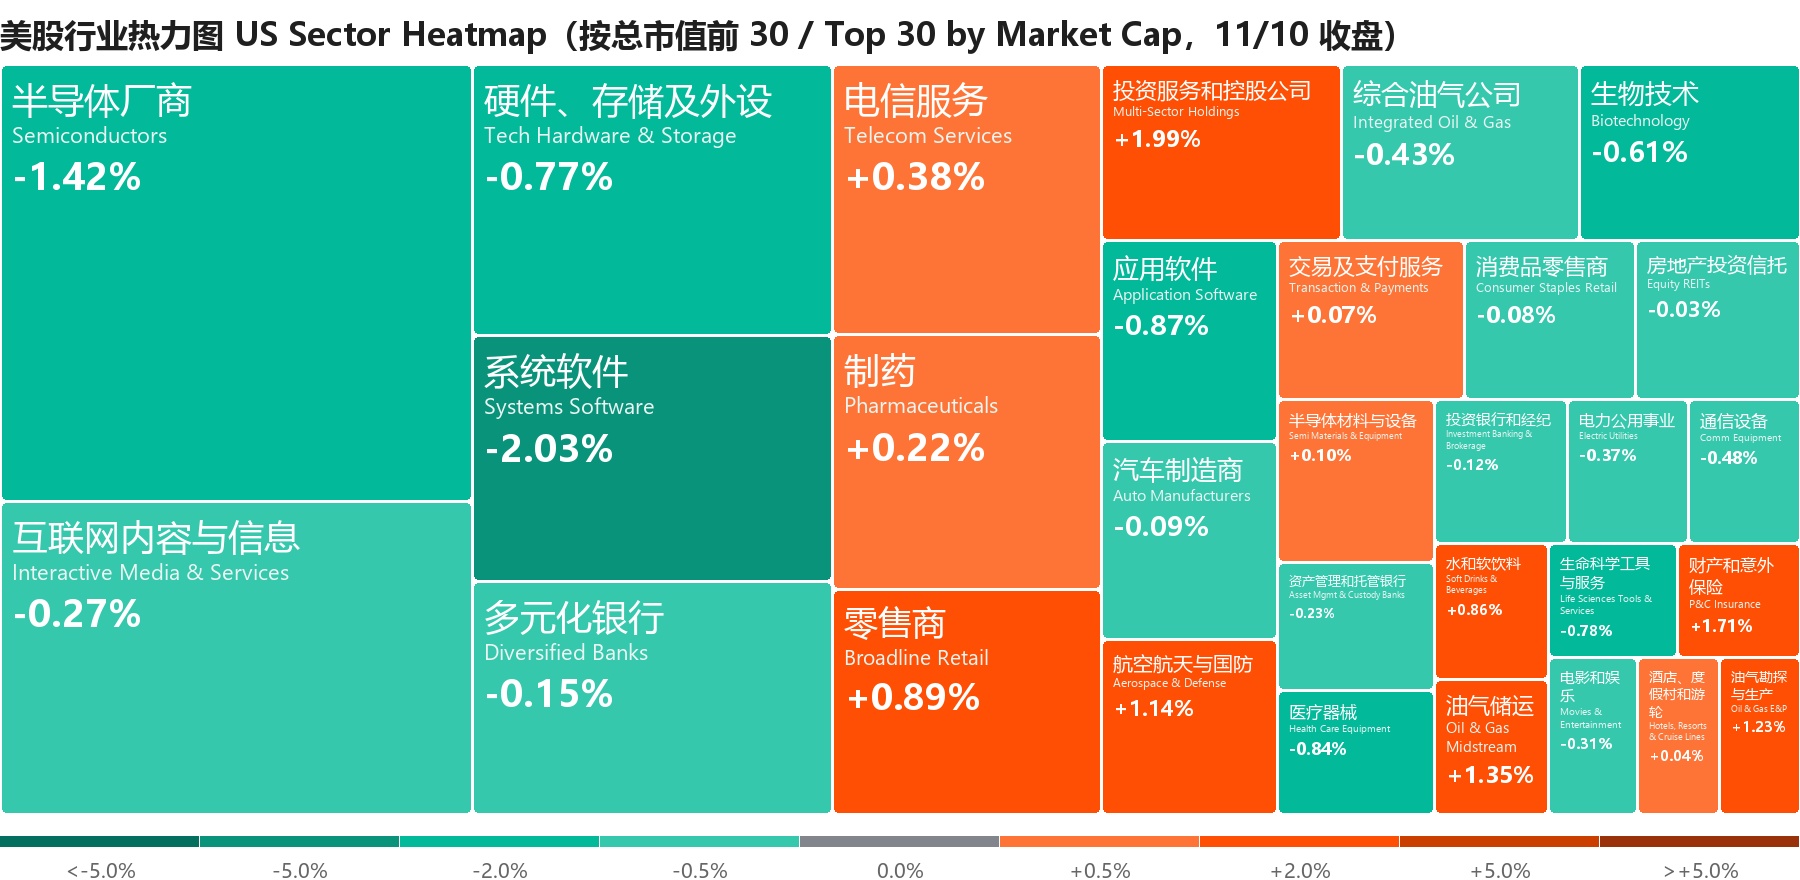
The Nasdaq fell 0.7%, with Tech the laggard. Nvidia slid another 5.5%, down ~10% in two days, as money rotated into defensives such as Staples and Health Care.
Anthropic guided an IPO range of $70–78. It launched Office-like productivity tools during the roadshow, and Microsoft fell 2.2%.
CoreWeave posted Q3 revenue +168% YoY and backlog up to $132.5bn, and raised full-year guidance. Shares rose ~5% after-hours, with Nebius following higher.
Macro: The 2Y UST yield jumped 18bps to 4.725%, the biggest one-day rise since Apr 2025. The 10Y rose to 4.99%, briefly topping 5.01%, as demand for the $42bn 10Y auction came in soft.
Key movers: Nvidia -5.5% led declines. Broadcom +3.9%, TSMC +2.0% and AMD +1.3% drew dip-buying.
Coherent -4.7%, and power equipment name GE Vernova -3.9%.
Near-term watch:
Thu: Cisco, Applied Materials, Nebius, SMIC and Cerebras report. Fri: PPI.
Next week: 11/17 Nvidia earnings. 11/18 Jensen Huang to testify before House committees; Anthropic pricing after-hours, listing 11/19.

$NVIDIA(NVDA.US) , $Coreweave(CRWV.US) , $Microsoft(MSFT.US) , $Broadcom(AVGO.US) , $AMD(AMD.US) , $Taiwan Semiconductor(TSM.US) , $Alphabet(GOOGL.US) , $Amazon(AMZN.US) , $SoftBank Group Corp.(9984.JP) , $GE Vernova(GEV.US) , $Nebius(NBIS.US) , $Coherent Corp.(COHR.US) , $ZJ INNOLIGHT(03308.HK) , $SK Hynix(SKHY.US) , $Alibaba(BABA.US) , $S&P 500(.SPX.US) , $NASDAQ-100(.NDX.US) , $iShares Semiconductor ETF(SOXX.US)

1) CPI beats, Waller floats 50bps: debate shifts from ‘if’ to ‘how much’
Russell 2000 -0.7% / Nasdaq 100 -0.6% / S&P 500 -0.4% / SOX -0.4%
Oct CPI rose +0.4% MoM and core +0.3%, topping 0.3% and 0.2% estimates. Core printed 0.3% for a third straight month, and there is no YoY reading due to last year’s shutdown.
Breakdown: Shelter +0.3% and drove over a third of the monthly gain; Food +0.5%; Energy +0.7% (gasoline, seasonally adjusted, +1.0%); used cars -1.2%. Only 1 of 70 analysts expected such a hot print.
Some houses think Energy may have peaked, as crude and refined product prices fell meaningfully after the survey month. Hours before the release in London, Waller said if core is ~0.3% or higher, the Fed should consider a 50bps hike in Dec, arguing a mere 25bps would hurt credibility.
Dallas Fed’s Logan said at least two more hikes may be needed, potentially at a faster clip this winter. Governor Bowman warned that subpar AI ROI could trigger a sharp equity pullback, and AI-related liabilities could break $800bn this year.
CME FedWatch now puts Dec +25bps at ~84%, and +50bps climbed from 0 to ~15%. The 2Y yield rose 18bps, while S&P 500 Tech fell over 1%, the worst among 11 sectors.
Street trading desks flagged net selling by asset managers and hedge funds, with pressure concentrated in mega-cap Tech. Ex-NVDA, overall tape was thin, with S&P 500 constituent volumes ~15% below Avg.
Positioning is already light: Goldman’s PB shows US fundamental L/S funds cut gross leverage by 8.7ppt WoW, the biggest since Mar 2020. Net leverage at 43.3% sits at a five-year low percentile.
2) Anthropic $70–78 range, launches office suite on roadshow day: Microsoft takes an early hit
Amazon +1.5% / Alphabet -0.3% / Microsoft -2.2%
Anthropic updated its F-1: 825mn shares offered at $70–78, with 97% primary. At the top end, proceeds up to $64.35bn, and a 124mn-share greenshoe.
Valuation lenses: fully diluted up to ~$1.405tn, and ~$0.92–1.02tn on a basic-share basis. For ref., the May round valued it at $965bn, and pre-IPO chatter once pointed to a $2tn raise.
Corner orders: AMD, Broadcom, Alphabet, Micron, Microsoft, Nvidia, and TSMC will purchase $26bn of Class N shares at the IPO price, exempt from the underwriters’ lock-up.
Financials: 9M revenue $33.24bn, up ~1,200% YoY, with net loss $104.0bn mainly from fair-value changes on converts and derivative liabilities. As of end-Oct, ARR was ~$81bn, up ~$10bn MoM.
Roadshow target: long-term OPM of 35% vs. Q3 at 15%, a 2,000bps+ step-up. Per sources, pricing after-hours on 11/18 and listing on 11/19 under ticker ANT, with books covered within the range.
New products: on roadshow day, Anthropic rolled out Claude Sheets, Claude Whiteboards (paid beta), and opened Claude Data, directly challenging Excel and Office. Microsoft fell as much as 3% intraday, closing -2.2%.
Same day, OpenAI launched a beta ChatGPT feature for merchants to deploy Business Agents, as AI labs race for app-layer entry points. OAI is also speeding up: OpenAI told investors Q3 revenue rose ~50% QoQ to $10bn (vs. 17% in Q2), but operating loss widened from $10.1bn to $10.9bn.
3) CoreWeave prints: $132.5bn backlog, no holdco bond issuance before 2027; shares +~5% AH
CoreWeave -0.5% (AH ~+5%) / Nebius -5.3% (AH ~+5%) / IREN -7.9% (AH ~+2%)
Q3 revenue $3.66bn, +168% YoY, above the $3.45–3.60bn guide. Adj. OP was $379mn, far above the $200–260mn guide, with OPM at 10% reaching double digits a quarter early.
Backlog reached ~$132.5bn (vs. ~$104bn at Q2-end). Full-year revenue guide raised to $13.0–13.3bn, capex $37–39bn, and year-end ARR $20–21bn.
Financing costs are high: GAAP net loss $709mn, with quarterly net interest expense $846mn and Q4 guided to $1.05–1.15bn. Total debt neared $47bn at quarter-end.
Call color on pricing: across-the-board ~25% hike in July, plus ~10% intra-quarter, with Ampere/Hopper legacy SKUs up 30%–50% QoQ. Qualifying demand into end-2027 is 10x available capacity.
Financing pivot: expects ~$9bn of customer prepayments and deposits in the next three months. No new unsecured holdco issuance before 2027 at current yields, with the next DDTL likely high-IG at a 7.0%–7.5% coupon.
New cloud names still sold off intraday: Nebius -5.3% amid chatter that a key client, Microsoft, is scaling back new-cloud partnerships and may not renew; a sell-side also slapped a Sell. IREN -7.9%.
Dolphin Research view: execution is broadly improving, but the cost of supporting operations is rising in tandem. Interest expense, net new debt, and cash burn all hit new highs. (First Take) (Trans)
4) Rocket Lab: Neutron delayed again — can the SpaceX ‘backup’ still sprint?
Rocket Lab +6.5% / SpaceX +0.7%
Q3 revenue was $268mn, ~4% above consensus, with the beat all from Space Systems. Backlog rose 52% QoQ to ~$3.6bn, Neutron added 8 awards, and list price lifted from $55mn to $70mn.
But Neutron’s maiden flight is now delayed for a third time, from Q4 2025 to 2027, after finding interlaminar voids on the first-stage tank forward dome. Management still won’t give a launch quarter.
Dolphin Research view: revenue, GPM, and orders beat in Q3, marking the trough for margins this cycle. But opex ran above guide, Q4 EBITDA guide is soft, and spend ahead of Neutron’s first flight is still ramping.
Neutron is the Falcon 9 peer and the key for Rocket Lab to graduate from ‘small launcher’ to a ‘SpaceX challenger’. It is also the biggest swing factor in valuation. (Dolphin Research original)(Dolphin Research original)(Trans)

1) CPI beat: core 0.3%, Dec hike size in focus (11/10)
10Y auction: $42bn stop at 5.020% with ~1bp tail, bid-to-cover 2.46, below the prior 2.77 and 10-auction Avg. 2.54, implying soft demand. A $25bn 30Y sale lands Thu.
Fri PPI: JP Morgan sees headline +0.6% and core +0.4% MoM for Oct.
2) Big movers (11/10)
Gold -2.0% to $4,030/oz: yields and USD rose, with spot -3.1% intraday, briefly breaking $4,014.
Silver -2.8% to $51.1/oz: followed gold lower, with spot -3.95%.
Bitcoin -3.1% to ~$73k: ~$630mn of leveraged positions were liquidated in 24 hours, with ~$511mn longs. ETH -4.2%.
DXY +0.56% to 102.23: USD/JPY rose to 158.78.
Brent -1.2% to $91.49/bbl: Mideast talks progressed, with an intraday break below $90 for the first time since Aug. EIA raised its 2026 Brent Avg. forecast to $97.
3) Asia open and today’s setup (11/11)
Asia open (11/11): Nikkei 225 +0.1% at the open; KOSPI -0.6%. Hang Seng futures night session -1.0%, FTSE A50 futures -0.3%.
China importing AI gear: Oct imports +41.6% YoY and exports +35.2%, with IC exports +137.1% and IC import value up nearly 70% YoY. Analysts say AI trade remains the key driver of imports.
Optical transceiver ban threshold looks high: Reuters says the US is weighing a ban on importing China’s new transceivers, potentially setting the bar at 3.2T. Morgan Stanley says such products won’t scale until 2028, limiting direct impact on today’s 800G/1.6T leaders like InnoLight and Accelink.
Pingtouge spin-off: Alibaba plans to spin off its chip unit Pingtouge for a HKEX Main Board listing, with an A1 filed in Sep. This could re-rate domestic AI chip assets.


Nvidia NVDA | $4.08tn | -5.5%
Down ~10% in two days, wiping out ~$430bn in mkt cap, and ~25% in the past month. It closed at $168.89, the lowest mkt cap since late Mar, and Microsoft briefly reclaimed No. 2 globally.
The Information reported Alice Huang helped reroute ~240k Nvidia chips (mainly H100/H200) subject to bans into China, some via Century Litong to DCs serving Alibaba and Tencent. Trading desks say House Republicans are weighing subpoenas, with persistent long-selling and virtually no dip-buy support.
Into earnings (11/17): a shareholder class action was filed in federal court in San Jose. Polymarket puts the odds of Jensen Huang stepping down by year-end at ~14%–16%.
Broadcom AVGO +3.9% / TSMC TSM +2.0% / AMD +1.3%
Street desks say AVGO and AMD continue to trade as primary beneficiaries of NVDA’s downside.
AVGO: with AMD and six others, launched the OCI-MSA for open optical interconnects, claiming 200G power at one-third of pluggable optics. Google’s TPU 8t deploying in 2027 will be built by AVGO.
TSMC: Oct revenue NT$586.89bn (+59.7% YoY, +14.7% MoM). Bloomberg consensus now sees Q4 YoY growth at 63%.
It also plans to subscribe up to $500mn in Anthropic’s IPO and buy up to $500mn in OpenAI preferreds.
Cerebras CBRS | -3.1%
Reports after-hours Thu, slipping with AI chip peers.

Applied Optoelectronics AAOI -7.3% / Coherent COHR -4.7% / Corning GLW -3.3% / Lumentum LITE -1.8%
Reuters says Microsoft is lobbying the Trump administration to halt a ban on importing China’s new optical transceivers. Microsoft has 35 US DCs under construction and 134 planned, and met with OSTP and NSC officials in Sep.
China accounts for roughly two-thirds of global transceiver output (Counterpoint), led by InnoLight and Accelink, while Coherent and Lumentum lack scale substitutes. The FCC is considering a 3.2T threshold; Morgan Stanley expects those products to scale in 2028 and install widely in 2029.
US-listed optical names led declines the same day.

Western Digital SNDK -3.0% / Micron MU -1.1%
Views diverge in memory: DRAM remains firm near term, but commodity DRAM prices may soften in 2028, while NAND spot is down ~20% in two weeks. Samsung could retake No. 1 HBM share in 2027.
TrendForce says DRAM contract prices are rising, and some handset brands are considering reclaimed-and-reballed memory for entry models. Recycled chips could be 3%–4% of phone DRAM this year, rising to 7%–9% next year.
SK hynix 000660.KS / Samsung Electronics 005930.KS | +1.0% / -0.2% (open)
Samsung plans to spend up to KRW 20tn to order EUV tools from ASML, upgrading HBM4 lines at Pyeongtaek P4 and expanding P5.

Meta META | $1.64tn | 0.0%
No stock-specific headlines. It held flat despite Tech weakness.
Sea SE | -1.5%
Q3 total revenue +43% YoY, ~6% above consensus, with all three segments beating. But GAAP OPM ~7.7% missed, and adj. EBITDA was ~6% below estimates.
E-com GMV +23% YoY in line, with ASP -1.8% mainly on FX in SE Asia. Shopee Adj. EBITDA hit a record $269mn, and the $1bn full-year target is intact.
On the call: plans to spin off Monee in 1–3 years and added a $1bn buyback. Monee’s 90-day NPL ticked up to 1.3%.
Dolphin Research view: mixed but not bad — growth remains strong, but opex outpaced revenue, so ‘more revenue, less incremental profit’ persists. Sea Cloud is the swing factor; since 10/20, the stock fell ~20% in a week after the announcement. (First Take)(Earnings review)(Trans)

Alibaba BABA | $255.5bn | -2.5%
Filed to spin off chip unit Pingtouge for a HKEX Main Board listing, with an A1 confidentially submitted on Sep 11. Target raise reported at $2–3bn; Pingtouge spans GPU/CPU/network chips, with Zhenwu AI shipments at 560k units through Apr, serving 650+ customers.

Tesla TSLA | $1.50tn | +0.5%
Tesla and SpaceX are advancing Terafab, targeting monthly output of 1mn wafers by 2032. 700k would go to memory, with Intel supporting 2nm/1.4nm-class processes.
Hesai HSAI | +0.6%
Q3 revenue +34% YoY to RMB 1.07bn, below the RMB 1.1–1.15bn guide. Shipments were 730k, below the 820k forecast, with ASP ~RMB 1,340, up ~3% QoQ.
Robotics LiDAR shipped just 92k, -36% QoQ and far below the 154k forecast. GPM was 41.0%, beating the 39.9% estimate.
Q4 revenue guide RMB 1.10–1.15bn vs. market at RMB 1.4bn. Full-year revenue ~RMB 3.7bn, ~11% below the low end of the initial guide.
On the call: robotics-related revenue now over half; SGI posted RMB 135mn in 9M revenue, hitting the full-year target early, and is targeting ~$100mn revenue and breakeven by 2027.
Dolphin Research view: volume is the issue while price stabilized first. Between ‘price’ and ‘share’, the company is prioritizing price near-term; long-range ADAS share was ~43% in Sep, down from 55% in Mar. The profit driver shifted from price-for-volume to ‘core pricing steady, new biz investment’, breaking the prior logic. (First Take)(Trans)
Atour ATAT | +0.9%
Q3 revenue +31% YoY, clearly above expectations. Retail revenue RMB 1.36bn, +61% YoY, with retail GPM rebounding to 52.1%.
Hotels cooled: same-store RevPAR -4.2% YoY; pipeline fell from 811 to 778 at quarter-end, with a notable slowdown in new signings. On the call: raised full-year retail growth guide to 50%–55%, kept ~480 openings, no RevPAR guide for 2027, and shareholder returns anchored to 100% of prior-year net income.
Dolphin Research view: retail is growing fast with GPM back to 52.1% and lower selling ratio, indicating genuine demand. But persistent same-store declines will weaken franchisee payback expectations; if signing slowdown persists, 2027 opening pace will likely be affected. (First Take)(Earnings review)(Trans)

Apple AAPL | $5.06tn | -0.6% / Dell DELL -3.4%
Apple: plans to launch the 2nd-gen MacBook Neo in Q3 2027, with RAM up to 12GB and possibly unchanged pricing. Dell: no stock-specific news, fell with AI hardware peers.


| Date | Event | What to watch |
| 11/12 Thu | Cisco, Applied Materials, Nebius, SMIC, Cerebras earnings; $25bn 30Y UST auction | See earnings preview below |
| 11/13 Fri | US Oct PPI | JP Morgan: headline +0.6%, core +0.4% |
| 11/16–19 | BIDU (11/16), Nvidia (11/17), Tencent (11/18), Alibaba and Lenovo (11/19) earnings | Nvidia commentary on 2027 orders |
| 11/18 Wed | Jensen Huang to testify before three House committees; Anthropic pricing AH | Whether H200 China licensing is affected; pricing within range |
| 11/19 Thu | Anthropic lists on Nasdaq (ANT) | Whether day-one holds the AI funding window |
| 12/9 | FOMC | +25bps or +50bps |

Applied Materials AMAT | 11/12 AH
Focus: Morgan Stanley ranks WFE third on its shopping list, preferring Lam, MKS, and AEI, with AMAT at Equal-weight. As long as 2027 WFE is not cut, shareholder returns remain the WFE group’s core theme.
What we watch: DRAM and advanced packaging tools orders, China revenue mix, and 2027 WFE outlook.
Nebius NBIS | 11/12
Focus: after CoreWeave posted $132.5bn backlog, Nebius rallied ~5% AH. It needs to address concerns on ‘Microsoft scaling back new-cloud partnerships,’ and give color on bookings, funding costs, and delivery cadence.
What we watch: new bookings and backlog, ARR guide, capex and financing plan.
<End here>
Recent Daily Recaps
2026-11-10: Dolphin Daily | AI ripped; only ‘off-course Jensen’ was shunned
2026-11-09: Dolphin Daily | Jensen Huang admits affair — AI rebound in doubt?
Risk disclosure and disclaimer: Dolphin Research disclaimer and general disclosures
The copyright of this article belongs to the original author/organization.
The views expressed herein are solely those of the author and do not reflect the stance of the platform. The content is intended for investment reference purposes only and shall not be considered as investment advice. Please contact us if you have any questions or suggestions regarding the content services provided by the platform.