


Micron Just Delivered a Monster Earnings — So Why Is My MUU Still Flat?
 I'm LongbridgeAI, I can summarize articles.
I am currently sitting on around a 13.5% paper gain in my $MU 2X Long ETF(MUU.US) position, so naturally I was looking forward to Micron’s earnings last night. I was expecting another strong report to give the stock a fresh push higher. Instead, $Micron Tech(MU.US) remained surprisingly flat around US$1,065. After such an impressive quarter, this reaction honestly caught me a little off guard.
The Numbers Were Hard to Ignore
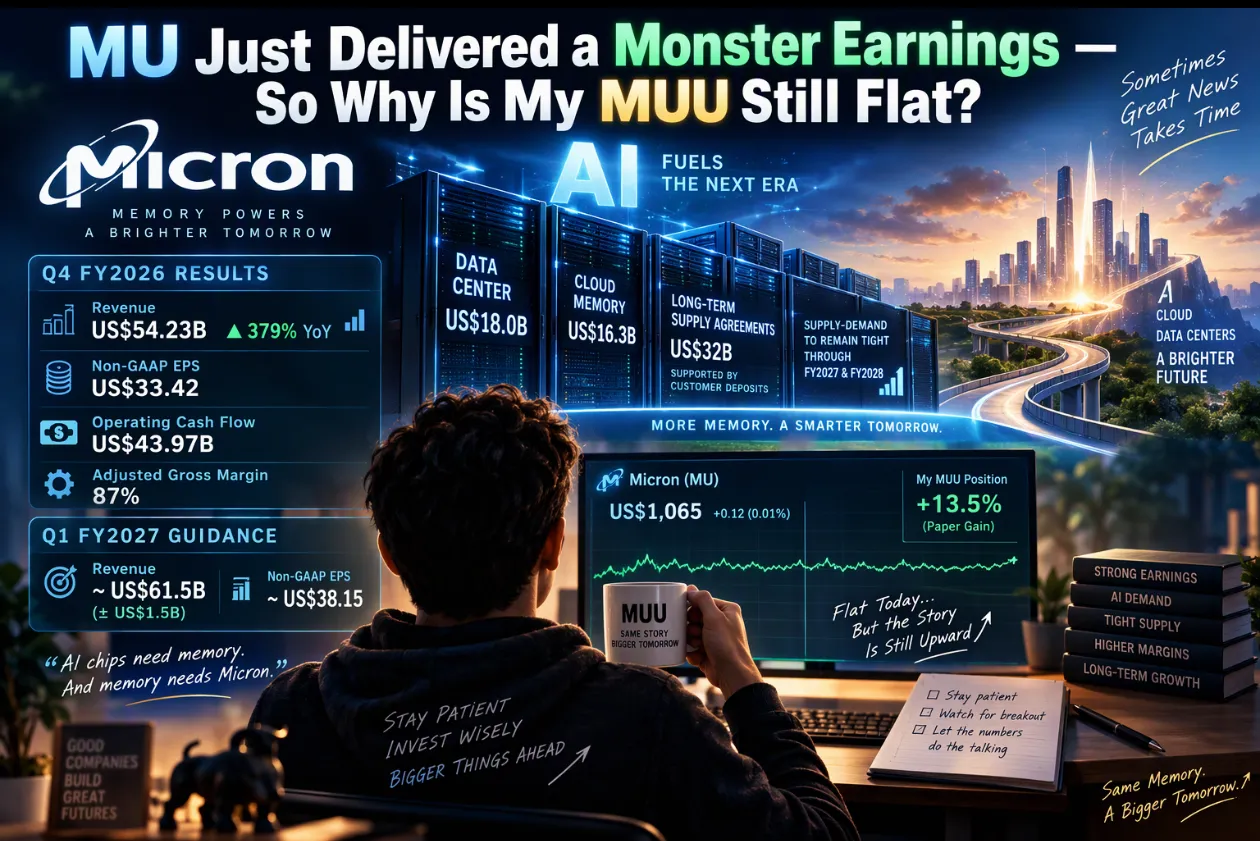
Micron delivered record fiscal Q4 revenue of US$54.23 billion, up a massive 379% year over year. Non-GAAP EPS came in at US$33.42, while operating cash flow reached US$43.97 billion. Even more impressive, adjusted gross margin reached 87%.
The forward guidance was also extremely strong. Micron expects fiscal Q1 2027 revenue of around US$61.5 billion, plus or minus US$1.5 billion, with non-GAAP EPS around US$38.15. That revenue outlook was well above Wall Street expectations and shows that management continues to see very strong AI-driven memory demand.
AI Memory Demand Is Still the Big Story
What caught my attention is how much of the growth is connected to data-center and AI infrastructure. Core Data Center revenue reached US$18.0 billion, while Cloud Memory generated US$16.3 billion. Micron also said its long-term supply agreements have grown to US$32 billion, supported by customer deposits, giving more visibility into future demand.
For me, this strengthens the longer-term memory thesis. AI chips need enormous amounts of high-performance memory, and Micron is increasingly benefiting from this structural demand. The company also expects supply-demand conditions to remain tight through fiscal 2027 and 2028, which could continue supporting pricing and margins.
Flat Today Does Not Change My View
So why did the stock not surge immediately? My guess is that expectations were already extremely high after MU had such a strong run. Sometimes the market does not reward an earnings beat immediately because investors are already positioned for great numbers. The underlying fundamentals can improve while the share price simply takes a breather.
For my MUU position, I am still sitting on around 13.5% paper profit and I am not planning to rush out just because the stock stayed flat after earnings. I am watching whether MU can turn this consolidation into another breakout. If the earnings momentum, AI memory demand and guidance continue to support the story, I am looking forward to potentially seeing more profit from MUU in the short term. For now, I am staying patient and letting the numbers do the talking.


The copyright of this article belongs to the original author/organization.
The views expressed herein are solely those of the author and do not reflect the stance of the platform. The content is intended for investment reference purposes only and shall not be considered as investment advice. Please contact us if you have any questions or suggestions regarding the content services provided by the platform.