


Nebius: From +20% to -17% in Days — Why I Am Trimming, Not Giving Up
 I'm LongbridgeAI, I can summarize articles.
$Nebius(NBIS.US)
Neocloud debt concerns are shaking the AI infrastructure sector. I am protecting my capital while keeping faith in the long-term opportunity.
From Paper Profits to a Sharp Reversal
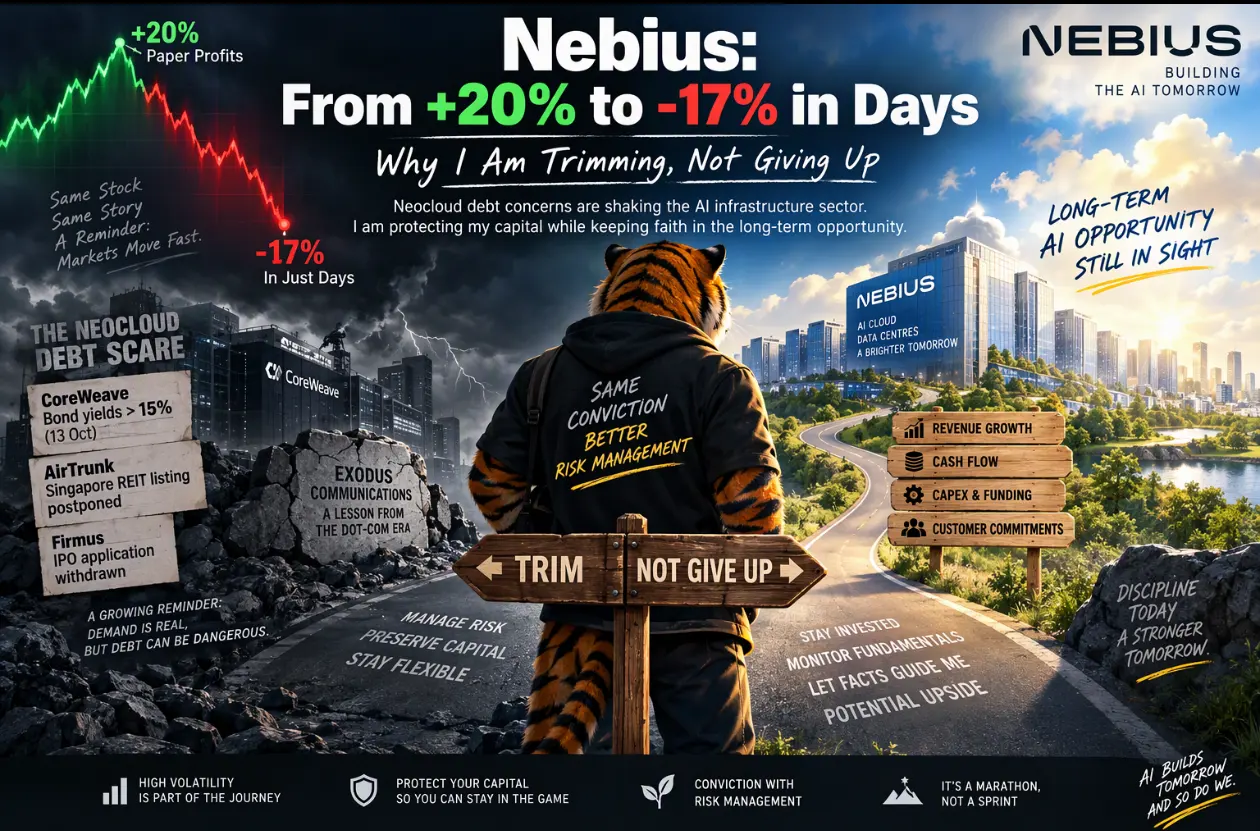
Sometimes, the market reminds us how quickly paper profits can disappear. $Nebius(NBIS.US) was previously sitting at around 20% unrealised gains in my portfolio, but within just a few days, the position swung to a 17% loss.
Rather than blindly holding and hoping for a recovery, I decided to trim part of my position to protect my capital. However, I am not giving up on Nebius completely because I still believe in its long-term AI infrastructure potential.
The Neocloud Debt Scare
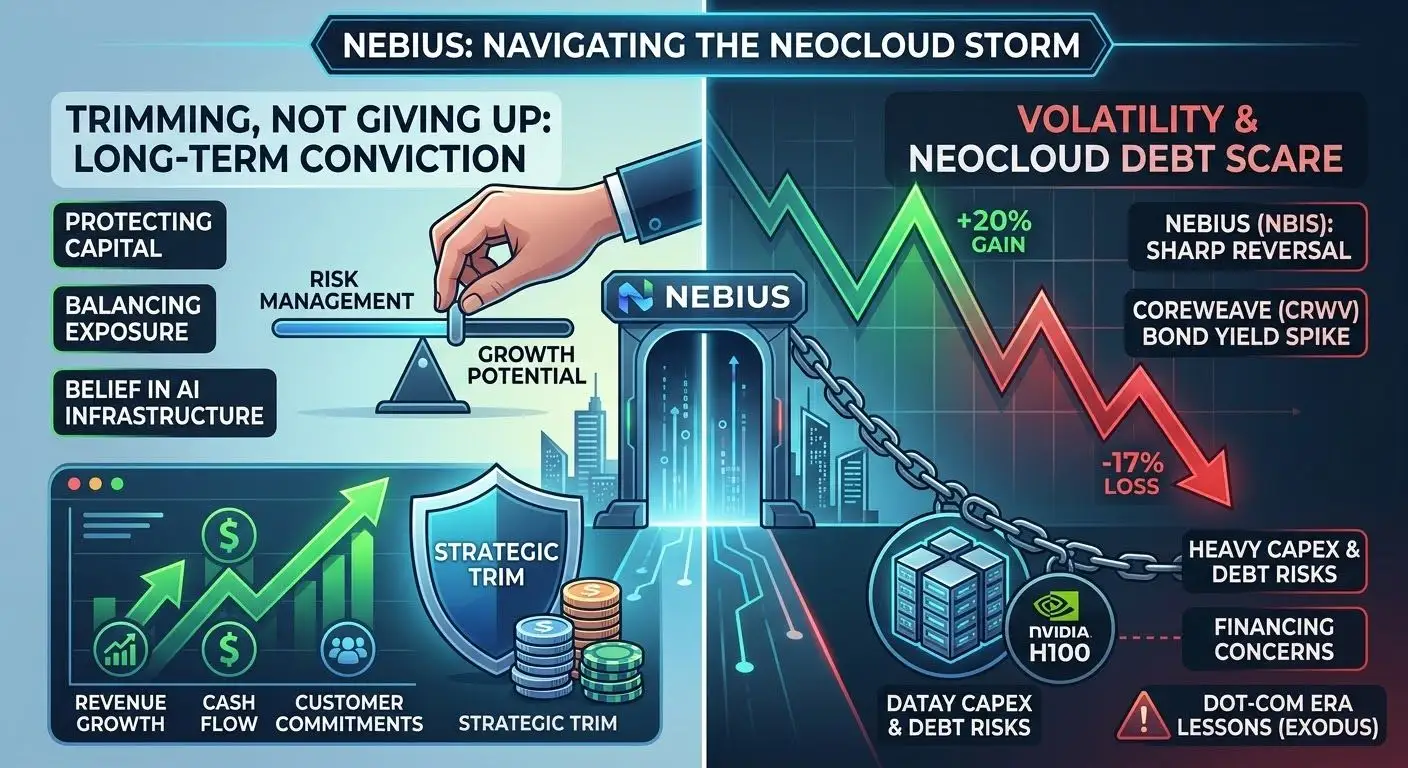
One factor weighing on sentiment is growing concern over the financing model used by neocloud providers. Companies such as $Coreweave(CRWV.US) invest heavily in Nvidia GPUs and data centres, then rent computing capacity to AI developers and enterprise customers.
This model can generate rapid growth when demand is strong, but it also requires enormous capital expenditure and often relies on debt and external financing. When borrowing costs rise or financing becomes harder to obtain, these companies face greater pressure to turn strong demand into sustainable cash flow.
Recent reports highlighted CoreWeave bond yields surging above 15% on 13 October, alongside substantial interest expenses and refinancing needs. Although the company has a large backlog of customer commitments, these do not automatically guarantee sufficient cash flow to service its debt.
The comparison with Exodus Communications during the dot-com era is a useful warning: even when demand for a revolutionary technology is genuine, excessive debt and aggressive expansion can create serious risks for shareholders.
Why This Matters for Nebius
Nebius is not CoreWeave, and I would not automatically apply CoreWeave's financial risks to Nebius. However, both operate in the broader AI infrastructure ecosystem, so concerns about one company can trigger a reassessment of the entire sector.
The reported postponement of AirTrunk's planned Singapore REIT listing and the withdrawal of Firmus's IPO application also suggest that financing conditions for data-centre businesses are becoming more challenging.
If neocloud providers struggle to raise capital, they may slow expansion or reduce spending. This could affect GPU orders, data-centre investment and sentiment across AI-related stocks.
For Nebius, I believe the key questions are whether its AI cloud business can continue growing, whether customer commitments translate into actual cash flow, and whether its expansion can be funded without excessive financial pressure.
I remain bullish on the AI infrastructure opportunity, but I do not want to assume that strong demand alone guarantees attractive shareholder returns.
Why I Trimmed Instead of Selling Everything
Moving from a 20% gain to a 17% loss in just days was a clear reminder of the volatility involved in high-growth stocks.
I decided to reduce my exposure to a more comfortable level while retaining some shares for potential long-term upside. This allows me to participate if Nebius executes well, while preserving capital and flexibility if the selloff continues.
My focus now is on monitoring its revenue growth, cash flow, capital expenditure, funding requirements and customer commitments. I would rather reassess based on fundamentals than blindly average down simply because the share price has fallen.
My Takeaway: Conviction With Risk Management
I can remain bullish on Nebius while recognising that financing risks across the neocloud sector deserve attention. AI demand may continue growing, but not every infrastructure provider will benefit equally, and valuations can remain under pressure when funding becomes more expensive.
For now, I am trimming to protect my capital, keeping some exposure to the upside, and watching how the situation develops.
The goal is not to predict every market swing correctly. It is to manage risk well enough to stay invested in opportunities I believe in.
How are you approaching NBIS after this sharp pullback? Are you holding, adding on weakness, or trimming while waiting for greater clarity on the neocloud financing risks?


The copyright of this article belongs to the original author/organization.
The views expressed herein are solely those of the author and do not reflect the stance of the platform. The content is intended for investment reference purposes only and shall not be considered as investment advice. Please contact us if you have any questions or suggestions regarding the content services provided by the platform.