In 2026, the AI hardware hot spot has shifted from compute to memory. As AI trades in U.S. equities start to wobble, Micron’s prints have turned into the new bellwether. $Micron Tech(MU.US) reported after-market on Jun 24 (FQ3 FY26 for the quarter ended end-May), and it delivered, taking up the mantle as the AI infra standard-bearer.
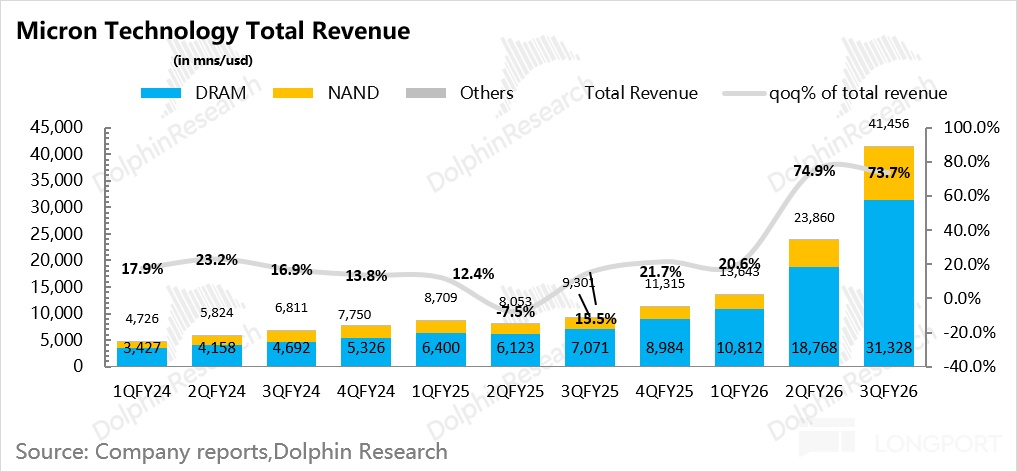
Results speak for themselves: broad-based strength. Key takeaways: 1) Headline results: revenue of $41.5bn, up 74% QoQ, marking a second consecutive quarter with 70%+ QoQ growth...
Micron (MU) posted FQ2 (FY26) results (quarter ended Jan 2026) after the U.S. close in the early hours of Mar 19 Beijing time. Key takeaways: (1) overall results.
Revenue was $23.86bn (+75% QoQ), beating raised buy-side est. of $19.9bn. Growth was driven by both DRAM and NAND, each up 70%+ QoQ.
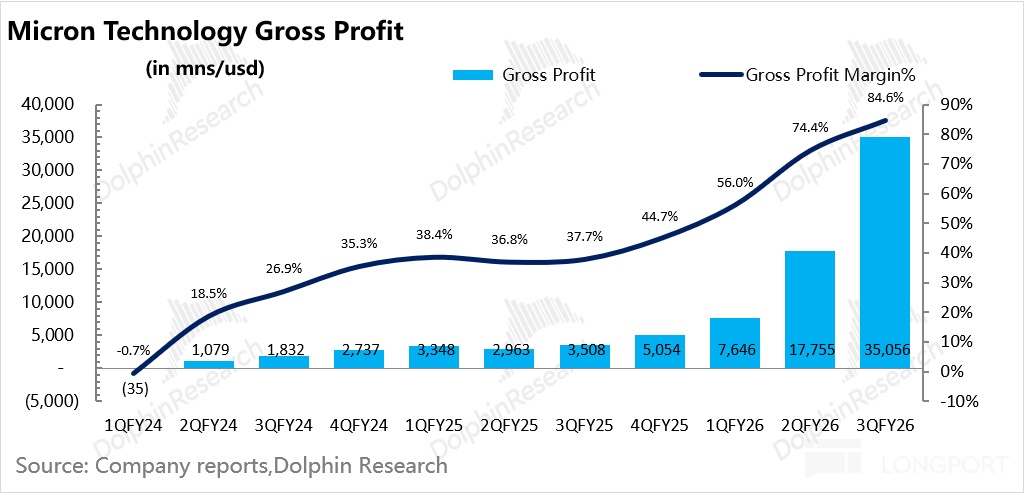
GPM reached 74.4%, above the raised buy-side est. of 69%. Supported by a sharp rise in memory pricing...
Jensen Huang's keynote at CES 2026 reignited market enthusiasm for memory. In the Rubin architecture, higher DDR and NAND content vs. Blackwell is fueling another rally in memory stocks.
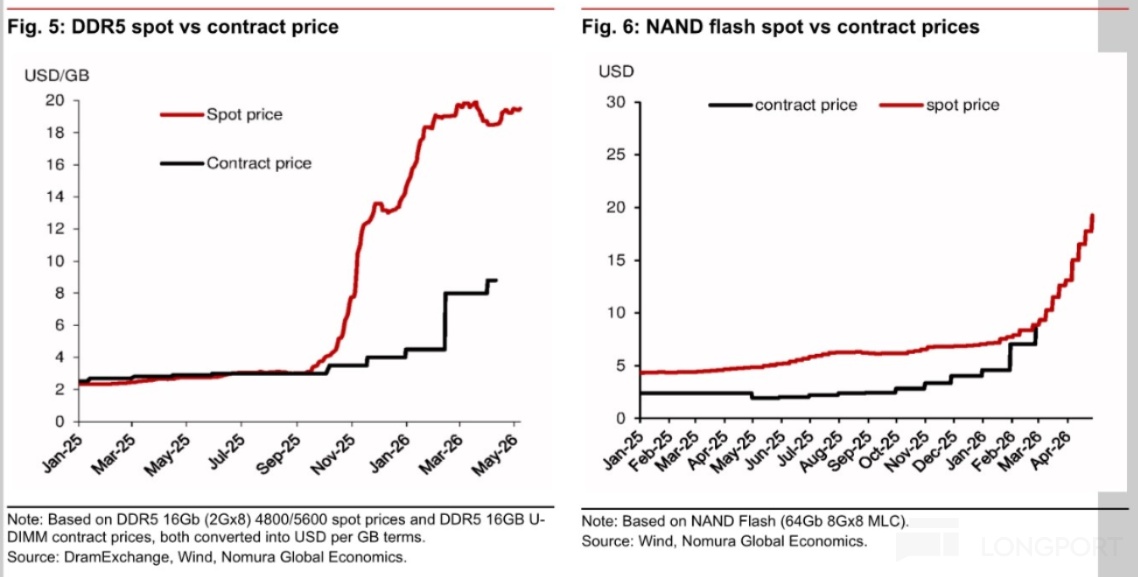
Investor focus has broadened beyond HBM to more traditional categories such as DDR and NAND. Shifting supply-demand dynamics are driving a broad-based rise in memory pricing. Our previous article mapped the roles of each memory tier in AI servers and reviewed the HBM market...
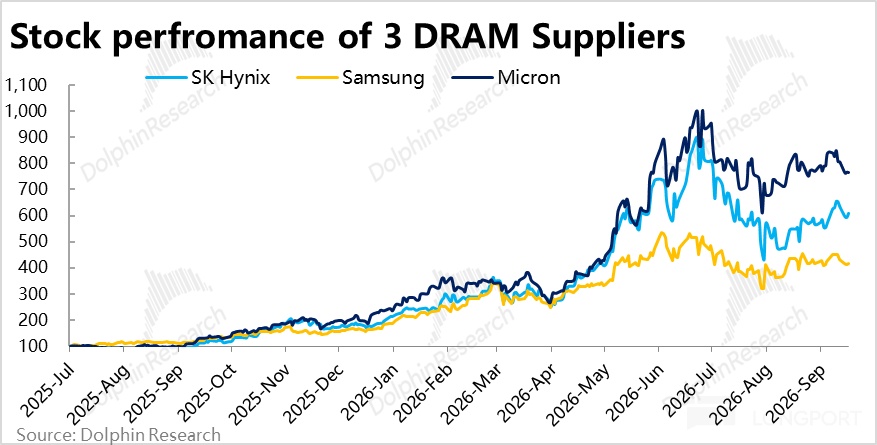
With AI demand fueling the current memory 'super cycle', the sector rallied again last night. Gainers included $Sandisk(SNDK.US) +27% and $Micron Tech(MU.US) +10%.
The surge was largely catalyzed by Jensen Huang's CES 2026 keynote, which poured fuel on an already hot memory market. Source: Longport.appFirst, a quick recap of Jensen Huang's key messages at CES 2026. More below.
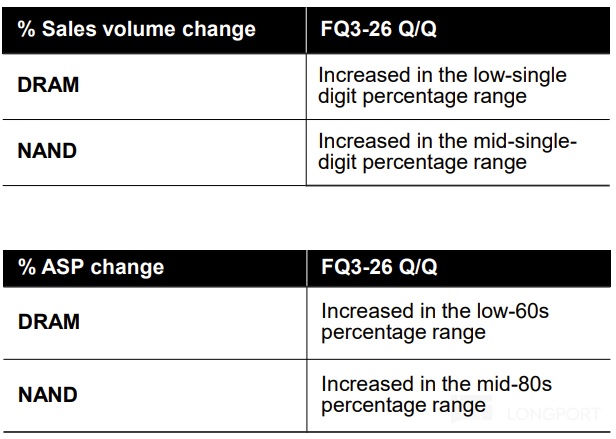
Fueled by AI demand, the memory upcycle that started in HBM has extended into mainstream DRAM/NAND. Using MU as an example, sustained ASP hikes have pushed GPM to elevated levels.
Management guided next-quarter GPM to 66–68%, a record high. That implies this memory cycle is stronger than prior ones.Price gains reflect the underlying supply-demand balance. This bout of undersupply is mainly driven by AI servers and related workloads...
Following $Micron Tech(MU.US)'s post-earnings main call and breakout sessions, Dolphin Research highlights the core takeaways. Details as follows:
1) Memory demand: the 2025 DRAM bit demand growth outlook is raised to around 20% (prev 15%+), and NAND to 15%+ (prev 10%–15%). For 2026, industry shipments for DRAM and NAND are expected to grow about 20% vs 2025.2) HBM market: the total addressable market (TAM) is expected to keep expanding at roughly 40% CAGR. Continued rapid expansion is anticipated...
Below is Dolphin Research's FY2026 Q earnings call Trans for Micron. For the earnings analysis, see 'Micron MU: AI is energizing memory; is a new cycle starting?'.
I. $Micron Tech(MU.US) key financials recap. Revenue: Q1 revenue reached $13.6bn (+21% QoQ, +57% YoY), a company record.GPM: blended GPM was 56.8%, up 1,100bps QoQ. Gains were driven by higher pricing, cost control, and a better product mix...


 +16