D
MRVL to buy LITE: Strategy looks sound, but the market votes with its feet first.
Worth it or not hinges on how long the InP shortage lasts. Duration is the key driver.

Worth it or not hinges on how long the InP shortage lasts. Duration is the key driver.
Below is the meeting Trans of MRVL 2026 Investor Day (covering FY27), compiled by Dolphin Research. For in-depth analysis, cf. 'Marvell: Long-term guidance surges — confidence or just painting a rosy picture?'
I. Core highlights. 1) Shareholder returns & capital allocation: From FY21–FY26, the co. invested approx. $8 bn in organic R&D and about $11 bn in M&A.
It also returned about $4 bn to shareholders via dividends and buybacks. Looking ahead, with structurally stronger cash flow...
Marvell hosted its Investor Day in New York last night (ET Oct 6, 2026), led by Chairman & CEO Matt Murphy and the executive team. This marked the first comprehensive update to its long-term outlook since the company postponed its 2025 Investor Day, and the first time it set targets for FY2031. Earlier, $Marvell Tech(MRVL.US) signed a new collaboration with Alphabet on custom ASICs, offering warrants to win orders; cf. 'Marvell: teaming with Alphabet with sweeteners — can it pry share from Broadcom?'
MRVL released its FY2027 Q2 results after hours on Aug 28 Beijing time (quarter ended Jul 2026).
It raised its FY2027 revenue outlook to $12bn (prior $11.5bn), up 45% YoY.Guidance for FY2028 was lifted to $18bn (prior $16.5bn), up 50% YoY, with data center rev. expected to grow 60%+ (vs. NVDA's next-year outlook of 70%+)...FY27/FY28 revenue guide raised to approx. $12bn and $18bn, with FY28 growth re-accelerating to 50%.
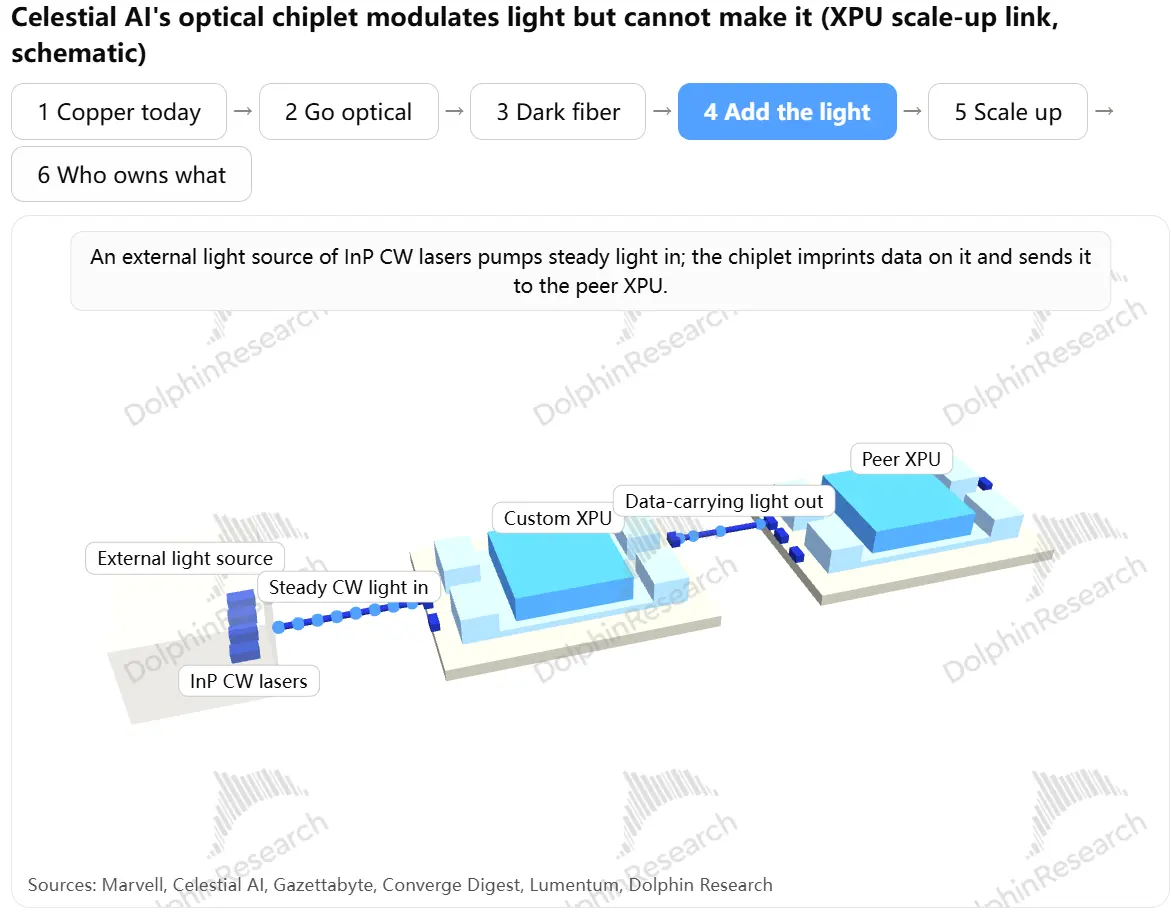
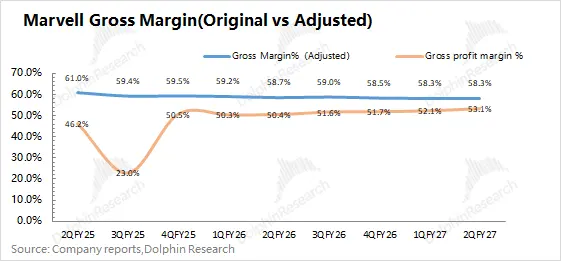
However, the custom ramp is pressing Q3 non-GAAP GPM to 57.5–58.5% and is likely to persist into FY28. Mgmt noted the $1.5bn uplift is mainly from optical interconnect scale-up rather than custom chips.Marvell announced it issued warrants to Alphabet for the first time, sending its shares up 10%+.
Meanwhile, AVGO sold off, reflecting fears that $Marvell Tech(MRVL.US) could win Alphabet's TPU orders.Here, Dolphin Research walks through both companies' deal structures and the implications.
We summarize the key terms and potential impact below.1) Marvell–Alphabet agreement
First, the specific arrangement Marvell signed with Alphabet: the commercial agreement was executed on Jul 29, 2026...Below is Dolphin Research's Trans of Marvell's FY27 Q1 (FQ1 2027; period ended May 2, 2026) earnings call. For our earnings analysis, see 'Marvell: AI mega-interconnects bring another opportunity — can it support the Little Broadcom dream?'.
I. $Marvell Tech(MRVL.US) Core highlights recap. 1) Shareholder returns: repurchased $200mn of stock under the ongoing capital return program, and returned $54mn to shareholders via cash dividends...MRVL released its FY2027 Q1 results after-hours on May 28 (Beijing time). The quarter ended Apr 2026.
1. Revenue: $2.42bn (+9% QoQ), in line with consensus ($2.41bn). The ~$200mn sequential uplift was almost entirely driven by Data Center.2. GPM: 52.1% this quarter, up 40bps QoQ. Margin is affected by amortization of acquired intangibles and other items...Dolphin Research's transcript summary of Marvell's FY2026 Q4 earnings call.
For the analysis, cf. 'Marvell: ASIC card orders fell short; connectivity drives the AI comeback!'. $Marvell Tech(MRVL.US) key takeaways: (1) Outlook — FY2027 total revenue guide raised to $11bn (prior $10bn), with data center revenue +40% YoY and comms & other +10% YoY. FQ4 FY2027 revenue is expected to surpass $3bn...MRVL reported FY2026 Q4 results after hours on Mar 6 (Beijing time), for the quarter ended Jan 2026.
1) Revenue: $2.22bn, +7% QoQ, in line with consensus ($2.21bn).
The $150mn QoQ uplift was primarily driven by data center.2) GPM: 51.7%, +10bps QoQ.
Margins are affected by amortization of acquired assets and other factors...