Oracle

D
Dolphin Research

ORCL: AI boosts the optics, but what backs the bottom line?

On Sep. 11 after the U.S. market close, leading cloud vendor Oracle ($Oracle(ORCL.US)) released FY27 Q1 results for the period ended Aug. Overall, it was a mixed print, with strengths very strong while weak spots stayed weak.

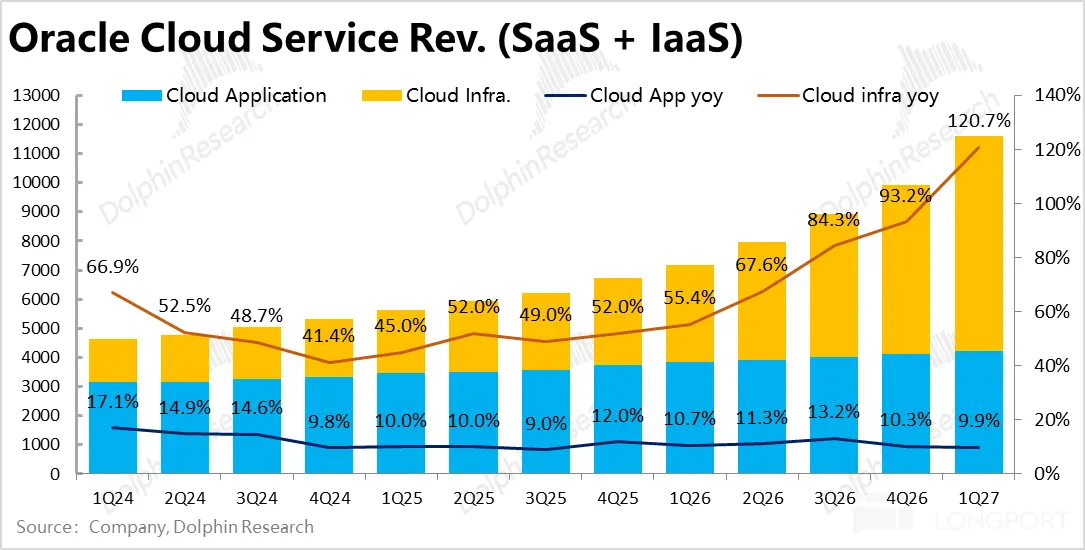
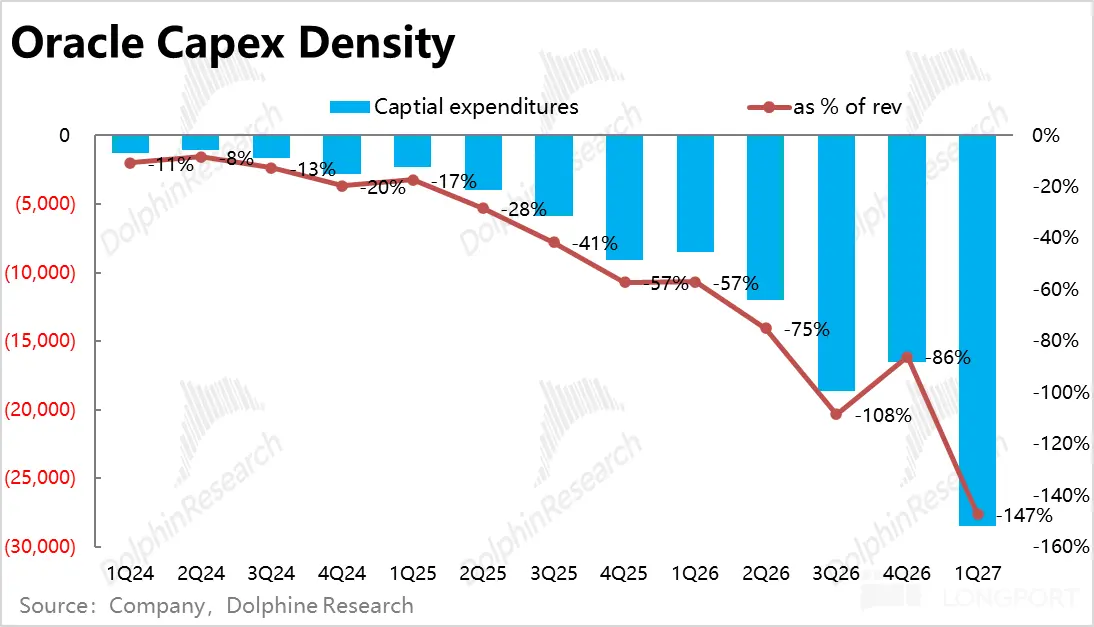
OCI drew the most attention with robust growth, revenue continuing to accelerate sharply, and Capex ramping significantly. Legacy businesses remained sluggish, GPM was under notable pressure, and those issues showed little improvement.

Specifically:

1) Core — OCI beat and accelerated. As the most critical segment, OCI revenue reached nearly 7.4 bn this quarter...

DRACLE
Oracle Cloud Service Rev. (SaaS +laaS) 13000 Cloud Application Cloud Infra. Clou
Oracle Capex xD Density Captial expenditures 0 c as % of rev xch C 0% -8% eo -11
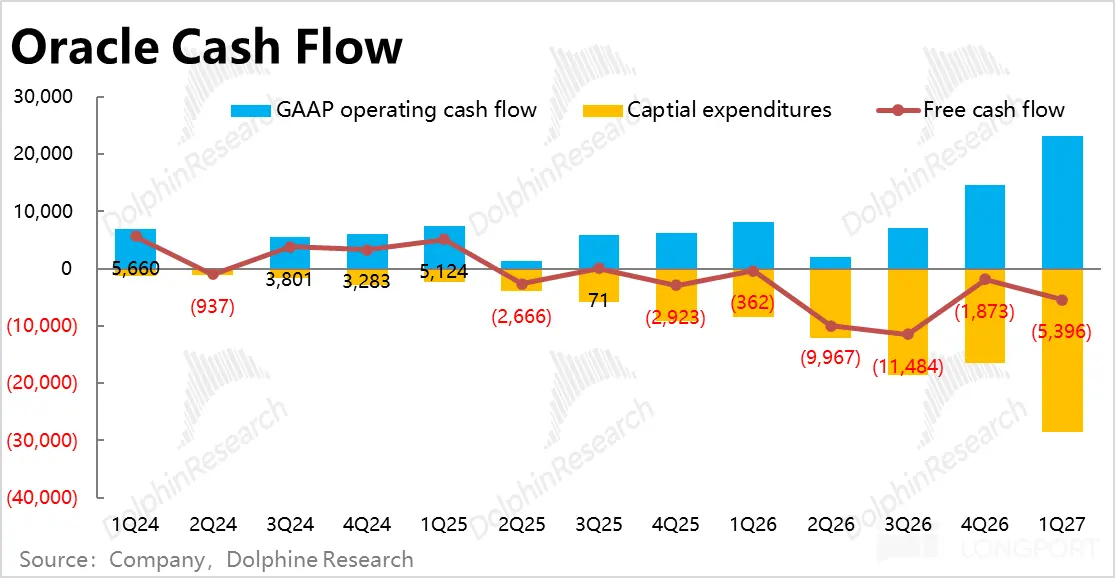
Oracle Cash Flow 30,000 20,000 10,000 DolphinResear DolphinResear DolphinReseai +10
D
Dolphin Research

ORCL (Trans): OCI +121%, cash flow still -$5bn

OCI revenue was $7.4bn (+121% YoY). Alongside RPO rising another $26bn QoQ, this drove full-year revenue guidance up to at least $90bn.

However, Q1 CapEx of $28bn kept FCF at -$5bn. GPM declined as expected, and management offered no timeline for a return to positive FCF.

Meanwhile, nearly all new contracts skew to prepayments. They also require customers to supply their own hardware.

ORACLE
D
Dolphin Research

ORCL plunge? AI infra can't offset a core flaw — high interest costs, heavy debt + a sluggish software biz

Among the 'New Cloud' cohort, $Oracle(ORCL.US) is one of the most watched and debated. On Jun 11 after hours, it reported FY26 Q4 results for the period ended May.

Overall, the print was mixed. OCI growth accelerated, while the broader legacy software portfolio slowed.

GPM improved QoQ off the trough, but still missed estimates by a wide margin. Next-quarter guidance was above expectations.

However, the FY27 full-year outlook was relatively conservative. Net-net, the quarter felt muted...

DRACLE
Oracle Financial Earnings Wrap
Oracle's Business Segments and Revenue Classification Cloud Software Hardware Se
Oracle Cloud Service Rev. (SaaS +laaS) 11000 Cloud Application Cloud Infra. Clou+12
D
Dolphin Research

ORCL: Big Bet on AI Compute — Are the Odds Good Enough?

Per Dolphin Research's prior note on Oracle, our core takeaway is that Oracle is essentially a scaled-up CoreWeave. The bull case hinges on explosive AI compute demand that could lift its compute-rental revenue by 10x or more.

The key risk is the mismatch between uncertain AI demand and fixed upfront capex and leverage, which could lead to sizable credit losses if the AI cycle unwinds. Overall, visibility is limited...

DRACLE
Oracle "Legacy" Biz Rev Projection 40,000 Services Hardware Software (License +
Exhibit 31 - Oracle Market Share - Application Software ($, in M) 2023 2024 y/yg
OCA Rev. Projection by Sub-segments Fusion Suite Netsuite ERP 35,000 30,000 25,0+20
D
Dolphin Research

ORCL (Trans): AI biz. GPM at 32% this quarter

Below is Dolphin Research's FY26Q3 earnings call Trans for $Oracle(ORCL.US). For analysis of the print, see 'All-in to survive — did ORCL's AI bet win?'.

I. Core info recap

1) Financing plan: In Feb, the company announced a plan to raise up to $50bn via debt and equity, and committed not to issue additional bonds in calendar 2026.

Within days of the announcement, it raised $30bn through a mix of IG bonds and mandatory convertible preferreds (MCPS), with the book heavily oversubscribed. The ATM equity component has not yet launched...

DRACLE
Oracle Financial Earnings Wrap 3Q24 4Q24 1Q25 2Q25 3Q25 4Q25 1Q26 2Q26 3Q26 3Q26
D
Dolphin Research

Bet-the-company for survival: Did ORCL's AI bet pay off?---

As the most debated of the Big Four cloud players, $Oracle(ORCL.US) reported 3QFY26 results (through end-Feb) after hours. Overall, the print was mixed.

On the plus side, Oracle Cloud Infrastructure (OCI) — anchored by databases and compute leasing — maintained strong growth and even accelerated. On the flip side, gross margin pressure was worse than expected, while capex and borrowings climbed faster than anticipated.

Net-net, the quarter screens neutral with positives offset by negatives. The real after-hours catalyst was management raising its FY27 full-year guidance...

DRACLE
Oracle Financial Earnings Wrap 3Q24 4Q24 1Q25 2Q25 3Q25 4Q25 1Q26 2Q26 3Q26 3Q26
Oracle's Business Segments and Revenue Classification Cloud Software Hardware Se
Oracle Cloud Service Rev. (SaaS +laaS) 10000 Cloud Application Cloud Infra. Clou+14
D
Dolphin Research

ORCL: Picking up scraps, leaning on deep‑pocketed patrons—fighting to survive?

Previously, Dolphin Research profiled CoreWeave, an emerging AI-era 'new cloud' leader, as an entry point into the U.S. IaaS space. This time we turn to a more pivotal player — $Oracle(ORCL.US), one of OpenAI's primary partners.

As the first note in our coverage, Dolphin Research will focus on two questions. 1) A high-level review of the company's history, tracing how a 50+ year incumbent evolved into a new force in cloud services; 2) A clear breakdown of its business and revenue mix...

ORACLE Cloud
A series of acqusitions by Oracle during 2005~2010
Oracle's Business Segments and Revenue Classification Cloud Software Hardware Se
Other seg. rev almost stable from FY18~26 Cloud will nearly reach 50% of total r+11