D
 +5
Tencent, BABA, ByteDance: Who will call the shots in AI productivity?
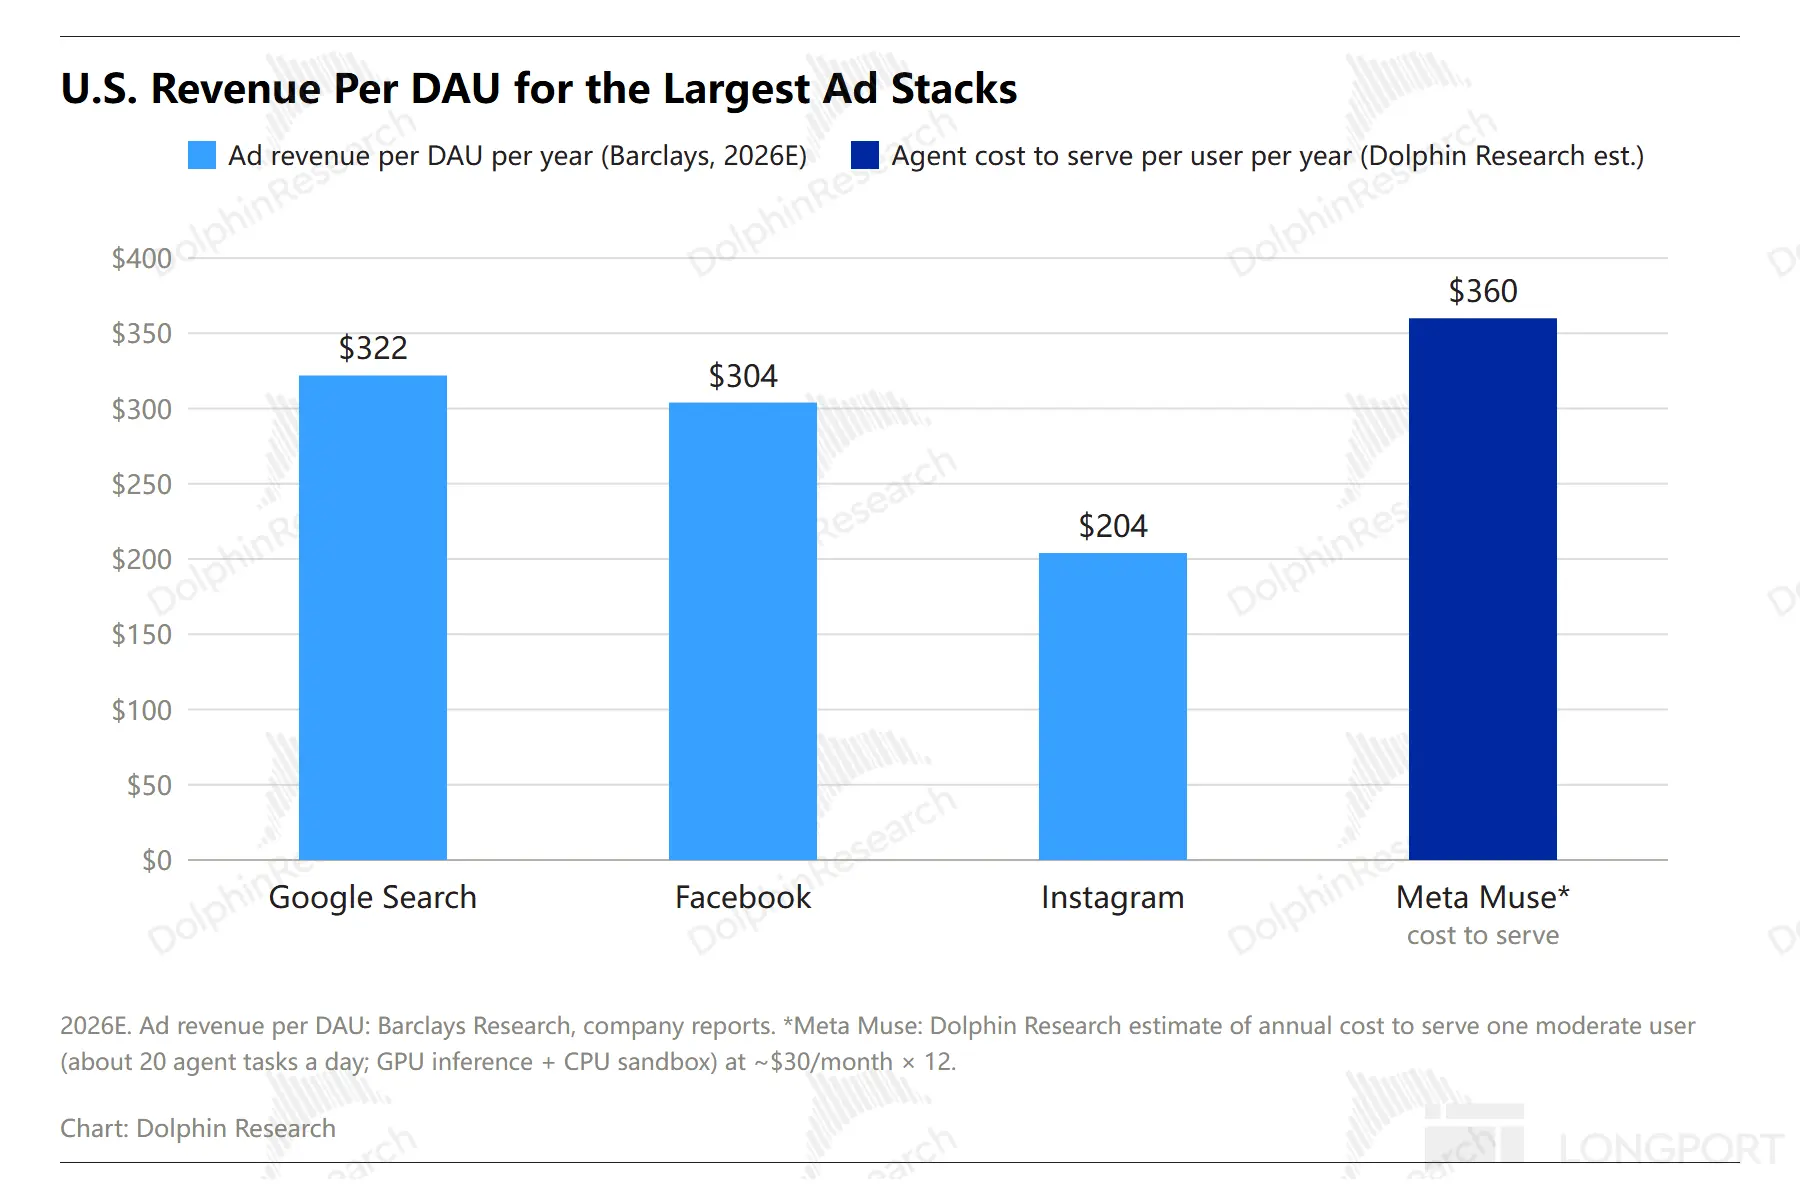
Chat boxes don’t monetize well. Agents are taking the baton.
+5
Chat boxes don’t monetize well. Agents are taking the baton.
+5Agent technology is not a moat. The real barrier is user behavior data, which is hard to replicate.
 +3
$TENCENT(00700.HK) Q2 print was broadly lukewarm. Line items were largely around consensus, and the picture aligns with market concerns: AI investment is already weighing on near-term profit and cash flow.
To offset bottom-line pressure, as a long-standing internet leader Tencent still has room to pull top-line monetization levers, most visibly in ads. That said, profit pressure in H2 is likely to remain elevated.Specifically: (1) capex rose sharply as expected, and the FY outlook will likely be revised up. Management had already signaled this last quarter...Q2 revenue was RMB 204.8bn (+11% YoY). Non-IFRS OP ex new AI products reached RMB 86.1bn (+19% YoY), but the drag from new AI widened from ~RMB 8.8bn in Q1 to RMB 10.5bn.
Operating capex rose 190% YoY to RMB 51.8bn, turning FCF to -RMB 13.8bn. Management has prioritized compute for self-developed model training, WorkBuddy inference, and cloud leasing. 'Hunyuan 4' will be released within the year.Below is Dolphin Research's Trans of $TENCENT(00700.HK) FY26 Q1 earnings call. For our post-results take, see 'Tencent: No Longer Resting on Past Laurels; AI Is the Way Forward'.
I. Core highlights from the results. Key points are summarized below.1) Shareholder returns: Q1 buybacks totaled approx. RMB 7.9bn. Management believes the stock is undervalued, is accelerating monetization of the investment portfolio to fund continued buybacks through the year, and sees now as a particularly attractive window for repurchases.
2) Outlook: CapEx is expected to increase materially vs. last year. Guidance points to a sharp step-up this year...
$TENCENT(00700.HK) Q1 results are out, and the read is mixed with plenty to unpack. There are several points that warrant a closer look.
On the market's key question of AI spend vs. returns, Dolphin Research offers a quick take.1) AI spend is clearly rising. Q1 capex recognized was RMB 31.9bn (+16% YoY), which looks like a modest growth rate.But cash outlay reached RMB 37.0bn, indicating another round of prepayments for capacity yet to be delivered. Compute remains scarce, especially at the high end.Since Tencent began iterating its foundation model in earnest, securing high-end compute has required heavy upfront orders. Looking back over the past year...Below is Dolphin Research's Trans of Tencent's FY25 Q4 and full-year earnings call. For our earnings take, please see '腾讯:到了去登味,AI 上火候的时候了'.
Key highlights: 1) Shareholder returns: proposed FY DPS of HKD 5.3 (+18% YoY). For FY25, planned buybacks of ~153.4 mn shares (HKD 80 bn total); with AI opportunities in focus, 2026 repurchases may come in below 2025, while the dividend payout will be increased...After the Hong Kong close on Mar 18 (Beijing time), $TENCENT(00700.HK) released its 2025 Q3 results. Overall, the print was largely in line with no major surprises, though some line items came in slightly off expectations.
Against the backdrop of the current AI transformation window, management’s guidance on this year’s investment and growth matters more than the reported quarter. This will be more critical for mid-term valuation.
Specifically: 1) Games delivered and are expected to remain the core growth driver this year. The current product cycle is strong, with new titles performing and evergreen franchises supporting durability. Q4 revenue rose 21%...
Over the weekend, the Yuanbao team rolled out a major update, and in doing so also unveiled the AI roadmap for $TENCENT(00700.HK). Dolphin Research jumped in with friends to try it right away.
We had some expectations, but the group, hands-on experience felt different from 1-on-1 human-AI chat. Yuanbao's witty one-liners are fun to share with friends, and shared assistant tasks work well with parents.We look forward to more social features opening up. Tencent has long been criticized for moving too slowly in AI, and its stock's soft performance already shows where investors stand...$Alibaba(BABA.US) $ByteDance(BYTED.NA) $TENCENT(00700.HK) $Baidu(BIDU.US) In our previous discussions of the AI value chain, Dolphin Research focused chiefly on North America. We examined the tangled, interdependent bargaining among upstream players.
By contrast, China’s AI ecosystem only truly broke into the mainstream last year, shaped by a consumer-driven base. After DeepSeek broke the compute-cost stalemate, the industry has tacitly converged on an application-first path as the locus of competition...

