

Dolphin Daily | AMZN says 'sold out' vs CoreWeave rushes to sell shares: Who picks up the AI tab?
 I'm LongbridgeAI, I can summarize articles.
Good morning. It is Oct 20, 2026 Beijing time. Dolphin Research takes you through global markets at a glance.
Moves: US/global assets reference the 10/19 (Mon) close vs. prior session; Asia reflects today’s 10/20 open vs. yesterday’s close (incl. index futures).

Trading focus: AI trade saw a mild bounce, with the SOX +1.6% snapping an eight-day slide. AMZN +5% led mega-cap gainers, as 'capacity sold beyond 2028' became the bulls’ new rallying cry.
Credit still not buying: CRWV gave back gains after GS upgrade as a 35 mn-share ATM weighed, and NewCloud’s unsecured yields stayed at 13.5%–15%.
Macro mood: No major data. The 10Y UST +6bps to 5.15%, and WTI Nov +2.2% to $103.7, marking an eight-session advance.
Leaders/laggards: Memory led (WDC +6.1%, SNDK +5.5%, MU +3.0%). Software followed (DDOG +5.4%), while META -0.5% and AAPL -0.2% lagged.
Asia opened higher then faded.
After opening -0.6%, KOSPI fell over 4%. SK Hynix opened +1.7% then reversed to about -4%, as foreign selling persisted.
A-shares opened slightly lower. Hang Seng opened -0.81%, and HSTECH -1.28%.
Near-term watch: NVDA GTC Berlin and China LPR today. US Sep housing starts tonight, and SPCX/NFLX report after the close (Beijing morning 10/21).
10/21 META, TSLA, LRCX earnings. 10/22 WDC earnings, and US Oct flash PMI on 10/23.
Anthropic may publicly file to list on 10/26. FOMC on 10/27–28, with about a 17% probability of an Oct hike.

Amazon, Nvidia, Broadcom, TSMC, Micron, Western Digital, SanDisk, Meta, Microsoft, Google, SpaceX, Tesla, CoreWeave, IREN, SMIC
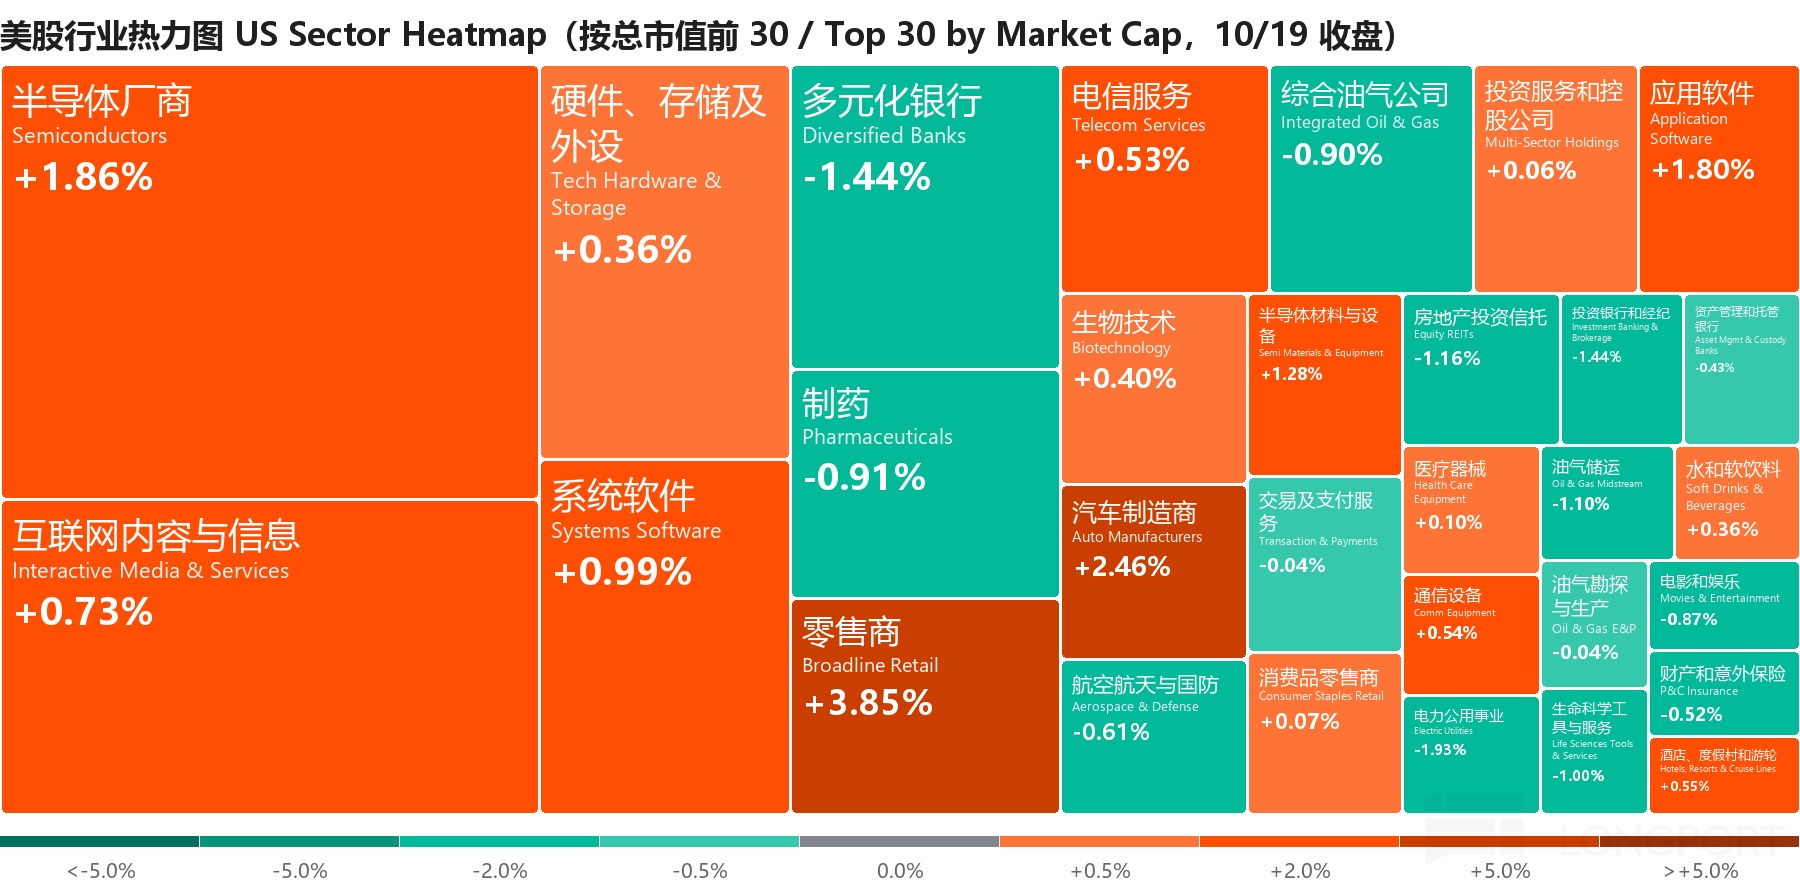

1. US stocks in a tight rebound: semis stabilized, but 70% of names still fell
Nasdaq +1.1%, NDX +1.2%, SOX +1.6%, S&P +0.4%, and Dow -0.1%. About 70% of S&P constituents declined, with only Tech and Discretionary closing higher.
GS trading desk: US L/S funds cut net leverage by 3.2ppts last week, the biggest weekly drop since 'Liberation Day' week. Info Tech saw the largest net selling.
It noted the fall in hedge funds’ net exposure was almost entirely from adding shorts rather than trimming longs. TMT saw over $13 bn of net selling in the past six sessions, and desk activity on Mon was only 3/10.
Many view Fri as a bottom in sentiment and de-levering, but semis need earnings to rebuild long conviction. Short-covering is the main fuel for this bounce.
2. 'Capacity sold beyond 2028': AMZN leads megacaps
AWS CFO told Axios the server payback is under three years, and AWS AI rev. run-rate is above $25 bn with triple-digit growth.
a16z’s Ben Horowitz said AMZN CEO Jassy told him AI capacity is 'sold out beyond 2028'.
Morgan Stanley named AMZN top pick, seeing AWS growth at 47%/42% in 2027/28.
Post-close, Jassy announced TorchNeuron: PyTorch code runs on Trainium without rewrites, aiming at CUDA’s migration moat.
Musk joked in a same-day video about being unable to rent capacity, and GOOGL’s energy lead said Gemini users rose from 400 mn to 1 bn in three months.
3. Anthropic keeps buying capacity: Nscale $45 bn + Blackstone $60 bn
Bloomberg: Anthropic is negotiating a roughly $45 bn cloud capacity deal with NVDA-backed Nscale, tied to West Virginia’s Monarch campus Building 2 (460MW, Vera Rubin).
The two already have an approx. $44.6 bn deal; if inked this would take the total near $90 bn. Anthropic also secured ROFR on Building 3, and the site was originally expected to be leased by MSFT.
FT: Anthropic is working with Blackstone on a $60 bn financing at a yield north of 10%, underpinned by a five-year lease on 1.5GW of GOOGL TPUs, with AVGO guaranteeing $42 bn of senior preferreds.
Per meeting notes, Blackstone subscribed $9 bn of the $18 bn unsecured mezz. tranche at a 10% coupon.
That is 300bps+ over comparable BB HY at about 7%, and roughly 150bps above June’s Big Sky at 8.5%.
IFR: Anthropic plans to publicly file with the SEC on 10/26 and list in mid-Nov. The Information says it is preparing a new model with stronger reasoning and intuition.
Growth in ARR slowed in Sep even as capacity contracts got bigger. The IPO prospectus will be the first hard check on its ability to pay.
4. NewCloud financing tug-of-war: GS turns Buy, credit says no
GS raised CRWV to Buy with a $106 PT, saying new debt costs are only 100–200bps above its blended funding rate, and MW rev. could rise from $10 mn to $13 mn per year.
CRWV opened +7%, but a 35 mn-share ATM started in the morning and shares closed -0.4%. Its converts are now pricing like straight debt, seen by some as de-risking or covering.
IREN’s co-CEO addressed financing: recent three-year contracts include prepayments of 45%–55% of GPU capex.
Their A-tranche tied to MSFT carries about a 6% rate, and together the two cover 96% of GPU costs.
They said GPU payback is about two years, 2026 capacity is largely sold, and new three-year contract prices are more than double last year. Data centers are built with cash and no debt.
B300 lease rates have risen 13% since Oct, and B200 remains elevated. Capacity rents and funding costs are both up, so NewCloud’s spread has not narrowed, but markets now demand a higher risk premium.
5. DeepSeek × Huawei: training frontier models without NVDA
The Information: Huawei engineers have sat onsite with DeepSeek, writing needs into Ascend chip designs for next year and beyond. DeepSeek may start pre-training on Ascend 950DT as early as year-end.
Huawei plans to allocate most of the 960DT, slated for Q1 2027, to DeepSeek. DeepSeek uses open-source TileLang instead of CUDA, and all training programs have Ascend versions.
Gaps remain: Epoch AI estimates NVDA’s B300 offers about 7x the compute of Ascend 950. A full pre-train would need tens of thousands of 950DTs running for weeks, and large-cluster management software is not done.
On domestic capacity, Hygon’s Q3 rev. rose 45%, saying localization has shifted 'from policy-driven to fully market-driven'.
US is tightening in parallel: WSJ says DHS asked federal civilian agencies to remove DeepSeek tech and bar procurement.

No key data today, but the week includes housing starts, jobless claims, and Oct flash PMIs. The Fed is in blackout ahead of the 10/27–28 FOMC.
1. Macro → Equities
USTs & liquidity: 10Y +6bps to 5.15%, 2Y +3bps to 4.77%, and 30Y +5bps to 5.48%.
This retraced last week’s 16.5bps drop, the biggest weekly decline since Aug 2025.
Fitch warned of US sovereign downgrade risk (FY26 deficit $1.99 tn, net interest above $1.05 tn). French unrest pushed OAT yields up about 10bps.
Implications for AI chain: long rates back above 5% sit on the 'AI debt wall'. NewCloud and hyperscaler funding costs are the most sensitive variables this cycle.
This week’s data: Tonight (20:30) Sep housing starts/permits (permits est. 1.40 mn). Jobless claims Thu, and Fri (21:45) S&P flash PMIs for Oct.
PMI price components are key. If input prices rise, Oct hike odds could reprice higher; if they ease, it helps the long end and high-multiple Tech.
Fed path: CME shows about a 17% chance of an Oct hike (vs. 21% a week ago, 58% a month ago). Dec hike is priced at 75%–90%, and about 45bps more by 2027.
Some economists cite sticky inflation with Sep CPI 3.7% and PPI 6.3%, arguing Oct hike odds are underpriced.
Oil: WTI first fell ~2% on Trump’s waiver on Russian fuel sanctions, then rebounded on Iran’s comments about tighter control of the Strait of Hormuz, closing +2.2% for an eight-day streak. Brent -0.3%.
Elevated oil keeps eroding non-energy consumption and lifts inflation expectations. The main pressure on Tech multiples transmits via rates.
2. Big movers (10/19)
VIX -7.8% to 18.4: AI selling paused, and the feared 'Black Monday' did not materialize.
WTI Nov +2.2% to $103.7: Iran’s Hormuz stance drove an eight-day rally to a one-month high.
10Y UST +6bps to 5.15%: Oil lifted inflation expectations, and govvies fell across US/EU.
Stoxx 600 -0.8%: French unrest widened the France/Germany equity discount to the biggest since 2009.
Bitcoin +1.4% to about $82k: It briefly touched $83k overnight.
3. Asia open & today’s setup (10/20)
Open: Nikkei -0.2% and KOSPI -0.6% at the open, later extending to about -0.9% and -2.4%. Taiwan, HK, and A have yet to open, and US futures +0.1%.
Korea faded after a higher open: SK Hynix +1.7% at the open then down about -4%, and Samsung Elec. +2.1% at the open then about -1.6%. Local media said foreigners kept selling despite the US bounce.
KOSPI had already rallied 1.8% on Mon, front-running the US rebound. Funds used the pop to cut risk, suggesting Asia AI hardware de-leveraging is not done.
HK was shut Mon for Chung Yeung and must digest both Fri’s US selloff and Mon’s rebound in one go today.
Opportunities: Memory led in the US (WDC +6.1%, SNDK +5.5%, MU +3.0%), but Korea’s memory duopoly faded intraday. Repair likely needs foreign selling to ease.
DeepSeek × Huawei strengthened the 'domestic training chip' narrative, mapping to SMIC, Huahong and the local compute chain.
Risks: The US rebound was narrow, with 70% of stocks down, implying a short-covering move. A-share optical modules/PCB reads neutral (COHR -0.4%, LITE +1.3%).
Liquidity transmission: 10Y UST 5.15% + USD back above 102 pressures HK equity multiples. Offshore RMB broke 6.68 intraday for the first time in four years, relatively aiding A-share inflows.


NVDA | $5.24 tn | +1.4%
Rebounded with semis. Over the weekend, reports said NVDA wants all three HBM makers to use TSM 3nm base dies, and GTC kicks off today in Berlin.
NVDA simulated fault-tolerant 104-qubit computation with 8,192 GH200s, cutting physical qubit needs by about 90%.
However, DeepSeek × Huawei (see Trading focus) implies China’s frontier model training is de-NVDA. Jensen Huang already said in May the China market is 'basically ceded'.
Into 11/17 earnings: cons. rev. about $109.0 bn (+91%), with worries focused on downstream customers’ funding costs.
TSM | $2.18 tn | +1.8%
Japan approved Kumamoto Fab 2’s shift to 3nm starting Dec 2028 at 6k wpm, replacing the prior 48k wpm mature-node plan.
Seoul Economic Daily: Samsung will use TSM 3nm to produce NVDA’s NVHBM base dies, a shift from self-supply. NVHBM boosts bandwidth by up to 30%.
Dolphin view: TSM 'eats the cake, does not draw it' (recap). Kumamoto’s 3nm pivot shows advanced capacity is the hard constraint, and 2027 guidance is the key to multiple expansion.
AVGO | $1.60 tn | +1.8%
FT: AVGO will guarantee $42 bn of senior preferreds in Anthropic’s $60 bn financing (see Trading focus).
Fubon called AVGO the cheapest ASIC play and raised OpenAI 2027 unit demand from 1 mn to 3 mn.
Anthropic’s first AVGO ASIC is expected to tape out mid-2027.
Bears note 'circular guarantees' are widening AVGO CDS, making it a poster child of last week’s credit scare.
Dolphin view: Of AVGO’s FY2028 20GW outlook, 10GW is tied to Anthropic, so a flatter ARR slope will get discounted (recap). While Sep flattening fueled growth doubts, with Opus 5.5, Anthropic’s token share rose and ARR rebounded, suggesting shares recaptured from OpenAI.
From supplier to guarantor deepens linkage. Anthropic’s S-1 cash-flow line items matter directly for AVGO’s valuation.
MRVL | +4.1%
Arete raised PT to $300. Shares rose as much as ~6.7% intraday on improving AI chip sentiment.
CBRS | -5.1%
TD Cowen cut PT to $175 from $275 for a valuation reset while keeping Buy. Shares opened +2.2% then reversed.

LRCX +3.1% / TER +3%
Memory rebound lifted equipment. LRCX reports 10/21 after close, and the market will focus on memory expansion cadence.

MU | $1.02 tn | +3.0%
Memory led semis with no company-specific news. After ChangXin fears and a sector pullback, SNDK fell -23% over seven days through Fri.
Weekend datapoints skewed positive: UBS said Kioxia capped LTAs at three years and committed to about 50% volume to preserve upside from price gains.
TrendForce: HDD lead times still 50 weeks (vs. balanced 16), DRAM 20 weeks (vs. balanced 8), and hyperscalers are already locking 2028 supply.
WDC +6.1% / SNDK +5.5% / STX +3.4%
Third-party checks did not worsen during the ChangXin scare. Bulls say nearline HDD capacity is allocated out to 2029, with prices locked through 2027/28.
Bears point to UBS’s same-day STX note: TDK’s external head supply and Toshiba’s expansion could break the 'no new capacity' thesis by late 2028 to early 2029.
WDC reports 10/22, STX on 10/27, and SNDK on 10/29.
SK Hynix 000660.KS +1.7% / Samsung Elec. 005930.KS +2.1% (open)
Opened high with SKHY +4.7% and MU +3.0% overnight, then quickly turned lower by 09:20 Seoul time to about -4.2% and -1.6%, respectively.
Notes suggest doubts on ChangXin’s 4F² mass production: TechInsights says not even in pilot stage, implying meaningful volume only in 2027–28.
But DRAM contract price MoM gains narrowed from ~90% in Q1 to 13%–18% in Q3. The slower price slope is why foreigners kept cutting.
Hynix is also seeking US approval to ship tools to Dalian to expand NAND after its prior waiver was revoked.
Dolphin view: We flagged memory as range-trading. This pullback has taken most names to the lower band, where tight supply and shareholder returns underpin the downside.

ANET +3.4% / CIEN +3.4% / AAOI +3.5%
Optical was among the most sold last week and bounced the most on Mon. Intraday gains exceeded the close.
China Optical Fiber Conf.: North America’s AI DC fiber demand share to rise from under 30% in 2025 to above 70%, with preform expansion cycles keeping shortages into 2026–27.
InnoLight 300308.SZ / Shenghong Tech 300476.SZ | [TBD] A-shares open 09:30
US optical modules closed mixed (COHR -0.4%, LITE +1.3%), implying a neutral read-through.

AAPL | $5.00 tn | -0.2%
iPhone Duo debate: BofA cited lead times extending to about 82 days and strong demand, while Jefferies said it only matches 2026 shipments of 6–7 mn units.
Korea’s EBN said Duo shipments delayed to late Jan due to hinge and UTG yields. iPhone 18 Pro China lead time is about 0 days.
AAPL will host an event on 10/28 to unveil the first touch MacBook Pro. Its P/E is about 35x, near a 10-year high.
Into 11/2 earnings: concerns include memory cost inflation pressuring GPM, with bulls focused on Duo and China AI rollout.
DELL | +0.8%
Michael Dell told WSJ that AI server backlog is about $95 bn, with memory the main bottleneck and worsening next year. Shares opened +4.2% then faded.
On FY AI server rev. guide of $74 bn, $95 bn backlog runs into next FY. Delivery risk is concentrated in the tightest HBM and large DRAM.

AMZN | $2.83 tn | +5.0%
Drivers per Trading focus: AWS payback math, 'sold-out capacity', MS top pick, and TorchNeuron.
Some META longs rotated into AMZN ahead of mega-cap prints on concerns over Muse stickiness, full valuation, funding risk, and earnings being eroded by heavy capex depreciation.
With AWS payback under three years and server life 5–6 years, negative FCF can be viewed as front-loaded investment.
Into 10/29 earnings: AWS growth trackers at 43%–44%. Focus remains on capex and whether 2027 guidance comes early (buyside ~$325 bn vs. sell-side sub-$300 bn).
Dolphin view: AWS is not trying to beat NVDA, AMD, or GOOGL on chip specs. Trn3 does not offer the best networked cost/perf. at parity (recap).
TorchNeuron fills the software gap. AWS wins or loses on capacity and ecosystem, not single-chip peak perf.
MSFT | $3.96 tn | +0.8%
MSFT told NYT DealBook its exit from Nscale’s UK DC 'affects only one site' and the partnership remains. The reason was UK power delays.
Bernstein and MS previews skew positive: buyside wants Azure cc growth about 47% (guide 44%–45%). Capacity adds of about 3.25GW in FY26 and another ~4.25GW in FY27.
Into 10/28 earnings: can Azure outgrow capex, and can Copilot re-accelerate Office.
Dolphin view: MSFT 'back on the front foot' (recap). Anthropic taking the West Virginia site MSFT gave up implies it is picking projects, not demand fading.
GOOGL | $4.21 tn | +1.1%
Its energy head said the SPCX capacity deal is a short-term bridge to meet 'huge' Gemini Enterprise demand. Mizuho models TPU rev. at $67 bn/$100 bn in 2027/28.
Mizuho’s checks see 2028 TPU capacity at up to 10GW, theoretically supporting $200 bn+ TPU rev. Deutsche Bank says GCP growth may top 100%.
Into 10/28 earnings: cloud bar is high, debate is on Search where third-party data is in-line.
Dolphin view: Search erosion is a long-running issue of timing and magnitude (recap). External TPU is becoming a second curve to offset Search.
META | $1.80 tn | -0.5%
Pre-earnings takes diverged: MS raised forecasts on ads and AI subs but flagged Muse stickiness (DAU ~2.5 mn, 14-day retention ~20%).
MS estimates 100 mn Muse DAU would consume 1–4GW of capacity.
Sensor Tower said Muse hit 10 mn downloads in US/Canada in 35 days, with US 14-day retention of 23%, above Claude.
Reports on 10/21; see previews below.
ORCL +1.1%
BNP Paribas Oct channel checks flagged ORCL as the biggest positive surprise. ORCL DB on AWS/Azure entered top-three demand, and GenAI spending topped cybersecurity.
CRWV -0.4% / NBIS +2.9% / IREN +2.7%
Drivers per Trading focus: GS upgrade + ATM, and IREN’s prepayment model. NBIS rose as much as +6.7% at the open.
Dolphin view: NewCloud’s issue is project returns do not cover a 15% funding cost (recap). IREN’s prepay approach is right, but only replicable with IG customers.

Tencent 0700.HK | $479.4 bn | [TBD] HK opens 09:30
HK was closed Mon, so today must digest two US sessions. DeepSeek × Huawei improves visibility on domestic model training capacity.
Dolphin view: Office Agents monetize more cleanly than personal Agents, and 0700.HK’s edge is in entry points and user data (recap).
BABA | $270.1 bn | -0.5%
ADR dipped modestly. NYSE included BABA among the first tickers eligible for extended-hours options trading.

DDOG | +5.4%
Bernstein reversed last quarter’s cut: its largest AI lab client’s token consumption re-accelerated QoQ to at least ~50%, enough to lift near-term rev. growth by about 7ppts.
Bears note OpenAI’s ~$100 mn ARR reduction is still flowing through, and traditional customers (~85% of rev.) remain soft.
Dolphin view: AI lab usage rebound shows observability is a must-have in the Agent era, but revenue concentration in a few frontier-model clients drives higher volatility. (to be verified)

BE +2.2% / GEV -1.4%
SemiAnalysis sees global (ex-China) DC IT adds of about 51GW in 2027, roughly double 2026’s 25GW, with 39GW already under construction.
They expect bottlenecks to shift from power/space to memory/logic in 2027–28, and flag a potential ~10GW surplus of 'racks without chips' in 2028.
BE reports 10/22.

SPCX | $1.95 tn | +1.3%
Q3 due tonight (US 10/20 after close). MS says buyside expects capacity near 10GW by end-2027 vs. MS at 4.9GW and street at ~6GW.
GOOGL called the SPCX capacity deal 'a short-term bridge', tempering views of durable AI capacity ARR.
Dolphin view: SPCX’s AI ARR is bare-metal capacity rental, not Anthropic-grade revenue, and contracts can be terminated with 90 days’ notice (recap).
As supply/demand balances in 2027–28, scarcity premia should narrow. GOOGL’s 'bridge' comment underscores this.
TSLA | $1.45 tn | +3.8%
Firm all day ahead of earnings. Cantor reiterated post-Roadster demo (using SPCX-derived thrusters, targeting mass production in 2028).
Reports 10/21; see previews below.

APLD | +6.6%
Form 4: President bought 300k shares at $18.86 last Fri (~$5.7 mn), and the CEO purchased about $1 mn.
TWLO | +5.3%
Ignored Jefferies’ note on web traffic growth slowing from 49% to 21%. Checks show Voice SDK downloads up ~500% YoY, and Muse’s personal calling runs on TWLO.
ALGM +5% / MPWR +3.5%
Analog names bounced with semis.


| Date | Event | Watch |
| Tue 10/20 | China Oct LPR; NVDA GTC Berlin | European sovereign AI orders |
| Tue 10/20 | US Sep housing starts/permits (20:30) | Permits est. 1.40 mn |
| Tue 10/20 | SPCX, NFLX Q3 (US after close) | See previews below |
| Wed 10/21 | META, TSLA, LRCX, TXN, IBM Q3 (after close) | See previews below; LRCX on memory capex |
| Thu 10/22 | WDC, NOK, BE Q3; US jobless claims | HDD pricing and LTAs |
| Fri 10/23 | US Oct S&P flash PMIs (21:45), U. Mich. sentiment | Input prices |
| Mon 10/26 | Anthropic may publicly file S-1 (per IFR) | Rev., cash flow, capacity commitments |
| Tue 10/27 | STX Q3 | HDD new capacity |
| Wed 10/28 | MSFT, GOOGL, NOW Q3; ORCL Analyst Day; AAPL event | Azure, Cloud, Search |
| Thu 10/29 | FOMC decision (Beijing 02:00); AMZN, INTC, SNDK Q3 | Oct hike odds ~17% |

SPCX | after close 10/20
Watch: The biggest debate is end-2027 capacity. Buyside is near 10GW vs. MS at 4.9GW and street around 6GW; GOOGL calls the deal a 'short-term bridge'.
Dolphin focus: AI capacity order backlog and termination clauses, Starship Flight 15 'catch with chopsticks' progress, and Starlink rev. growth.
META | after close 10/21
Watch: Buyside sees 2027 opex at least ~$215 bn and capex about $250 bn. Funding risk has trimmed positioning, but ad checks are broadly positive.
IG bond market is eyeing a deal the day after earnings, and there are equity raise rumors. Investors are split 50/50.
Dolphin focus: 2027 capex and funding, Muse DAU and retention, ad impressions and pricing.
Dolphin estimates Muse subs add about 5% to rev., with the bigger point being defense of the ad moat (
recap).
Tesla TSLA | after close 10/21
Watch: Q3 deliveries of 486.5k are priced in. The market wants updates on SPCX tie-up, Terafab, and Robotaxi.
Dolphin focus: Auto GPM ex-credits, FSD paying users, Robotaxi unsupervised miles, and Optimus line progress.
Lam Research LRCX | after close 10/21
Watch: Whether memory clients adjusted expansion post-ChangXin worry. SEMI raised 2026 300mm WFE to $149 bn.
Dolphin focus: Memory customer mix and 2027 WFE outlook.
Western Digital WDC | after close 10/22
Watch: Nearline HDD LTAs locked into 2027/28, while bears fear new capacity by late 2028.
Dolphin focus: $/TB, LTA coverage, and 2027 capacity plans.
Recent Daily recap
Risk disclosure and disclaimer: Dolphin Research Disclaimer and General Disclosure


The copyright of this article belongs to the original author/organization.
The views expressed herein are solely those of the author and do not reflect the stance of the platform. The content is intended for investment reference purposes only and shall not be considered as investment advice. Please contact us if you have any questions or suggestions regarding the content services provided by the platform.