Context
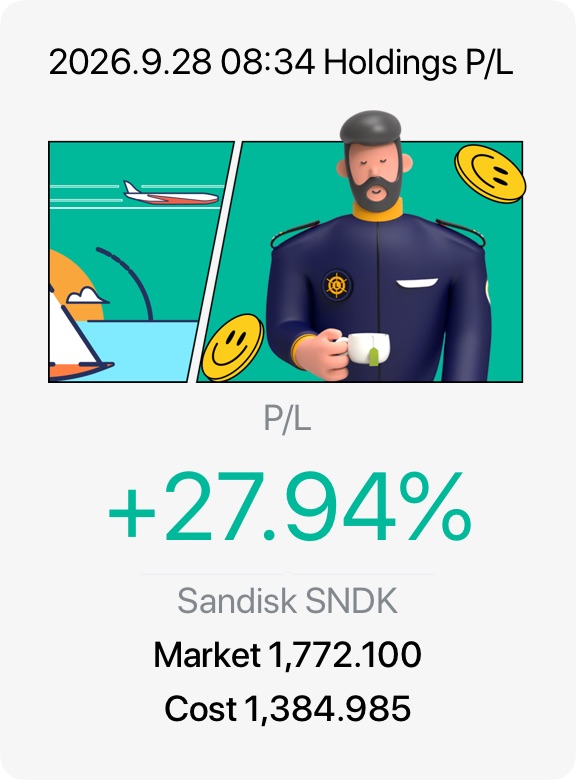
SanDisk Corporation (SNDK) has undergone a massive structural shift since completing its official separation from Western Digital. Now trading as an independent pure-play AI memory and high-performance NAND storage provider, the stock experienced a meteoritic +1,600% run over the past year before enduring a severe 35% drawdown from its summer high of $2,354.39.
Despite the technical cooling off, SanDisk’s underlying business metrics are powerhouse level: the company reported fiscal Q4 revenue of $8.97 billion (a 372% year-over-year surge), an industry-leading non-GAAP gross margin of 84.6%, and secured an astronomical $93.9 billion backlog via multi-year contracts with 8 core hyperscalers (including Meta). Essentially, memory is shedding its historical “cyclical commodity” discount and re-rating as critical AI enterprise infrastructure.
My trade
Given the massive gap between the company’s stellar fundamentals and the recent technically-driven chart drawdown, I executed a Buy the Dip strategy:
Entry Point: Will load on more shares heavily as the stock bottom out near the $1,500 – $1,550 support band, capitalizing on the panic sell-off triggered by temporary sector-wide macro rotations.
Takeaway
SanDisk is no longer a legacy flash drive producer; it is now fully entrenched as a structural AI infrastructure engine. The massive multi-year contracts provide predictable revenue visibility that is practically unheard of in traditional cyclical semiconductor history. With management holding a robust, debt-free balance sheet and ample runway for extensive share buybacks, the fundamental bull case remains incredibly strong.
Traders should ignore the short-term noise and use steep drawdowns to accumulate exposure, keeping a close eye on whether upcoming guidance can continuously sustain these historic 80%+ gross margins.