Context
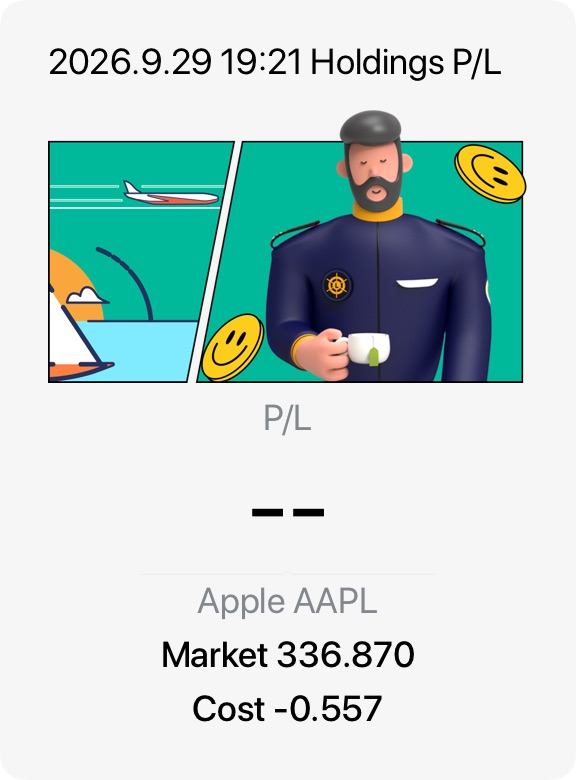
Apple Inc. (AAPL) has emerged as the top-performing “Magnificent Seven” stock of, driven by an accelerating hardware upgrade cycle and highly resilient services expansion. Following the launch of the iPhone 18 series, early market checks from major firms like Morgan Stanley and J.P. Morgan point to steady consumer demand internationally, with lead times stretching out 3 to 4 weeks for premium Pro models. Financially, the company remains an absolute powerhouse, delivering an EPS of $2.02 on $109.42 billion in revenue during its most recent fiscal quarter, comfortably beating Wall Street consensus projections.
However, this massive multi-month run has pushed Apple’s market capitalization up to $5.0 trillion. This has created a valuation premium, with the stock trading at a trailing price-to-earnings (P/E) multiple of 38.8x. Several fundamental analysts note that the stock screens as modestly overvalued relative to its intrinsic discounted cash flow (DCF) model, which suggests that immediate near-term upside may require exceptionally strong sales momentum to stay justified.
My trade
Buy Zone: $315.00 – $325.00. Accumulate on minor technical pullbacks toward the 50-day moving average or psychological support boundaries.
Price Targets: $362.00 (Short-Term / 6-Month Target) | $395.00 – $400.00 (Long-Term / 12-Month Target.
Stop Loss: $298.00. A decisive daily close below this dynamic horizontal baseline invalidates the recent structural breakout trend.
Takeaway
Apple presents a classic blue-chip dilemma: immaculate execution and robust institutional support clashing directly against a highly extended valuation premium. While momentum-driven traders may encounter minor near-term consolidation around its current record highs, the underlying business remains heavily protected by its vast installed device ecosystem, high-margin recurring subscription revenue, and an aggressive multi-billion-dollar share buyback framework.