

METAM

RDDT: Live by GOOGL, Die by GOOGL
 I'm LongbridgeAI, I can summarize articles.
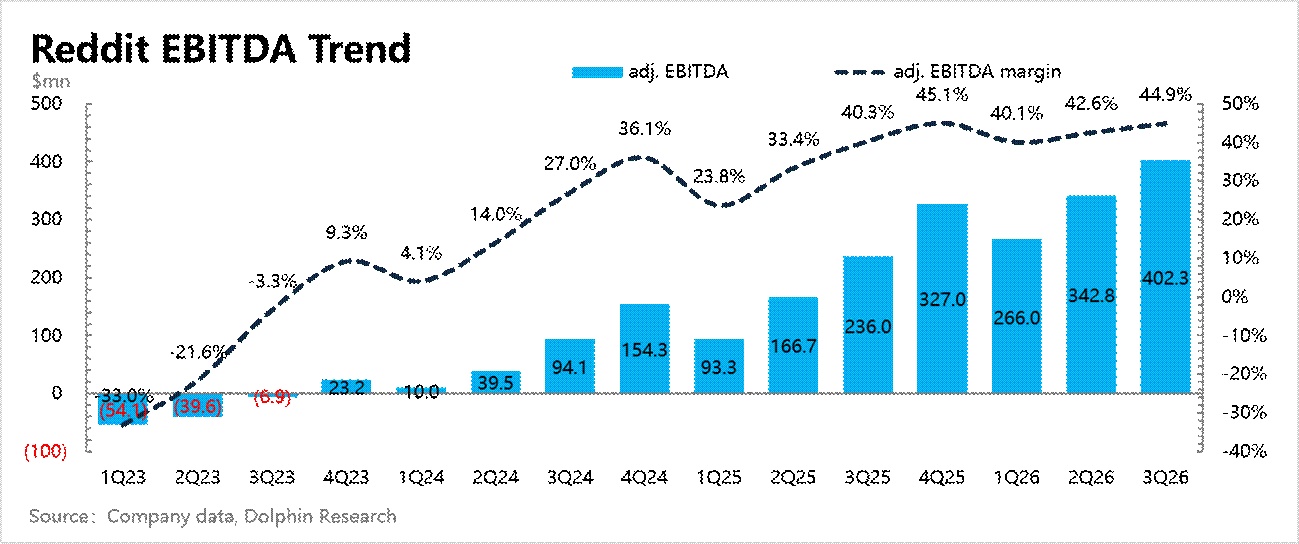
1) Big picture, $Reddit(RDDT.US) missed on the two headline metrics: users and the next-quarter guide both came in below estimates. Profitability held up, with margins improving QoQ.
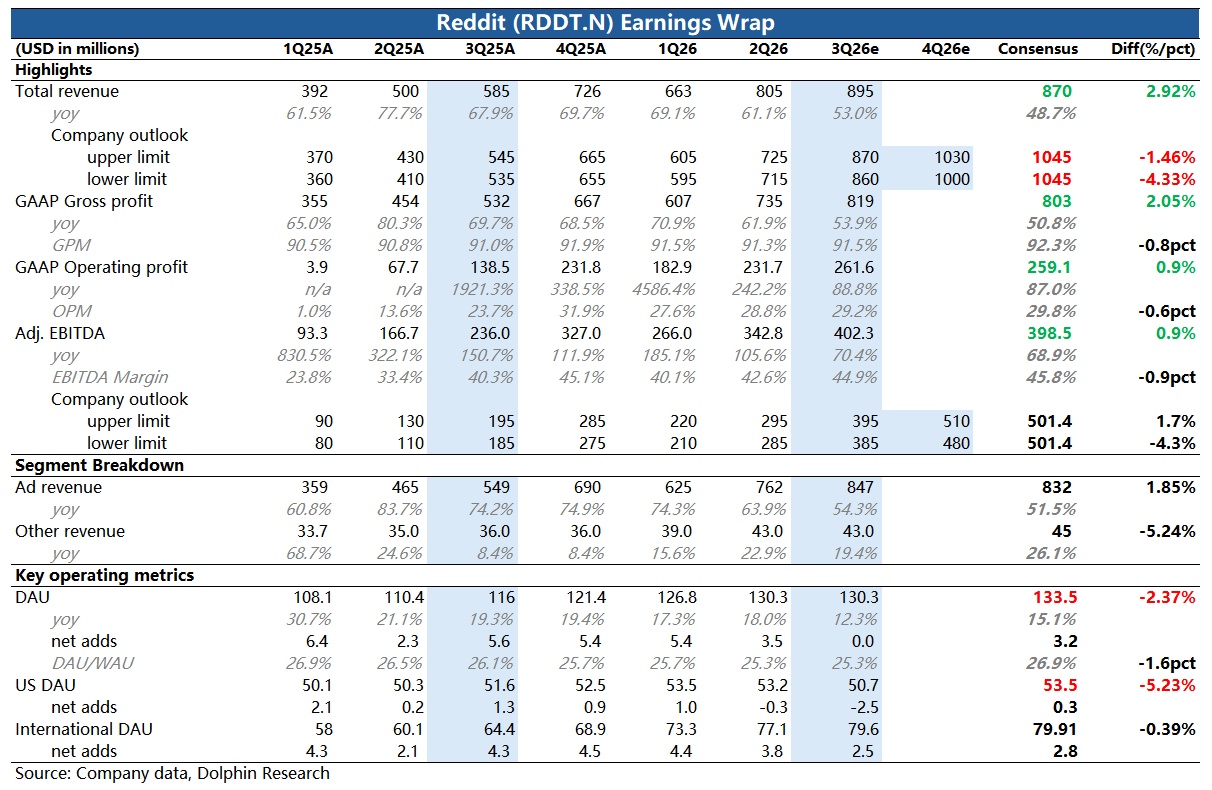
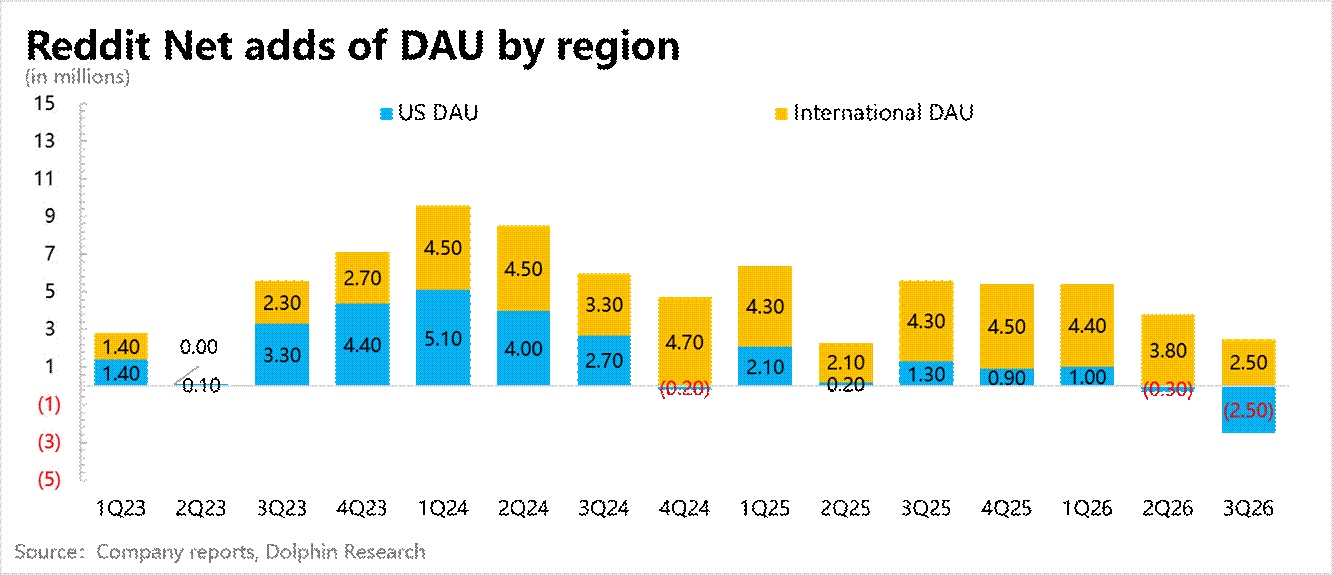
2) The core issue is user growth. U.S. user growth had been lackluster, but at least still net positive, and Intl penetration expanded aided by AI translation. Meanwhile, monetization was in a high-growth phase, and the positives outweighed the negatives.
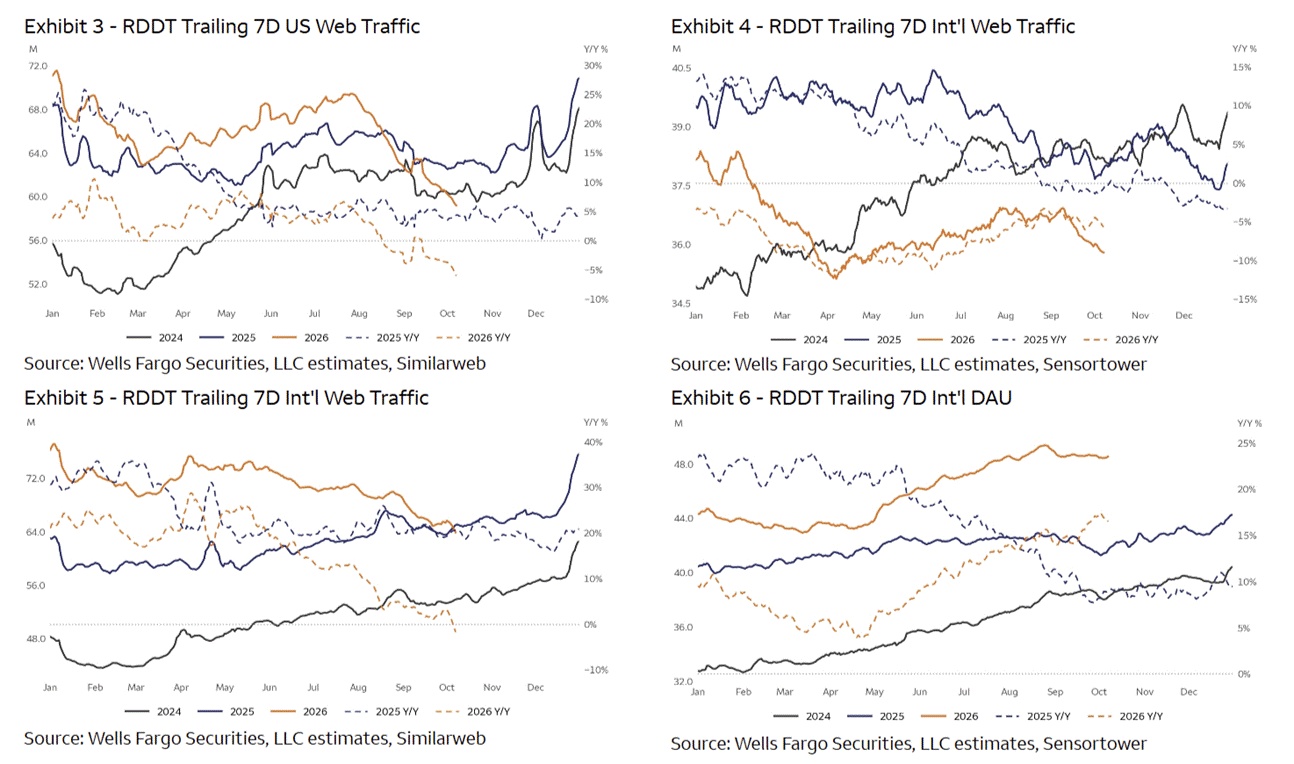
But this time, U.S. saw deeper net user losses, and Intl net adds also slowed, with early-Q4 impact persisting. The user drag, combined with a more mature commercialization phase, made growth harder and directly weighed on Q4 monetization.
3) There is essentially one reason: Google is no longer a traffic crutch. That is the crux.
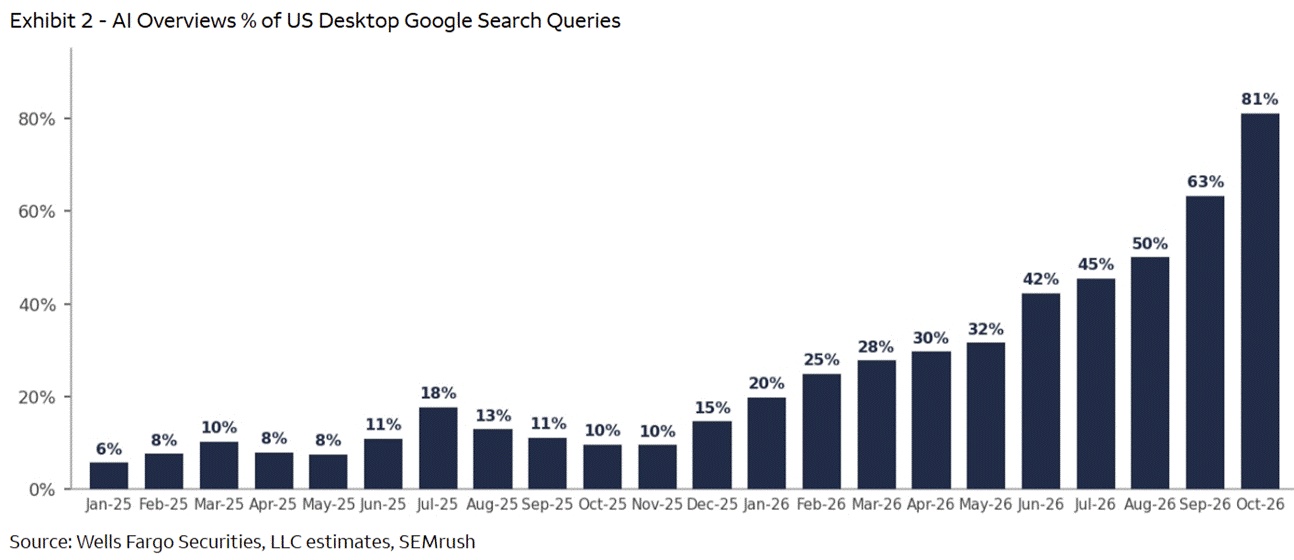
(1) In H1, Google downgraded traffic weighting for machine-translated content, which hit user numbers. Growth resumed in the back half of Q2.
(2) In Q3, Google pushed AI Overviews penetration from 40% in Q2 to 80% by quarter-end. These AI Overviews route far less traffic to Reddit than traditional search.
4) The company is actively in 'self-help', seeking to shed dependency early. It aims to move toward self-reliance.
Management is pushing an app-first model, steering users from web to the app. Web-to-app one-tap flows are being scaled, alongside marketing to encourage migration, and surveys indicate new-app-user retention above 50%.
This implies near-term revenue growth will inevitably decelerate due to platform migration, unless the company proactively expands ad inventory and raises pricing. Max is opening to all advertisers, with added ad API, Smartly integration, and asset groups.
At the same time, marketing and product development spend will likely rise. This could create dual pressure on profits and weigh on margins.
5) Valuation: what got hit is the narrative. Let sentiment reset first.
U.S. ARPU (revenue/DAU) is $14 per quarter, and in Q2 and Q3, with limited Google referral traffic, ARPU rose 22% and 18% QoQ, respectively. Monetization still has headroom vs. leaders like Meta and Google, but already exceeds smaller platforms.
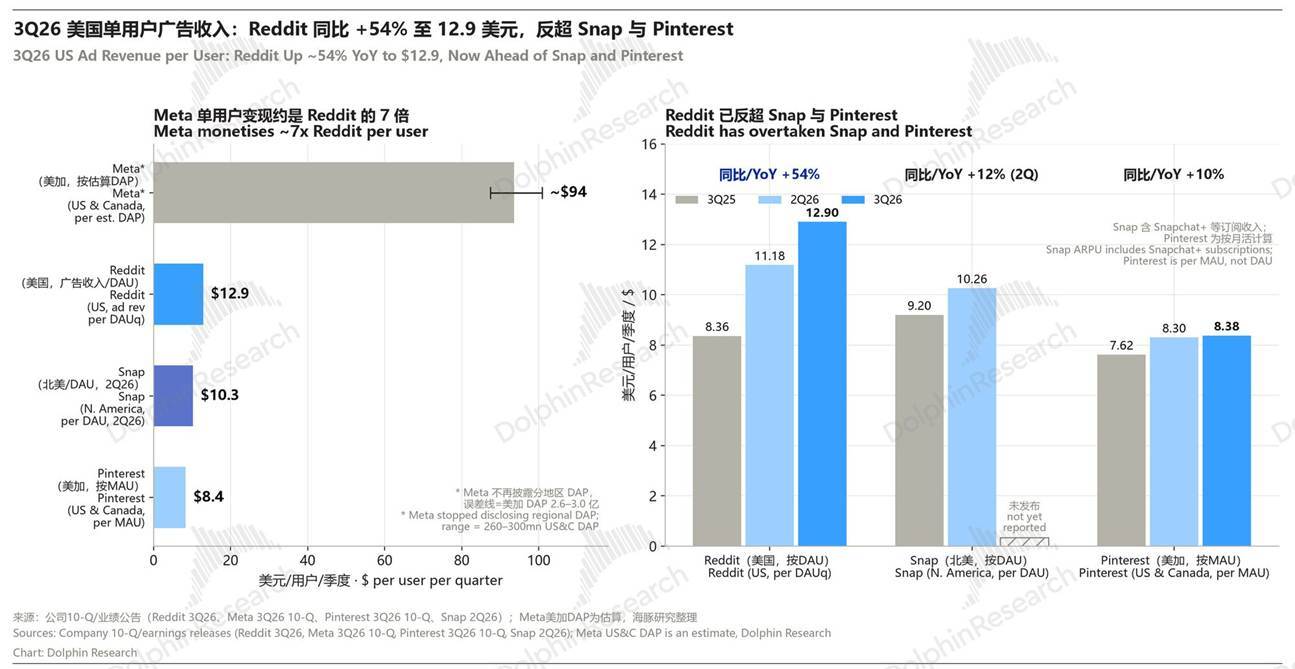
With Google's boost, advertisers paid a premium for incremental traffic. Without that channel, advertisers' willingness to pay is likely to weaken.
Dolphin Research cut its prior 2027 revenue outlook by 5% and lowered OPM from 33% to 30%, roughly the current level. Assuming a 15% effective tax rate, post-tax GAAP operating profit comes to $1.1bn.
Post-earnings, the stock fell 23%, leaving a $19.2bn market cap, implying 17.7x on the 2027 estimate. Near term, the multiple looks overly punished, but it also signals cautious views on Reddit's mid-to-long-term outlook. We prefer to wait for sentiment to clear and track high-frequency user data for stabilization in churn, then look for a re-rate toward a 20x–25x neutral band.
6) Call notes: Reddit (Trans): Google traffic cut accelerates, betting on 'login-only'. Link above.
Risk disclosure and disclaimer: Dolphin Research Disclaimer & General Disclosure.
The copyright of this article belongs to the original author/organization.
The views expressed herein are solely those of the author and do not reflect the stance of the platform. The content is intended for investment reference purposes only and shall not be considered as investment advice. Please contact us if you have any questions or suggestions regarding the content services provided by the platform.