
Yeah not sure how anyone thinks it's over on AI semis like $NVIDIA(NVDA.US) GPUs, memory, to photonics, after $SpaceX(SPCX.US) earnings.
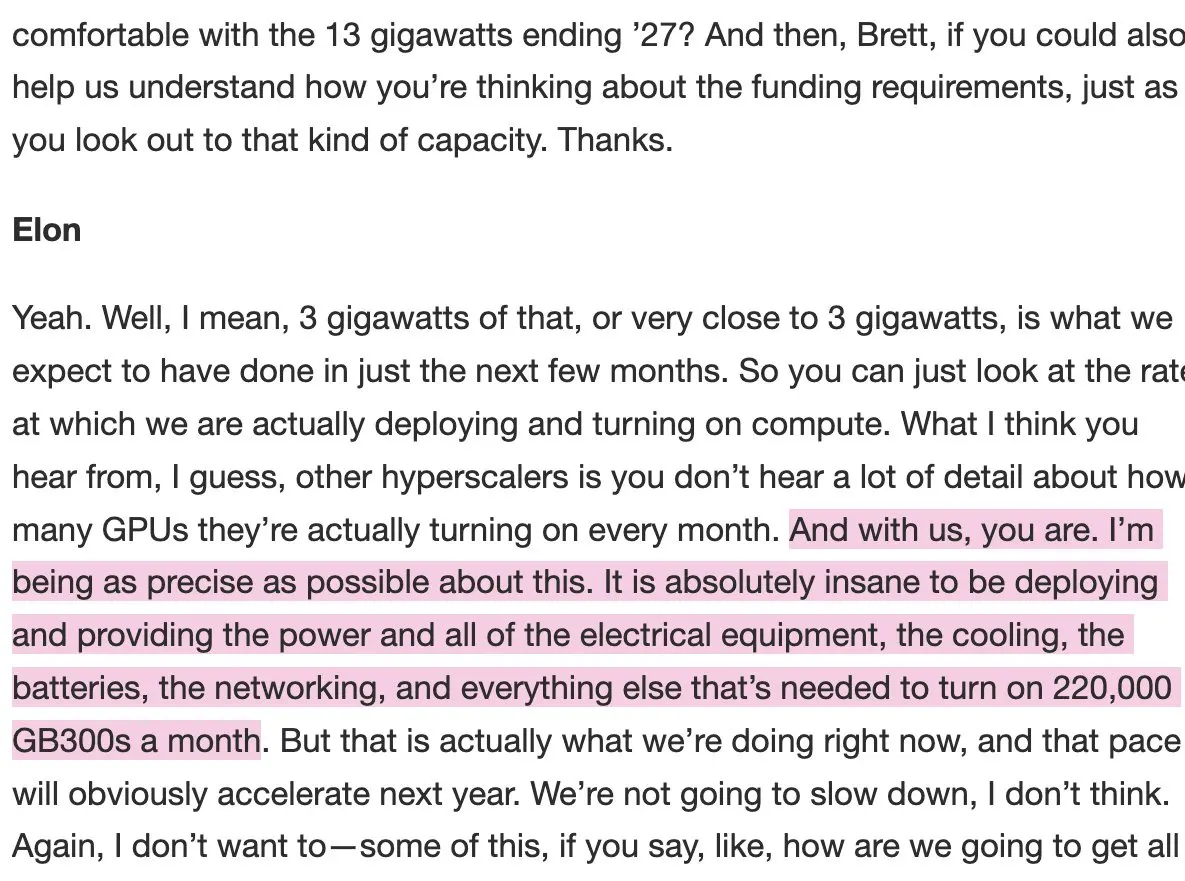
- Previous Q4 capex outlook ~$18.4B... Now $35–40 billion Q4 capex guidance, basically doubling previous outlook"Q3 and Q4 capex should be similar to Q2's $18.37B" from CFO in August. -Elon: "If everything goes right, we’ll have 20 gigawatts of incremental power next year" "High confidence of 10 GW next year, and 20 is difficult but not impossible- "I’m being as precise as possible about this. It is absolutely insane to be deploying and providing the power and all of the electrical equipment, the cooling, the batteries, the networking, and everything else that’s needed to turn on 220,000 GB300s a month"You're gonna need a lot of HBM, power, networking/optical components to make all of this happen.- Elon projects SpaceX could exit 2027 with an ARR of "$500 billion and $1 trillion by the end of 2027When you see $SpaceX(SPCX.US) double capex outlook next quarter, target another 10GW deployment by next year, and all the procurement needed to turn on 220,000 GB300's a month... Hard not to be bullish on AI semis.
Serenity
AI/Semi Supply Chain Analyst ex. RISC-V FDN, AI research scientist;

S
Feels like the public interpretation is all wrong…
I’m pretty sure $Microsoft(MSFT.US) backing out on NScale deal is bullish for Neoclouds like $Nebius(NBIS.US) or even $IREN(IREN.US) with energized capacity with Microsoft?Pretend Microsoft just ate a bunch of Chipotle burittos:- They order toilet paper delivery scheduled Q1 2027- NScale says: sorry 3-4+ year delay of the toilet paper (into 2030’s) because of UK grid constraints- Microsoft still urgently needs toilet paper so they will get it elsewhereThe cancellation does send warnings about what happens if a Neocloud can’t execute on contracted demand.But that just makes the other toilet paper sellers more valuable since Microsoft will go elsewhere for supply.
S![图片 1,共 1 张]()
$Alphabet(GOOGL.US) is now discussing deals to extend their memory LTAs through 2035 from KeyBanc channel checks.
Samsung already has 70% of their capacity allocated through 2031, and this move would suggest a more durable cycle for $Micron Tech(MU.US), $SK Hynix(SKHY.US), and the others. They also expect HBM prices up 80% to 100% in the Q1 2027. Having all your capacity potentially allocated out into 2035 via LTAs would ease a lot of memory durability fears.
S![图片 1,共 1 张]()
Wow, Largan Chairman dropped a nuke and stated MicroLEDs unlikely to become viable for AI DC buildouts
As for what's up and coming... Feels like $AMD(AMD.US), $NVIDIA(NVDA.US), and everyone in the industry is clearly going out of their way to procure CW laser supply this year. EML was the market's focus last year with $Lumentum(LITE.US) / $Coherent Corp.(COHR.US) (and still partially is). But future architectures with microleds was something to keep watch for 2028 onwards... Since $Credo Tech(CRDO.US) was pretty focused on it with their acqusition of Hyperlume, $American Shared Hosp(AMS.US) Osram was a popular name (working with Credo too), hyperscalers like $Microsoft(MSFT.US) were developing in the space too. Largan is also a $Taiwan Semiconductor(TSM.US) COUPE supply chain player that does FAU like Foci/microlens/passive components, so they're more impartial.But yeah... was a surprise to see Largan Chairman citing concerns over "power consumption, size, and transmission efficiency" for microled commercialization and said it's unlikely to become viable. (source: Digitimes)TLDR:-> MicroLED as a technology unlikely to become viable from Largan Chairman-> If it turns out correct, indirectly positive for lasers like VCSEL, then CW/SiPH since there's some overlap for CPO scale up applications
S
"Potential FCC rules on optical transceivers more likely to come at 3.2T" - $Lumentum(LITE.US), $Applied Optoelectronics(AAOI.US), $Coherent Corp.(COHR.US), $SIVE.
Morgan Stanley met with Washington officials:- Restrictions would likely start at 3.2T modules made in China (800g/1.6T would be left alone)- Potential restrictions would likely keep laser market tight (combining US DSPs + lasers could meet the 65% US value threshold per MS)- Chinese modules could qualify if 65% of bill of materials is US content. Chinese modules using US DSPs and lasers are already near that level- Analysts expect the positive impact on laser pricing... to be more important than any broad redistribution of transceiver market share.- Analysts don't expect this to bottleneck hyperscaler AI buildouts, they name InP substrate supply as the key variable to watch (hello $AXT(AXTI.US) ) TLDR:Component suppliers in general are really positive. Like $Semtech(SMTC.US) probably winner here for TIAs/drivers (I don't think this was listed), maybe $Maxlinear(MXL.US) for DSPs too. $Applied Optoelectronics(AAOI.US) another large beneficiary. $SIVE is high-key alpha for laser beneficaries since they have "tremendous capacity" coming online, and that points to US foundries (they haven't formally disclosed location). Since previous slideshows show 2 US foundries 1 Taiwan foundry (Win Semi) in terms of their capacity partnerships. And it's process of elimination. From CIOE Channel checks it does look like they're starting to work with Chinese pluggable players, (so they'd avenues moving forward as US supply chain component beneficiaries). Of course $Lumentum(LITE.US) / $Coherent Corp.(COHR.US) would be happy. TLDR: Western supply chains for Lasers / DSPs / TIAs / others are already bottlenecked but qualified capacity becomes even more important.
S
Everyone is asking "Where is Serenity" or "Who is Serenity". But nobody is asking...
"How is Serenity"? I do read things from $AMD(AMD.US) $8.2B acquisition of World Labs... but feeling pretty sick right now, so taking a little break. I remember saying physical AI + world models would major shift way back when, so maybe I should have invested in private companies at the time... Apart from that... other interesting news:- Some channel checks from ECOC was that $NVIDIA(NVDA.US) apparently secured 50% of $Lumentum(LITE.US) Greensboro UHP laser capacity? And possibly contracts that allow them to secure the remaining capacity per Barclays. That's $5B in lasers (annual capacity)... so it's hilarious to see Nvidia go out and bottleneck the rest of the industry by doing this. But this just puts more strategic value on other merchant laser suppliers + more visibility for Lumentum.It's kinda game theory over allocation, since if you secure all the HBM, lasers, and others it inadvertently makes it much harder for competitors to scale their programs. - Then there's your massive $150B Nvidia authorized buybacks (just look at $Apple(AAPL.US) when they did buybacks..) They're printing too much. - What's also interesting is that Samsung Electro-Mechanics is expanding their FC-BGA substrate capacity today... but customers are the one funding this. I also remembered $Marvell Tech(MRVL.US) in SEC filings cited large body substrates as one of the core bottlenecks of their program (alongside $Taiwan Semiconductor(TSM.US) sole source dependencies). So they also went out and did some other expansion agreements with related companies like AT&S recently. - OpenAI delaying Astra-6.1 October release over safety concerns just now. Nvidia also happened to launch an AI safety platform. I don't think this is meaningfully bearish that the models are just getting 2 good.
S![图片 1,共 2 张]()
![图片 2,共 2 张]()
If you're curious about the random $SPY / $QQQ candle:
Just now, “US and Iran discuss phased deal to reopen Hormuz and end US blockade" - Reuters- "A deal before the midterms could benefit Trump, as reopening Hormuz could ease tensions in the Gulf, contain oil prices and help bring down politically sensitive US gasoline prices."- "Trump has said he thinks the US and Iran could reach a deal after midterm elections to Congress on November.”Would make sense for Trump to want markets as strong as possible during Midterms elections…S![图片 1,共 1 张]()
I guess I need to start calling $Sandisk(SNDK.US) or $Lumentum(LITE.US) Super Intelligence stocks.
Thanks Trump.
S![图片 1,共 2 张]()
![图片 2,共 2 张]()
Wow Bitcoin + Ethereum pulled pretty extreme recoveries.
Looks like $Robinhood(HOOD.US) / $Coinbase(COIN.US) / Crypto is back? On-chain equities trading + regulator exemptions probably put a lot of fuel into the fire for the sector. That aside... crypto is usually a great indicator for high-beta AI equities believe it or not (they tend to frontrun broader market drops or rallies). So overall market risk appetite might be coming back despite the rate hikes.
S![图片 1,共 3 张]()
![图片 2,共 3 张]()
![图片 3,共 3 张]()
All right $Meta Platforms(META.US) Muse is cooking.
I can hear all the $AMD(AMD.US), $Intel(INTC.US), and $Arm(ARM.US) CPUs vrrrring in the background.Along with the memory + components (NICs, SSDs, DRAM) needed for all the browsers/VMsWhen I ask it to do a bunch of long form tasks… Intel CEO also said recently that CPU demand is so strong they can only support 50% of what customers need, so there’s some signals there.I’m also curious how much $Amazon(AMZN.US) or $Nebius(NBIS.US) is involved with running Muse, or if Meta hosts everything inhouse.Kinda an ADHD post but Meta beat my expectations with this release.Will keep trying it out
S
Just floating out an idea to $Broadcom(AVGO.US):
If you lock up $SIVE laser supply for next few years since you need “more laser capacity”.You could unintentionally cause bottlenecks across your main ASIC competitors:Like $Marvell Tech(MRVL.US) (Celestial), AlChip, Mediatek, GUC (Ayar CPO), first gen deployments. Where many also seem to be aligned with your best friend $NVIDIA(NVDA.US)…Maybe it’s worth discussing spending spare change to lock up the remaining merchant laser supply?
S
I think there’s a gap to fill…
Since I believe retail deserves the same research and early thematic ideas that institutions access first.I feel like everyone understandably gravitates institutional as they grow.But helping retail has always been my priority. And that hasn’t changed even as I grew to 1M followers.I’m excited to see what we can cook up together soon chat.S![图片 1,共 3 张]()
![图片 2,共 3 张]()
![图片 3,共 3 张]()
Anthropic's Economic Scenario publication was a pretty interesting read:
1. Anthropic's "extreme" scenario has GDP growth reaching 15.4% in 2030So around 7.3x current rates (~2.1% Y/Y), which is consistent with what Elon Musk is saying about outgrowing the national debt with AI. 2. Almost all of the divergence happens after 2027. Their model shows relatively little separation in 2026-2027, then the curves bend sharply into 2028-2030. So my read is that it points to 2026-2027 as buildout years and 2028-2030 as economic acceleration. Kinda gets mapped as well when you look at $Amazon(AMZN.US) / $Meta Platforms(META.US) / $Alphabet(GOOGL.US) capex, and short term FCF headwinds (but massive projected profitability post 2028)3. In an extreme scenario, unemployment of knowledge workers goes to 17.9%. With 11.9% economy-wide unemployment"At the individual level, it means coders and call service center agents may have to switch to jobs like electrician and nurse, which are less exposed to AI."GG computer science majors. 4. Non-cognitive wages: +33.6% vs. baseline in an extreme scenario. So your electricians/construction-type labor becomes extremely valuable? (but this isn't factoring in humanoids yet...)Whereas -11.5% for knowledge workers in 2030 vs. baseline. 5. Aggregate capital income is ~81% higher than it would have been without AIProductivity explodes -> aggregate labor income barely changes -> essentially all of the incremental GDP accrues to capital.So that makes ownership of capital rather than labor... so equities like compute, power, semis, networking, robotics, etc. become pretty important... TLDR:- Economic growth go brr- Jobs that require thinking = unemployment + lower wages- Physical labor = more important, like electricians. - AI equities go brrr.S![图片 1,共 2 张]()
![图片 2,共 2 张]()
Wait… this was real? I thought this was The Onion type meme.
Honestly would be more bullish on $Meta Platforms(META.US) if they admitted they trained on thousands of adult films… instead of claiming “personal use”.What could Zuckerberg be cooking?S![图片 1,共 2 张]()
![图片 2,共 2 张]()
Is there any other industry... Where every investor is cheering for shortages and price hikes?
SED reported today that: Samsung / $SK Hynix(SKHY.US) "stockpiles have fallen to less than 10 days of supply, and a severe shortage could emerge next year, according to a new forecast"KB Securities said that the memory market next year will see "the tightest supply conditions in history"KB Securities projects memory's share of AI infrastructure costs to expand from 40% this year to 57% next year, with others like TrendForce placing next year's figure at 68% (total hyperscaler capex, pretty wild forecast attached)"Both stocks have fallen 38% from their peaks over the past three months, pushing their price-to-earnings ratios based on next year's expected results down to about three times."Likewise, commentary around Phison stated they expect extremely tight NAND supply in 2027, so hard to see memory flooding the market or prices collapsing next year... They gave some color that "soaring NAND prices have forced some Chinese consumer module makers to liquidate inventory, giving Phison opportunities to buy lower-priced stock", so it does show some price declines can coexist with broader shortages. TLDR: KOSPI + read through for other names like $Micron Tech(MU.US) / $Sandisk(SNDK.US) might be happy for 2027 given demand causing shortages + infra spend share increase.
S
Let me get this straight chat… you have:
$NVIDIA(NVDA.US) 70% supply constrained revenue growth projections (would be 100%+)$Broadcom(AVGO.US) AI revenue growing 100%+ Y/Y for next 2 years from mid ~$50B -> $230BOpenAI Astra blowing away AGI benchmarks and starting to train itself.$Microsoft(MSFT.US) / $Alphabet(GOOGL.US) / $Amazon(AMZN.US) stating compute demand imbalances into next year, with Nvidia projecting $1.3T spend for 2027.You’re seeing this flow through supply chains from Samsung 70% capacity LTAs into 2031 to Powertech advanced packaging capacity 100% booked into 2030.Even your legacy players like Winbond are starting 2029-2030 allocations.Markets always have temporary drawdowns and macro scares… but…How can anyone not think AI stock go brrr?S![图片 1,共 1 张]()
Anthropic signs a $35B AI compute deal with $NVIDIA(NVDA.US) backed Lambda.
$Hut 8 Mining(HUT.US) / DC, with Lambda / GPUs. Frontier model demand is rapidly outpacing the ecosystem's ability to build capacity.It also looks like Anthropic is securing more compute... Which neocloud/colo player is next?S![图片 1,共 1 张]()
Remember my $SOI thesis anon? Soitec interview commentary today:
- 80% of capacity reservation agreements expected within 1-2 weeks, with more than 10 in total. - $200M Photonics-SOI revenue now described as "absolutely a floor"$Taiwan Semiconductor(TSM.US) also sees SiPH going mainstream in 2027 with market share topping 50%+ of the optical transceiver marketIf you hold a monopoly-like position over a chokepoint:(UBS estimates Soitec has 95% share of the market for substrates underpinning silicon photonics chips)Revenue usually flows through you.
S![图片 1,共 1 张]()
“Memory is a bubble.” Explain this then, KOSPI bears:
Samsung has reportedly reserved ~70% of its memory production capacity through 2031 via LTAs with $NVIDIA(NVDA.US), $Microsoft(MSFT.US), and $Alphabet(GOOGL.US) as main counterparties.Five years of demand visibility…S
Imagine Celestial ($Marvell Tech(MRVL.US) acquisition) was public.
The valuation would probably be astronomical in US markets (if I had to guess, $6-10B)Because 2028 revenue projections were $500m (q4 annualized runrate), 2029 revenue projections were $1B.And because Celestial is a core part of hyperscaler CPO programs. Celestial's 2026 Q2 earnings would have been:- Close to $0 revenue (Marvell said "revenue and earnings since the acquisition were not material")- Losing -$12.5M/quarter ($50M/year)Would people who knew what they were talking about looking at qualification cycle players say...1. based on Celestial's Q2 P/S numbers and because it was losing -$12.5M a quarter... That it's a worthless meme stock? Or 2. with CPO hyperscaler opportunities for 2028, it should be valued at $6-10B? And I think that's a core cultural disagreement between US / EU cultures + markets. If you knew how to evaluate qualification cycle players, which number actually matters? I'd argue overwhelmingly the latter.S
It’s been a little disappointing to see a pattern with some people I've interacted with on X:
- try to engage with the same audience, then quickly move toward aggressively monetizing it - get upset when I choose not to participate in or amplify paid groups- throw out personal or illogical attacks and try to reframe that as simply disagreeing over fundamentalsWhen I first joined X, a lot of finance content revolved around watches/private jets + options, paywalled communities promising the "secrets of Wall Street," and squiggly-line charts.One of the things I've wanted to do differently is publish my research and reasoning openly, for everyone.I think this definitely resonated with folks given my follower growth. But of course, this growth can also create friction with people whose business models rely on using X to funnel audiences into paid services or expensive paywalls.My subscription has been $1 for months and will stay at the minimum, despite claims at the beginning I would raise it to $100. All of my core theses are published on the main timeline for free. I could put substantially more behind a paywall. I just don't want to. I just prefer sharing the ideas openly and letting everyone decide for themselves.Many ideas have worked out well: $AXT(AXTI.US), $Nebius(NBIS.US), $Aehr Test(AEHR.US), $Micron Tech(MU.US), $Intel(INTC.US), $EWY, $Marvell Tech(MRVL.US), $Lumentum(LITE.US), $RPI, $IQE, $SOI, $Tower Semicon(TSEM.US), $Arm(ARM.US), $Coherent Corp.(COHR.US), and a lot more. Others ran into unexpected industry delays, like $LPKF with glass substrates and Auros with hybrid bonding.Some are still playing out into 2027/2028, including $SIVE, Foci, Shunsin, $Churchill Capital XI(CCXI.US), $XFAB and the broader CPO/humanoid themes.Some are brand new like Etron/ESMT for DDR2/DDR3.And many like $Jabil(JBL.US) to Murata to $Maxlinear(MXL.US), I just share for fun to see if the idea is right. Not every idea will be right. That's part of research.But I'd much rather have an X where people openly publish the thesis and reasoning so everyone can learn from it. Than one where information increasingly disappears behind $100 paywalls or becomes diluted with engagement-bait noise. Hopefully I can help create a new culture on X rather than amplify the old one.
S![图片 1,共 1 张]()
I know everyone’s watching $NVIDIA(NVDA.US) earnings right now…
But did you know Landmark signed a 4 year CW agreement with US customer to ensure “sufficient supply”?So now you have:- $Lumentum(LITE.US) (capacity gone)- $Coherent Corp.(COHR.US) (capacity gone)- Landmark (capacity committed)- $Applied Optoelectronics(AAOI.US) (capacity for transceivers)- $Macom Tech(MTSI.US) (not online)- $Semtech(SMTC.US) (limited)I remember saying earlier this year CW lasers would be the next optical shift and heavily bottlenecked by Nvidia?So fun watching this play out, with players signing LTAs already to 2030 (signaling less availability for other players).Implications for $SIVE / Win Semi are very material as one of the few remaining CW merchant suppliers with capacity (+ CPO-grade lasers).Let’s see how they execute.S![图片 1,共 1 张]()
All right back to $Semtech(SMTC.US) movie: "The bottleneck go Brrr":
My favorite quote was: "availability currently matters more than pricing". In the current market for optical products. - No near-term erosion is expected on booked optical orders, which signals they're passing cost increases through fine.- I was actually curious most about Semtec's CW laser products after the HieFo takeover:Semtech expects CW-laser revenue for transceivers to begin H1 FY28. Explicitly said capacity is limited.They still seem materially further behind compared to the laser leaders, but they're making progress for 2027 ramp. - TIA and driver solutions remain in exceptionally strong demand (confirmed from $Applied Optoelectronics(AAOI.US) earnings). Continues to deepen engagement across all the leading hyperscalers. "We are now designing to every module provider", expected 50%+ market share for 1.6T FiberEdge (TIA + driver) by years end. Very strong statement to make about being majority market share. - 1.6T FiberEdge qualifications finishing earlier than expected (good read through for your pluggable makers eg. AOI)q: "quick thoughts on how long into 2028 does that backlog extend?"a: The backlog for the remaining of this fiscal year, I would say for our target is all booked. For the next year, we probably over 70% there.Management said current capacity may not be enough for fiscal 2028, especially in the second half (great demand visibility)Q2 revenue: - $341.9M vs. ~$329M expected- adjusted EPS was $0.71 vs. $0.61Q3 guidance was most exciting:$410M revenue vs. ~$360M revenue$1.05 EPS vs. $0.73 EPS. yeah... just look at that beautiful revenue inflection Q/Q. So gigantic beat, great read through on 1.6T ramp. I don't own Semtec, but these were amazing earnings.S![图片 1,共 2 张]()
![图片 2,共 2 张]()
I know everyone's focused on Nancy Pelosi copytraders sending $Bloom Energy(BE.US) up 11.83%. Or Trump...
But you know what else is cool? FAU bottlenecks for CPO. I remember saying earlier this year FAU/Foci might be a future bottleneck around $Taiwan Semiconductor(TSM.US) / $NVIDIA(NVDA.US) CPO roadmaps... This was some media commentary supporting that: "It is understood that Largan Precision (3008), FOCI (3363), and China’s TFC have entered $NVIDIA(NVDA.US) FAU supply chain""Based on an estimated 20,000 Spectrum-X systems shipped this year, the optical engines installed in those systems would require approximately 600k-700k FAUs" In 2027, demand is expected to reach several million units, and existing supply chain capacity is currently unable to meet demand." (UDN, mandarin -> english translation is kinda off)Cough cough, "existing supply chain capacity is currently unable to meet demand"Tad early right now since mass production is expected H2 2027, but cool to read updates around this.S![图片 1,共 1 张]()
$NVIDIA(NVDA.US), following their $20B deal... Announces Groq3 LPX now in full production.
With $Nebius(NBIS.US) the first to adopt through Nebius token factory.- 3,400 tok/s in Artificial Analysis benchmarking running Gemma 4 31B, with 100k token context- 4x faster responsiveness than the nearest alternativeThing that caught my attention.. was a former press release after Nvidia's $2B investment into Nebius. That it would support their "early adoption of Nvidia's latest generation" architectures. Guess we're seeing that special treatment here.