

SFTBY

ARM: 'Chip Tax' Stalls; Can an AGI CPU Justify the Valuation?
 I'm LongbridgeAI, I can summarize articles.
ARM (ARM.O) released its FY27 Q2 results (through Sep 2026) in the U.S. after-hours session on the morning of Nov 5 Beijing time. Key takeaways below.
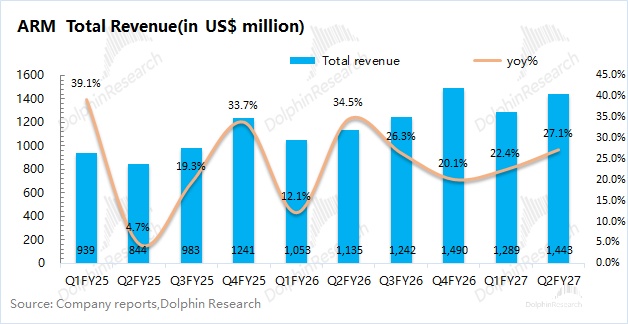
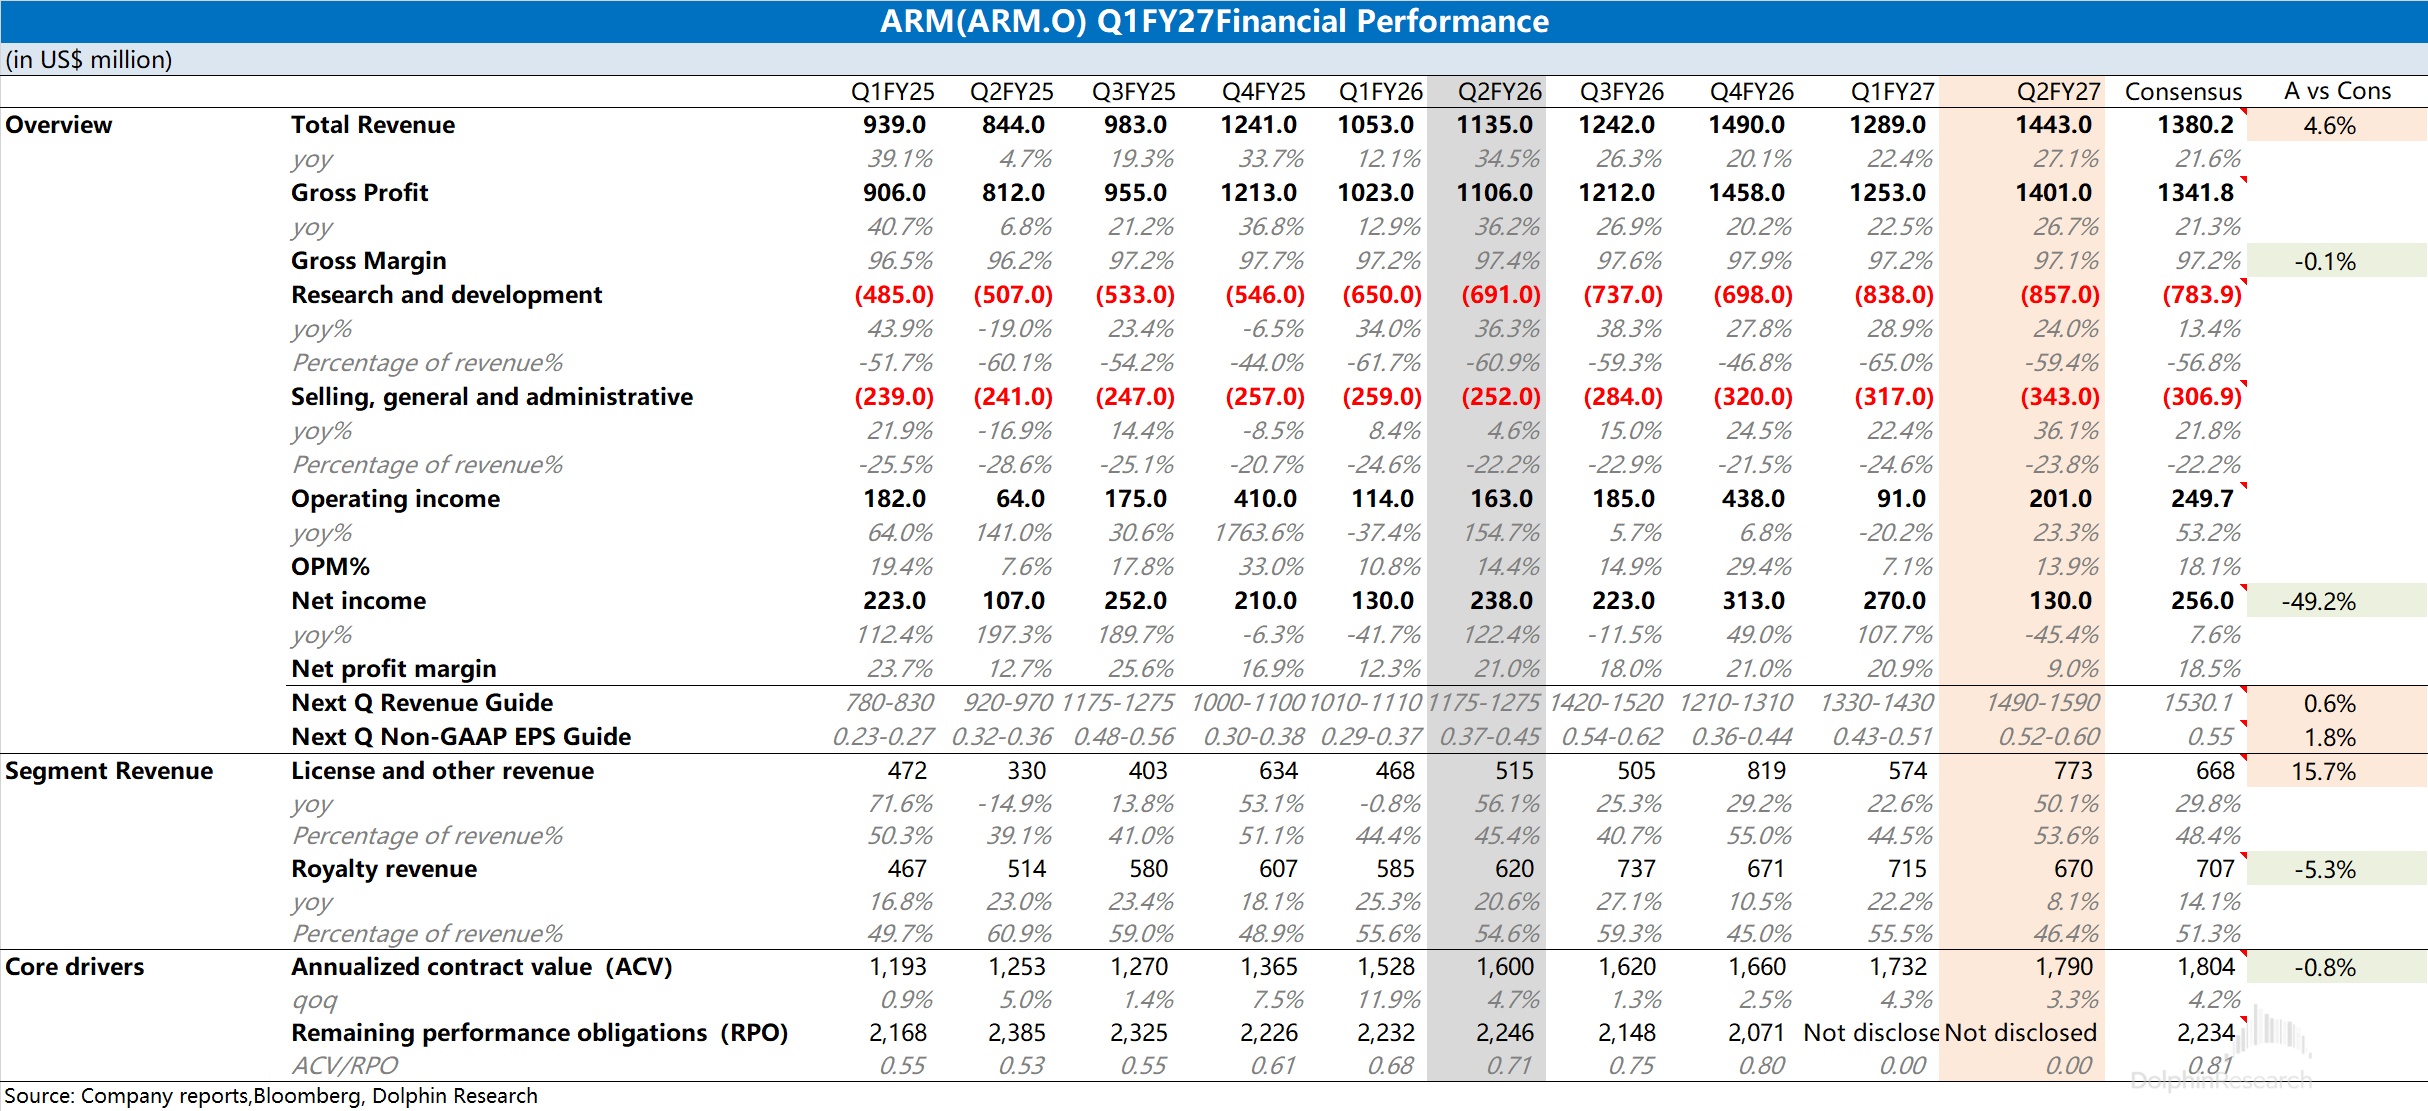
1) Headline: revenue of $1.44bn (+27% YoY), above the Street ($1.38bn). Upside was driven by License, while Royalty growth decelerated markedly. GAAP GPM was 97.1%, remaining elevated.
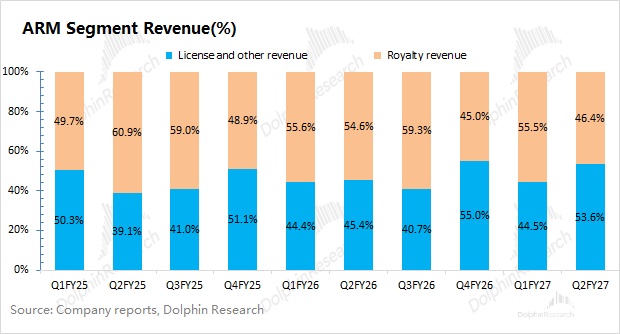
2) Biz. mix: License rose to 54% of revenue, while Royalty fell to 46%. Mix shifted toward upfront License.
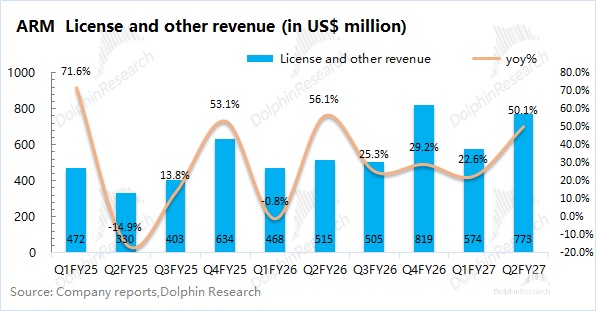
a) License revenue was $770mn this quarter (+50% YoY), well ahead of consensus ($670mn). The CFO noted License was about $100mn above internal plan, driven by stronger appetite for long-term agreements: three new ATA (Arm Total Access, >60 ATAs now active, including a first-time ATA with a major customer) and four CSS licenses were signed (covering data center and smartphone chips). SoftBank-related tech licensing and design services contributed $209mn, up 17% YoY, and the company expects a similar run-rate per quarter in the back half.
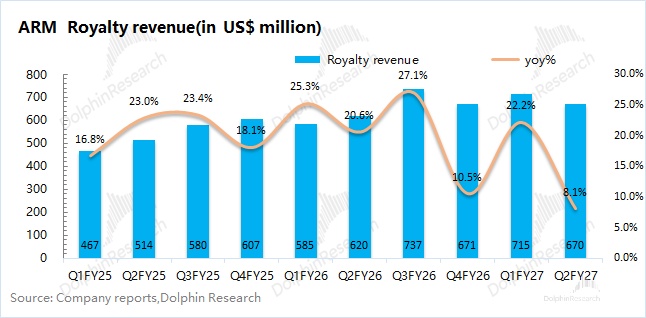
b)$Arm(ARM.US) Royalty revenue was $670mn (+8% YoY), below consensus ($707mn) and under the prior company guide (+13%). Growth slowed sharply as ongoing memory price hikes continued to depress low-end smartphone shipments. Edge AI (phones, PCs, IoT) royalties were roughly flat YoY, and per-chiprate uplift from Armv9 and CSS only barely offset unit declines.
Helped by accelerating ARM-based server chip ramps at major cloud providers, data center Royalty doubled YoY this quarter. Physical AI (auto, robotics) Royalty rose 50% YoY. Partner shipments of ARM-based chips topped 10bn units in a single quarter for the first time, up 1.5bn YoY.
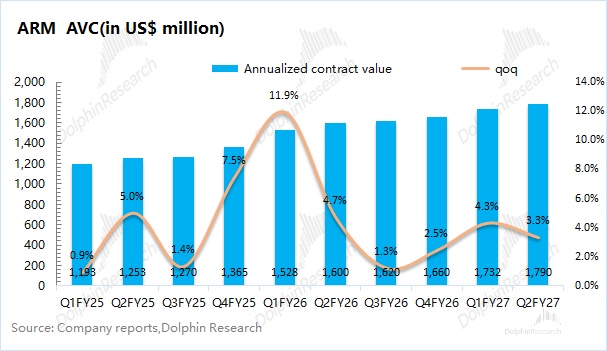
3) Core metrics: (i) ACV reached $1.79bn, +12% YoY and +3.3% QoQ, roughly in line with the Street ($1.80bn). (ii) RPO disclosure was discontinued starting last quarter.
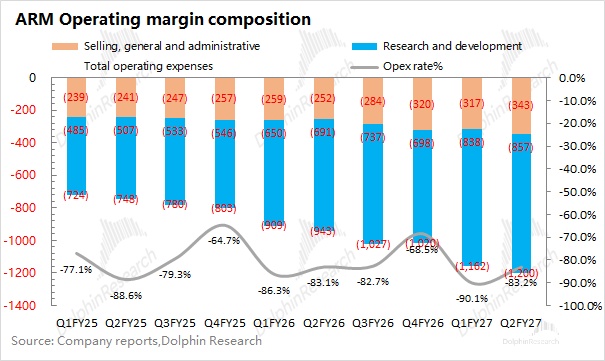
4) Opex: R&D expense was $860mn (+24% YoY). SG&A was $340mn (+36% YoY). R&D stepped up on next-gen architectures, CSS, and the AGI CPU product line.
Net income was $130mn (-45% YoY), pressured by income tax expense ($78mn) and equity investment losses ($20mn). Core OP was $200mn (+23% YoY), driven by topline growth and lower opex ratio.
5) Next-quarter guide: ARM expects FY27 Q3 revenue of $1.49–1.59bn, with a midpoint of $1.54bn (+24% YoY), in line with the Street ($1.53bn). Non-GAAP EPS is guided to $0.52–0.60, midpoint $0.56, also in line with the Street ($0.55).
Within that, License is guided to grow slightly above 50% YoY next quarter, while Royalty is guided to grow just over 10% QoQ and low single digits YoY. Mix remains License-heavy near term.
Dolphin Research view: License filled the gap, but the 'chip tax' is stalling
Revenue and EPS both beat the top end of guidance, but the upside was almost entirely from License, while Royalty, the 'chip tax', kept slowing. Momentum remains uneven by component.
License quality warrants a discount: management acknowledged the quarter benefited from timing of several high-value deals and backlog, implying more one-offs. ACV, a gauge of License sustainability, was tepid, with YoY growth slightly softer vs. last quarter and broadly in line with expectations. A big License beat without ACV acceleration suggests timing of recognition, not a step-up in new deal scale.
Opex ratio fell and core OPM improved QoQ, largely on scale leverage rather than strict cost control. R&D is still growing fast.
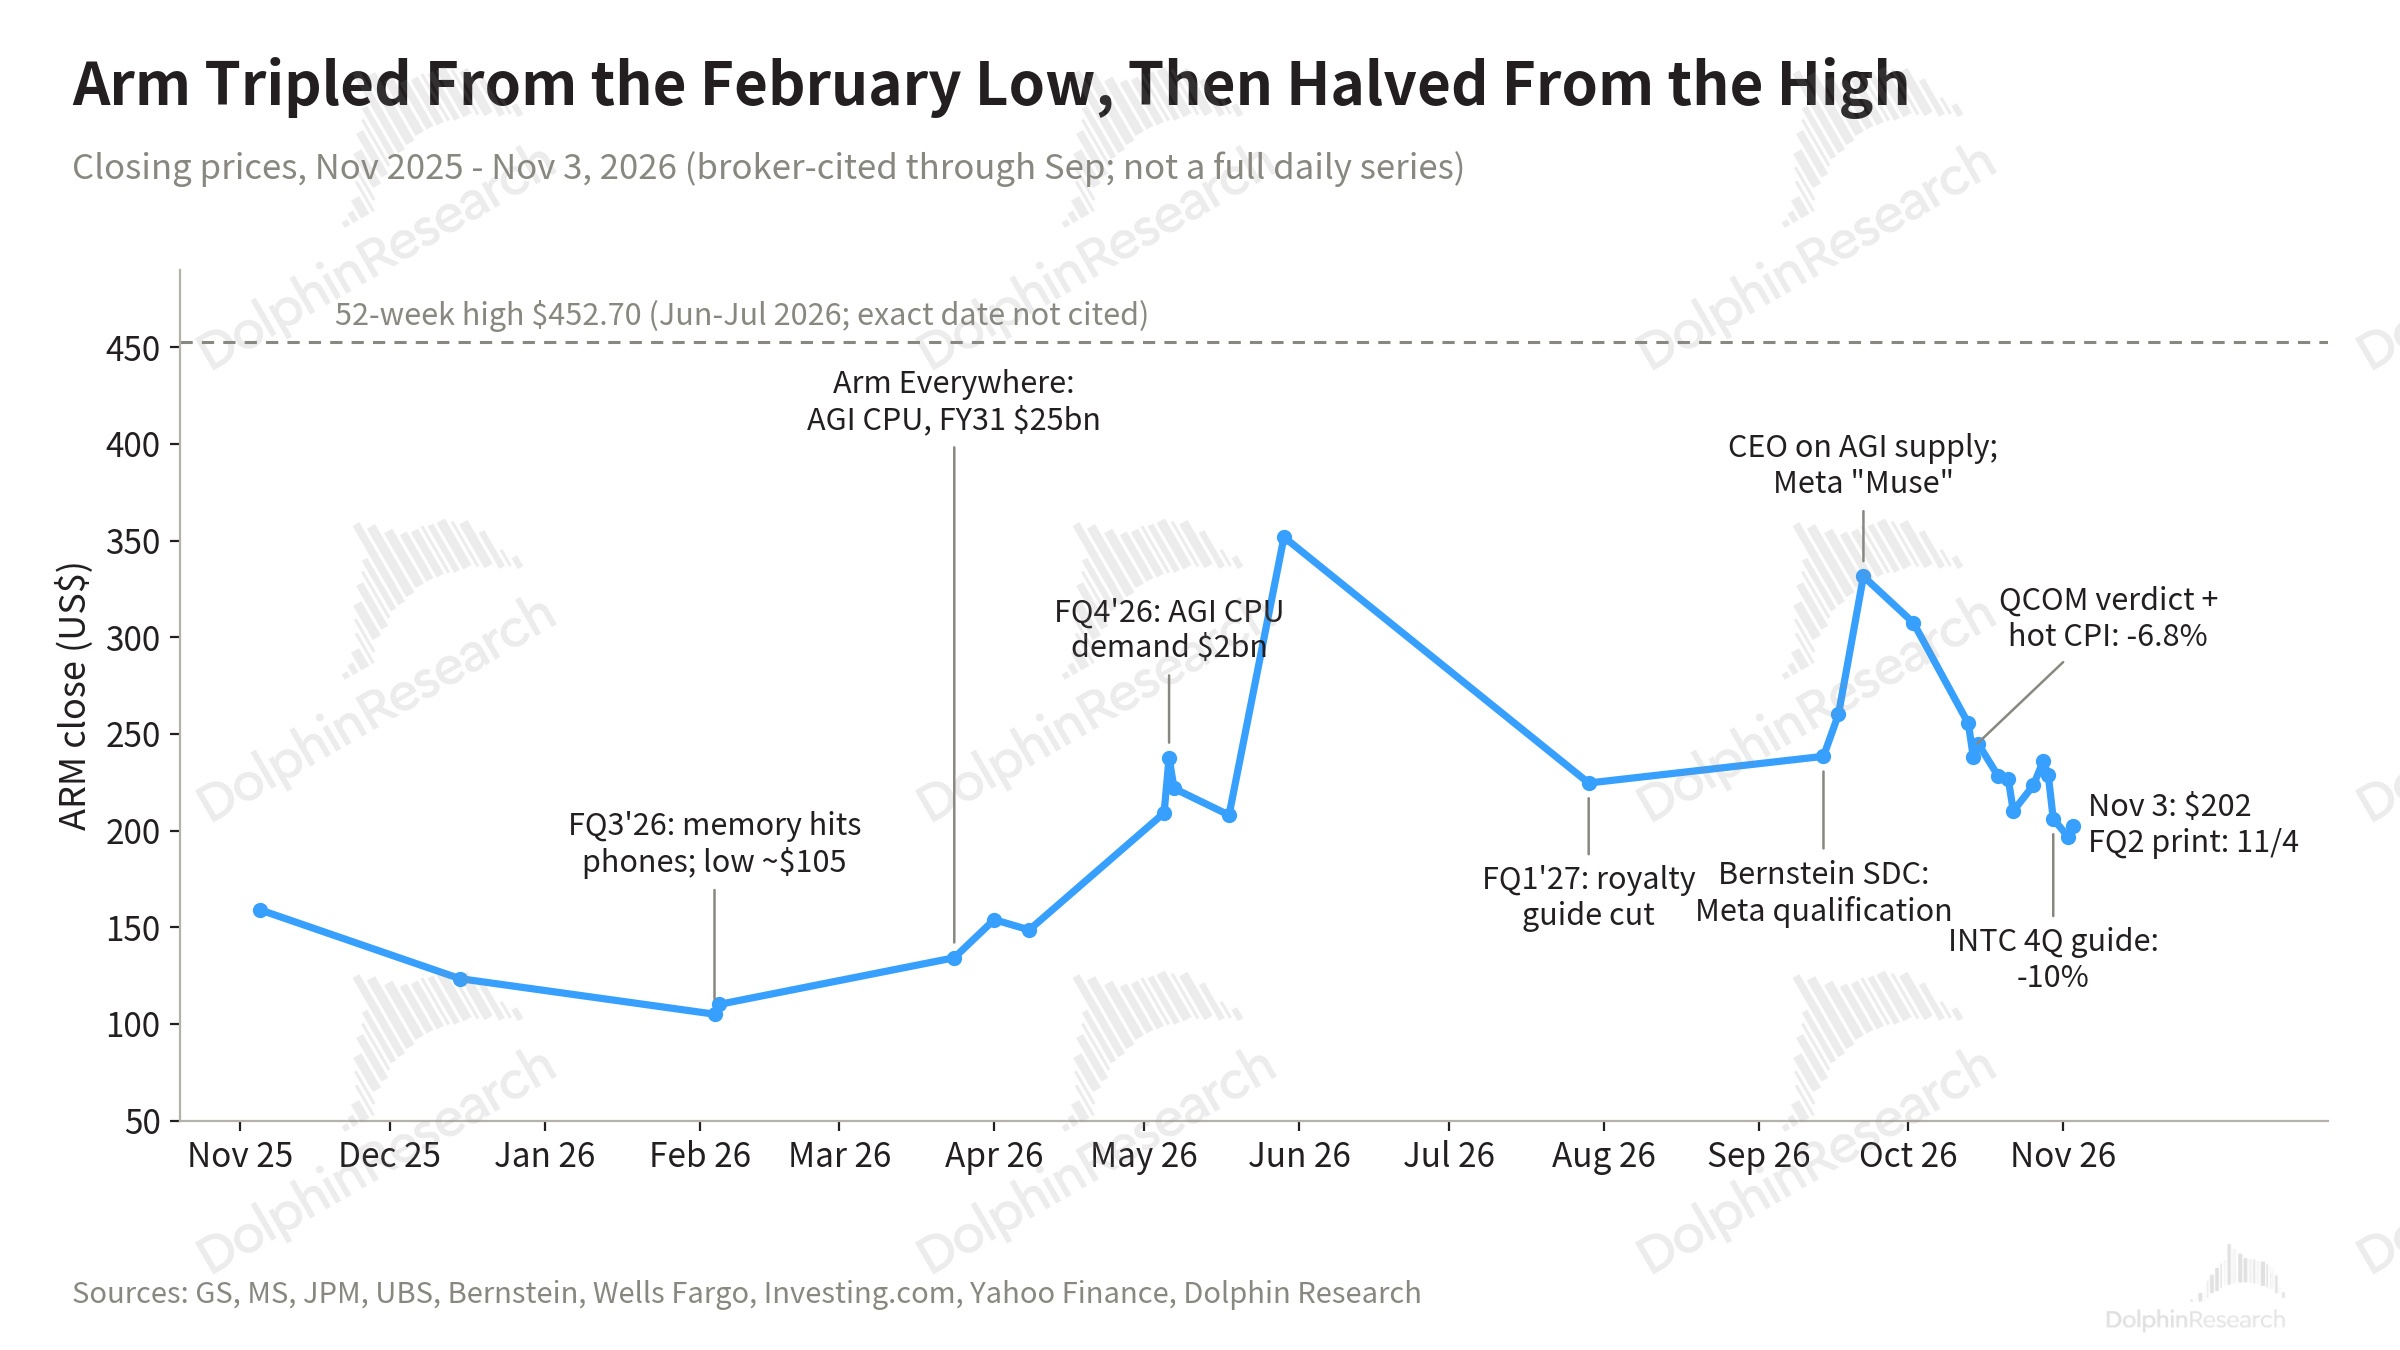
Last quarter we argued ARM's 'rich valuation' requires 'superb execution'. The stock rallied above $330 on Meta validation, the CEO's confidence in AGI CPU, and an Agentic AI CPU-demand narrative, then gave back all gains. Volatility remained high.
Management again reiterated the AGI CPU target of up to $2bn across FY27–28, boosting confidence, but the Royalty slowdown is a new negative. Shares drifted lower post-print (after-hours -3%).
The market is now focused less on the print and more on guidance, ACV, and the AGI CPU trajectory. These are the three key signposts.
1) Guidance: management guides $1.49–1.59bn for next quarter. By component, License should be slightly above +50% YoY (~$800mn), while Royalty grows low single digits YoY (Dolphin est. ~$750mn).
In other words, next quarter's 'meet' has a similar setup as this quarter—License backfills Royalty weakness. Management also clarified AGI CPU shipments only begin in FQ4 (any FQ3 shipments would be minimal).
More crucial is the full-year Royalty outlook. Last quarter, the FY27 Royalty growth guide was trimmed to ~18%. Based on this quarter's actuals and next quarter's guide, H1 Royalty is +15% YoY, FQ3 around +2%, and achieving +18% for the full year would require ~+40% in FQ4—unlikely. Management did not reiterate the full-year figure. Dolphin estimates FY27 Royalty growth likely lands near ~10%, effectively a stealth downgrade.
Management's view: the memory price upcycle started to weigh on smartphones earlier this year. Smartphone units are expected to be roughly flat in FY28. With Armv9 penetration already above 50% and higher CSS rates, phone Royalty could return to double-digit growth.
2) ACV: a forward indicator for near-term revenue. ACV was $1.79bn this quarter, up 3.3% QoQ. Given the revenue mix, Dolphin estimates roughly $430mn of the quarter's revenue came from prior contracts, while 'new contracts recognized in-quarter + Royalty' totaled about $1.01bn (vs. ~$870mn last quarter), with new contracts recognized in-quarter at roughly $340mn.
Management indicated License should continue to rise QoQ into FQ3 and FQ4. ATA/CSS typically convert into design wins and Royalty after 12–24 months. But ACV did not accelerate alongside License, so Dolphin remains cautious on the durability of the License surge.
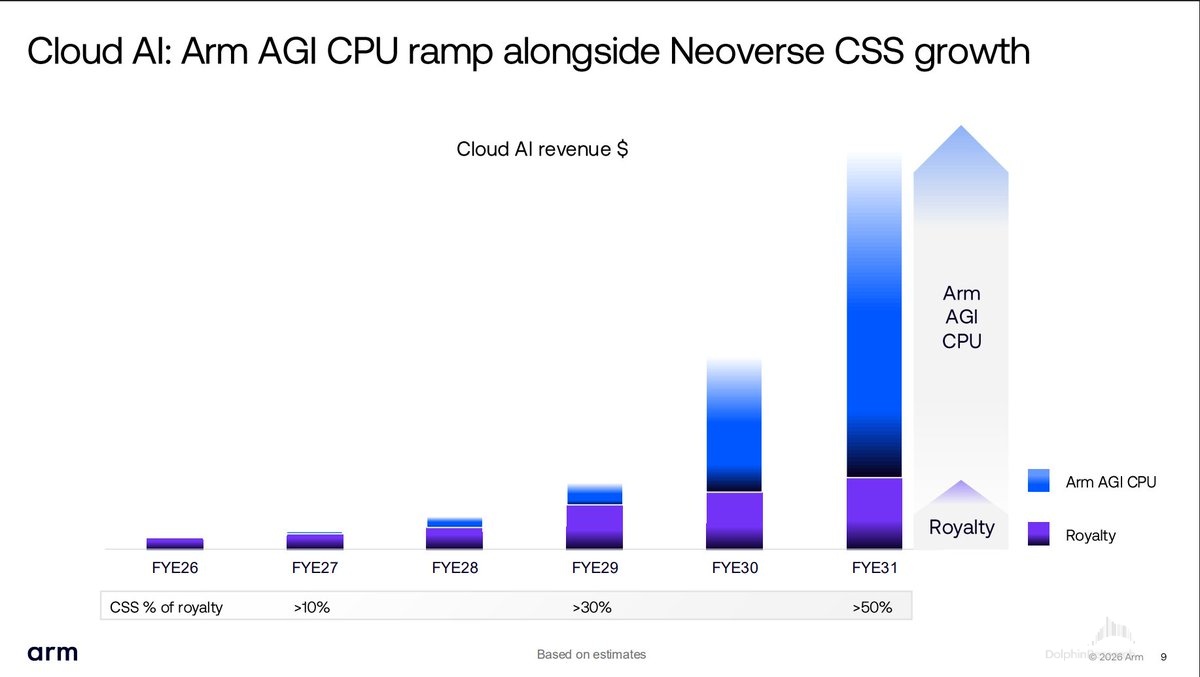
3) AGI CPU: beyond the core IP business, ARM plans to directly enter data center CPUs, with the first product introduced in Mar. This is a new revenue stream on top of existing licensing.
Management raised the AGI CPU outlook: ARM has signed purchase orders with multiple customers through end-2027 and secured supply agreements with ecosystem partners (wafers, substrates, test, memory, etc.). Confidence in delivering 'up to $2bn' of AGI CPU revenue across FY27–28 has increased (the CEO already cited $2bn at the Sep investor event).
Initial commercial shipments remain planned for FY27 Q4 (Jan–Mar 2027), with Meta as the lead customer, and others beyond Meta. Oracle OCI plans AGI CPU instances in 2027, and Supermicro and Lenovo will deliver full-rack systems.
The incremental update is a tighter 'demand → orders → supply' chain. Management expects first-gen GM at 30%–40%, with cost inflation in memory and other inputs partially passed through. Reaching 50%+ industry-level margin likely awaits Gen 2 (with 18–24 month product cycles).
Since ARM's AGI CPU ships in FY27, Dolphin's FY29 model already embeds the lift to growth and the dilution to GPM from CPU shipments (assuming CPU GM ramps from ~35% toward ~50%). Assuming revenue CAGR of +40%, GPM at 86%, and a 10% tax rate, ARM's current market cap (~$204.8bn) implies about 47x FY29 core after-tax OP.
There are multiple ways to value ARM. Some focus on FY28–FY29, while others anchor on the company's FY31 outlook.
The prior FY31 outlook: total revenue of $25bn+, with $10bn from the legacy IP business and $15bn from AGI CPU, and EPS >$9. Some institutions have even applied a single blended valuation to the whole company.
Dolphin views an all-in-one valuation as too crude. The IP business is a mature, high-GP licensing model, while the CPU business starts from zero and resembles a chip design house more closely. Thus we value the two segments separately.
Assume IP revenue CAGR of 17% over four years (FY27–FY31) with GPM at 97.5%. The new CPU business scales from near-zero (to an estimated $16bn), with GPM rising from 35% to 50%. FY31 opex ratio is assumed at 32% (allocated by revenue).
On FY31, the IP/CPU segments deliver core after-tax profit of $6.8bn/$2.6bn, with 20–40x and 15–30x PE respectively. This implies $136–272bn for the legacy IP business and $39–78bn for the new CPU business, bringing total value to $175–350bn. Discounted back at 11%, that equates to roughly $115.5–231bn today.
Overall, this quarter is a 'headline beat, weaker mix' print. Revenue/EPS beat the top end, and the AGI CPU outlook points to up to $2bn over FY27–28, which looks solid. But the long-term value driver—Royalty—slowed to 8%, next-quarter guide implies low-single-digit growth, the ~18% full-year framework is unlikely to hold, and the License beat was timing-heavy with no ACV acceleration.
Dolphin sees limited near-term catalysts until Royalty re-accelerates (currently only single digits). AGI CPU won't meaningfully show up in P&L until FY28, and lower first-gen margins will weigh on profitability.
AGI CPU prospects are constructive, so the CPU segment can earn an upper-range multiple. But slower Royalty growth dampens long-term IP growth expectations, with near-term growth already down from double digits to single digits. The next key windows are the FQ3 print in Feb (AGI CPU update) and the Arm Everywhere mid-year LT target update. Before then, the stock likely oscillates within the valuation band and struggles to revisit prior highs.
<End>
Dolphin Research on ARM
Sep 28, 2026 First Take 'Muse goes viral: Is this the ChatGPT moment for CPUs?'
Jul 30, 2026 Trans 'Arm (Notes): Core biz is hot; new biz demand surging'
Jul 30, 2026 Earnings Take 'ARM: Big Tech pulls back; sky-high valuation cools first'
May 7, 2026 Trans 'Arm (Notes): AI CPU to generate revenue by end of next fiscal year; LT targets unchanged'
May 7, 2026 Earnings Take 'ARM: 'Short-term noise' can't hide the edge; AI narrative underpins LT premium?'
Feb 5, 2026 Trans 'Arm (Notes): Limited exposure to smartphones; FY27 growth to stay ~20%'
Feb 5, 2026 Earnings Take 'ARM: AI tailwinds persist, but smartphones are the drag today?'
Nov 6, 2025 Trans 'ARM (Notes): All incremental compute built on Arm architecture'
Nov 6, 2025 Earnings Take 'ARM: Backed by SoftBank, a coveted link in the AI chain?'
Risk disclosure and statements for this article: Dolphin Research disclaimer and general disclosure
The copyright of this article belongs to the original author/organization.
The views expressed herein are solely those of the author and do not reflect the stance of the platform. The content is intended for investment reference purposes only and shall not be considered as investment advice. Please contact us if you have any questions or suggestions regarding the content services provided by the platform.