

STXU

Dolphin Daily | Heavy fine for GOOGL, reward for MSFT? Results rule.
 I'm LongbridgeAI, I can summarize articles.
Good morning. It is Beijing time Oct 29, 2026, and Dolphin Research brings you a one-glance take on global markets.

Trading focus: MSFT Azure up 48% with shares higher after-hours, while GOOGL search slows and FCF turns negative, dropping nearly 10% post-close. SK Hynix’s 'sold out through 2029' comment sparked a rally in memory and Korean equities, and NOW and FTNT plunged after-hours, weighing on software.
Macro tone: The Fed held rates, but two votes favored a hike and the statement upgraded its economic assessment. The 2Y UST fell 4bp and the 10Y rose 2bp to 5.02%, while Iran rejected a ceasefire draft and WTI rose 2.9%.
Key movers: SOX +1.8%, led by memory and equipment, with VRT +16.5% and ORCL +10.7%. Nasdaq futures -1% after-hours as software and the AI complex gave back gains.
Near-term watch:
Today: Samsung Electronics reports. The FCC votes on the sat-to-cell spectrum proposal (SPCX).
Tonight: 20:30 US Q3 GDP and Sep PCE, and 21:15 ECB decision. These are key prints for inflation and rate expectations.
Tomorrow morning: AMZN, INTC, and SNDK report. All three are in focus for cloud, CPUs, and NAND pricing respectively.
Next week: AAPL and PLTR (11/2), US midterms and AMD (11/3). Anthropic is reportedly eyeing an IPO the week of 11/16.

$Microsoft(MSFT.US) $Alphabet(GOOGL.US) $Alphabet - C(GOOG.US) , $SK Hynix(SKHY.US) ,$Micron Tech(MU.US) $Samsung Electronics (SSNGY.US) $Sandisk(SNDK.US) , $Seagate Tech(STX.US) $Oracle(ORCL.US) $Service Corporation International(SCI.US) $Fortinet(FTNT.US) ,$Lumentum(LITE.US) $Marvell Tech(MRVL.US) $Coreweave(CRWV.US) $NVIDIA(NVDA.US)
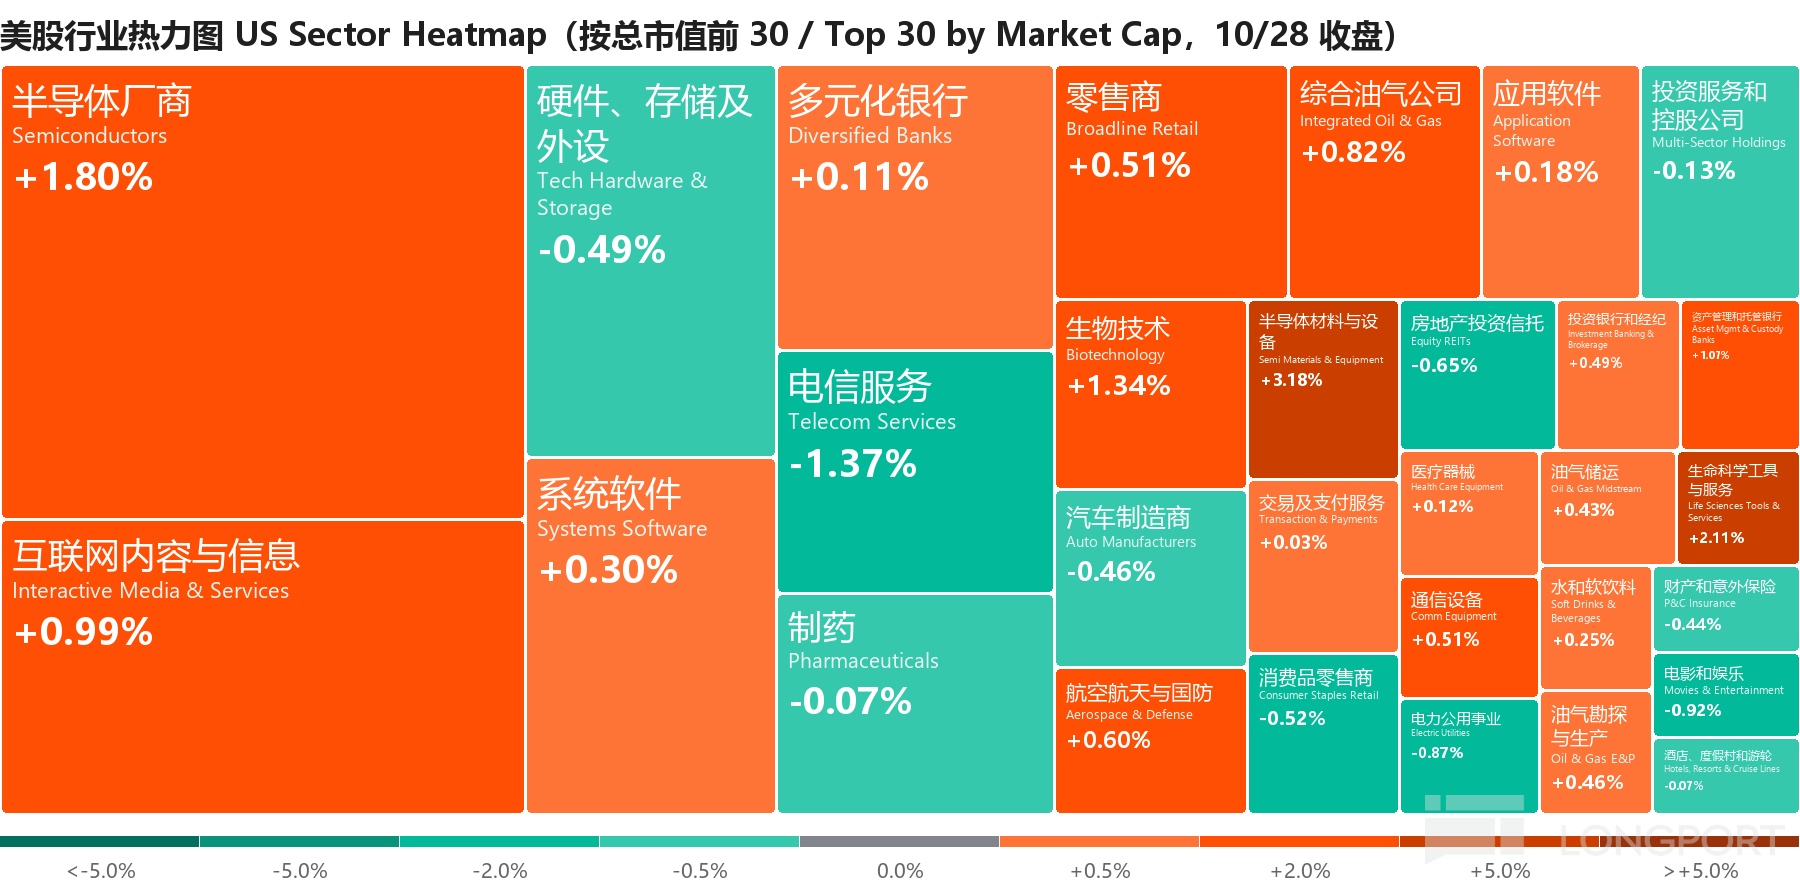
Performance windows: For US equities and global assets, moves are vs. the 10/28 close (after-hours around 20:00 ET). For Japan and Korea, moves are today’s open vs. prior close.

1. Same cash burn, different verdicts: MSFT rewarded, GOOGL punished as the market scores AI on cash flow
GOOGL +1.3% (post -9.9%) / MSFT -0.1% (post +2.9%)
Two reports on the same night: MSFT’s Azure revenue was $33.17bn, up 48%, topping the 44–45% guide and buyside at 46–48%. It guided next quarter to 49–50%, with shares up as much as 7% after-hours.
MSFT capex (incl. leases) was $45.2bn, below the '>$50bn' guide, and FCF of $18.6bn was far above the roughly $8.5bn expected. Next quarter capex is set to exceed $50bn and approx. $170bn for the calendar year, with the blemish being commercial bookings down 12% YoY.
MSFT recognized about $10bn of revenue from OpenAI this quarter, ~11% of total, and OpenAI still owes $7.2bn in receivables. CEO Nadella said the first batch of NVDA Vera Rubin is now available on Azure.
GOOGL was 'cloud strong, core weak': cloud revenue rose 103% to $30.7bn but fell short of the buyside’s $31–32.5bn. Search rose 12% to $63.35bn, below the 14.7% consensus and buyside 13–14%, vs. +17% in Q2, while YouTube ads were only +9%.
GOOGL capex was $51.4bn, ~40% of revenue, with FCF at -$9.1bn. EPS of $2.12 badly missed the $3.02 estimate, mainly due to an ~$8.6bn paper loss on SPCX holdings, and even ex that EPS of ~$2.67 still missed.
GOOGL left 2026 capex guidance unchanged but still signaled a meaningful increase in 2027, with buyside modeling around $350bn. The CFO flagged compute tightness and the use of third-party capacity, which will pressure cloud margins near term.
On flows, MSFT is seen as a 'crowded long' and GOOGL a 'crowded short', and longs were rewarded while shorts took profits. Both companies’ 5Y CDS hit new highs ahead of earnings.
AI proxies broadly faded after-hours: CRWV -4.4%, NBIS -5.1%, MU -2.5%, and AVGO -2.2%, with Nasdaq futures -1%. The market’s scoring rubric is: chase capex beneficiaries on 'how much you invest', but for CSPs the focus is whether monetization and cash flow keep pace.
Dolphin take: MSFT’s key Azure growth met the bullish end of buyside expectations and is set to re-accelerate next quarter. (First Take)
GOOGL’s search deceleration validates the AI erosion narrative. The post-close break below $300 nears the divergence level we flagged, but sentiment may still cap the multiple near term. (First Take)
2. SK Hynix 'sold out to 2029': is memory shifting from cycles to 'contracted infrastructure'?
SKHY +13.3% (ADR) / SK Hynix +10.9% (Seoul) / Samsung Electronics +9.0% (Seoul) / MU +5.9%
SNDK +7.7% / LRCX +5.4% / AMAT +5.1% / STX +4.5% / KLAC +3.3% (post +3.7%)
Korean media report BABA, Tencent, and ByteDance are seeking DRAM LTAs up to 10 years. Some channel checks note Huaqiangbei DDR5 spot has pulled back with Oct volumes down 20–30%, suggesting consumer cooling, while Reuters says CXMT plans small-batch advanced AI memory despite poor yields.
STX is the weak link in the memory chain: price per TB rose 16% QoQ, but shipments were up only 1% EB and unit cost rose ~3%, with Dec guidance below the buyside. It fell 2.5% pre-market but closed up 4.5% with the memory rally.
Equipment stocks followed higher on expected capex hikes at SK Hynix next year. KLAC posted after-hours with Dec-quarter revenue guidance of $4.7bn, above the $4.49bn consensus.
Dolphin take: SK Hynix’s upside is in mix — pricing beat, shipments to accelerate next quarter, quantified LTAs with >50% coverage, and heavy buybacks/dividends underpinning shares. Near- to mid-term earnings look safe, but the real debate is how long the upcycle lasts. (Earnings Review)
STX is 'price > expected, volume < expected', and HAMR cost-down did not show up in the numbers this quarter. (Earnings Review)
3. Software carnage after-hours: why did 'beats' drop 18% and 26%?
FTNT -5.9% (post -25.9%) / NOW -3.0% (post -18.0%) / PANW -1.8% (post -6.2%) / CRWD -0.5% (post -6.4%) / CRM +0.5% (post -5.6%)
NOW subscription revenue of $3.99bn merely met consensus, below the buyside’s $4.01–4.03bn. cRPO grew 21% at constant FX, below the buyside’s 21.5–22%.
The guidance hurt more: Q4 cRPO +18.5% vs. 19% consensus and bulls’ 19.5–20%, or ~17% ex-M&A. Q4 OPM guide at 32% trails the 33.5% consensus, and AI deployment spend shaved 50bps off subscription growth.
FTNT beat on revenue and EPS, but product revenue grew 37% vs. buyside’s >50% and +52% in Q2. Services revenue of $1.31bn missed, and full-year services revenue guidance was cut to $5.15–5.17bn.
FTNT’s Q4 revenue guide of +15.5% fell short of bulls’ 18–19%, and FFIV also fell 20% the same day. The bear case that the firewall replacement cycle has peaked took the upper hand.
FTNT is up 119% YTD, and with lofty expectations, narrower beats drew heavy penalties. Cyber and broader SaaS fell roughly 6% after-hours, and CRM also dropped 5.6%.
4. ORCL sets a payback timetable, VRT orders double: AI infra money and orders are still flowing
VRT +16.5% / ORCL +10.7% / CRWV +7.3% / NBIS +7.0%
AAOI +6.8% / LITE +5.5% (post +8.8%) / MRVL +3.3% (post -8.1%)
ORCL Investor Day: FCF to turn positive in 2H FY2028 and exceed $30bn in FY2029, with capex down in FY2029. This directly addresses concerns over leveraged expansion.
Before FY2030, new financing is capped at $20bn ($10bn equity and $10bn debt). Net debt/EBITDA will be kept within 3.5x.
ORCL also set targets for FY2030 of revenue ≥$225bn (35%+ CAGR), OPM ≥40%, and EPS ≥$21. New cloud names rallied in tandem, and on 10/27 ORCL confirmed deploying GOOGL TPU on OCI starting 2027.
VRT 3Q revenue was $4.31bn, organic +55% vs. buyside ~37%, its largest beat since listing. Organic orders doubled, full-year organic growth was raised to 37–39%, and 4Q guidance merely matched buyside numbers.
Optical components rallied during cash hours, then another twist after-hours: Bloomberg reported MRVL is in advanced talks to acquire LITE (mkt cap ~ $83bn), with an announcement as early as next week. LITE jumped as much as 17.8% after-hours.

1. The Fed held, but two voters sought a hike (10/28)
Decision: Rates unchanged at 3.75%–4.00%, with a 10–2 vote as Cook and Hummack favored a 25bp hike. The Bank of Canada hiked 25bp to 2.5% the same day, its first in over three years.
Statement: The economic view was upgraded from 'solid' to 'strong'. It dropped 'policy will help inflation return to 2% more promptly' and said it needs more information to judge stance.
Waller remarks: Starting in 2027, one meeting a year will discuss strategy without a vote, and he refused to pre-judge Dec. He also said AI investment is subject to rate sensitivity.
Rates reaction: 2Y -3.95bp to 4.70% and 10Y +2.08bp to 5.02%, with the curve spread widening to 32bp. JP Morgan believes as long as EPS growth exceeds 15%, US equities can digest a 10Y rising to 5.5%–6.0%.
For tech: The front end fell, but the long end stayed above 5%. High-valuation, FCF-negative AI names are more rate-sensitive, and only true growers with earnings can withstand higher rates. Tonight’s PCE is the next puzzle piece for a potential Dec hike.
2. More volatile assets (10/28)
SOX +1.8% to 11,684: memory and equipment led, with the semi equipment sub-index +3.2%. Nasdaq futures -1% after-hours.
WTI Dec +2.9% to $102.78: Iran rejected the ceasefire draft conveyed by Qatar, and the US has notified Gulf states to prepare for post-midterm military action. Brent Dec +1.3% to $115.32.
VIX -3.5% to 16.9: vol eased after the Fed decision.
3. Asia open and today’s setup (10/29)
Asia tape: Nikkei +0.3% and KOSPI +0.1%, with SK Hynix +1.6% and Samsung Electronics -0.4% (reports today). Hang Seng futures night session +0.2% and FTSE A50 futures about -0.1%.
Memory: Korea largely priced SK Hynix’s print yesterday, and today hinges on Samsung’s report. A-share memory and equipment map to the theme, but Huaqiangbei spot pullback flags consumer cooling.
GOOGL complex and software: GOOGL down nearly 10% after-hours and Nasdaq futures -1% imply pressure on HK tech and A-share GOOGL chain names in optical modules and TPU-related. Cybersecurity and SaaS screens weaker.
Compute infra: MSFT Azure re-accelerated, ORCL laid out a cash-flow path, and VRT orders doubled. Liquid cooling, power systems, and compute leasing are relatively favored.


NVDA|$5.20tn|-1.2% (post -0.7%)
Reuters: The US DOJ is probing how NVDA’s $12.93bn acquisition of Hugging Face would affect AI competition. It continues to investigate NVDA’s acquisitions, investments, and alleged pressure on customers.
AVGO|$1.68tn|+2.8% (post -2.2%)
Traded weaker after-hours following GOOGL. Our diligence suggests GOOGL Cloud’s surprise may tie to TPU shipment cadence, e.g., v8i slipping a quarter. (First Take)
CBRS|-5.7%
Short seller Culper disclosed a short, alleging wafer-level chip field life of only 1.2–2.5 years. Shares fell as much as 11% intraday to a record low since listing, which Reuters could not independently verify.

AAPL|$5.02tn|-0.9% (post +0.6%)
Launched the first touch-screen MacBook Pro with OLED and M5 Pro/Max chips, starting at $2,899 for 14 inches. Ahead of 11/2 earnings, iPhone Duo sold out at launch, and the market is focused on supply build and storage price hikes’ impact on GPM.

SPCX|$1.97tn|-2.3% (post -1.1%)
The three major carriers asked the FCC to remove ~290MHz of spectrum from the sat-to-cell proposal, with a vote today. GOOGL booked an ~$8.6bn paper loss in Q3 on its SPCX holdings.

GEV|-1.9%
3Q EBITDA was $1.94bn vs. $1.69bn expected, with full-year guidance raised again, buybacks doubling to $20bn, and a $9bn acquisition of Trench. The debate is about gas turbines, with 11GW of new orders and ~20GW each in 1Q and 2Q.

InnoLight 300308.SZ|$111.7bn|prior close +10.3%
A-share optical modules led yesterday, while peer TFC reported 3Q net profit +55% and said core material tightness has eased markedly.


| Date | Event | Focus |
| 10/29 | Samsung Electronics 3Q | HBM4 share and LTAs |
| 10/29 20:30;21:15 | US Q3 GDP, Sep PCE, Jobless; ECB rate decision | Inflation and Dec hike odds; policy stance amid energy inflation |
| 10/29 post-close | AMZN, INTC, SNDK earnings | See previews below |
| 11/2 post-close | AAPL, PLTR earnings | See previews below |
| 11/3 | US midterms; AMD, ANET earnings | Middle East backdrop post-election |
| 11/4 | ARM, QCOM earnings | AI CPU and handsets |

AMZN|post-close 10/29
Watch: CEO Andy Jassy said 2026 capacity is sold out and 2027 is basically sold out, with full-year capex raised to ~ $220bn. The market will watch whether AWS growth can match MSFT and GOOGL’s cloud acceleration.
Dolphin focus: AWS revenue growth and backlog, capex vs. FCF, and Anthropic-related compute revenue.
INTC|post-close 10/29
Watch: CPU price hikes and AI inference are boosting server CPU demand, and the stock has already recovered sharply. The market will look for foundry customer progress to keep pace.
Dolphin focus: DC and AI revenue, GPM, 18A/14A foundry customers, and capex.
SNDK|post-close 10/29
Watch: SK Hynix NAND ASPs are up mid-20% and Kioxia surged, and the market expects NAND price gains to continue. The debate is that NAND price increases decelerate the fastest.
Dolphin focus: NAND ASP and bit shipments, enterprise SSD mix, and LTA coverage.
AAPL|post-close 11/2
Watch: iPhone Duo sold out with full-year shipment targets raised. Storage price hikes’ pressure on hardware GPM is the main concern.
Dolphin focus: iPhone revenue and Dec-quarter guide, GPM, and services growth.
Recent Daily Recap
2026-10-28: Daily Recap | AI prospectus revives AI investing as 'growth' memory gets no credit?
2026-10-27: Daily Recap | Anthropic reports, Meta’s $95bn drain, and AI panic eases?
<End>
Risk disclosure and statement: Dolphin Research disclaimer and general disclosures
AMD
USAMD
Amazon
USAMZN
Seagate Tech
USSTX
Broadcom
USAVGO
Applied Materials
USAMAT
SK Hynix
USSKHY
SK Hynix US SDR 100to1
SGUNXD
Alphabet - C
USGOOG
Alphabet
USGOOGL
Alphabet Inc Pref Shares GOOGN 6.25 05/15/2029
USGOOGN
MSFT
USMSFT
002245
SZ002245
SKHYV
USSKHYV
09988
HK09988
89988
HK89988
HBBD
SGHBBD
BABA
USBABA
AAPL
USAAPL
SK
USSK
SSNGY
USSSNGY
The copyright of this article belongs to the original author/organization.
The views expressed herein are solely those of the author and do not reflect the stance of the platform. The content is intended for investment reference purposes only and shall not be considered as investment advice. Please contact us if you have any questions or suggestions regarding the content services provided by the platform.